Categories
Brandon Blog Post

GTA Real Estate Developer Insolvency: Two Very Different Outcomes – Why Acting Early Beats a Seriously Challenging Two-Year Court Process

I hope you, your team and your project are safe and managing as well as possible. When a real estate developer or construction business begins missing payments, facing liens or losing access to financing, the pressure can be overwhelming. Seeking advice early is not an admission of failure. It is a sign of responsible stewardship. The sooner we understand the problem, the more options may remain.

Real Estate Developer Key Takeaways

  • A CCAA restructuring can be a valuable and appropriate lifeline, and many proceedings succeed.
  • The lesson from the 1111 Clarkson Road receivership real estate developer story is not that the Companies’ Creditors Arrangement Act (CCAA) is bad. It is that time is a cost, particularly when a transaction remains uncertain.
  • Hedge Road Landing demonstrates how a creditor-led CCAA process can create a defined period to pursue restructuring and project completion.
  • Value can erode through professional fees, interest, deteriorating assets, loss of trades and staff, and changing market conditions.
  • A real estate developer should seek advice after a missed lender payment, loan default, growing construction liens, CRA arrears, a stalled project, a lost investor or an inability to fund the next phase.
  • Early advice can preserve optionality: refinancing, a sale, a proposal, a consensual workout or a properly structured court process.

Real Estate Developer Highlights

Why does speed matter in a distressed development?

A development is not static while its real estate developer owner considers their options. Every month can affect construction costs, financing availability, municipal requirements, purchaser confidence and the willingness of trades to remain involved.

A prolonged process may also create:

  • Professional fees for real estate developer legal counsel, monitors, financial advisers and other professionals;
  • Accruing interest and lender fees;
  • Deterioration, security and insurance costs for unfinished property;
  • Loss of key employees, consultants and subcontractors;
  • Difficulty re-engaging trades who are owed money;
  • Changing home prices, absorption rates and construction costs; and
  • Reduced confidence among investors, purchasers and financing sources.

This does not mean that a quick decision is always the right decision. A complex real estate developer project may genuinely require a longer court-supervised process. The CCAA is often the only realistic framework for a large or complicated insolvency. However, delay should be treated as an economic decision, not as a neutral passage of time.

The practical question is: what does each additional month buy the project? If it creates a credible path to financing, completion or sale, the cost may be justified. If it merely postpones an inevitable enforcement process, value may be lost.

What happened at 1111 Clarkson Road in Mississauga?

The 1111 Clarkson Road development provides a cautionary example of a debtor-led restructuring that did not produce a completed transaction for this real estate developer.

The real estate developer debtor companies (Clarkson Road Developments GP Inc., Clarkson Road Holdings Inc. and 2813427 Ontario Inc.) obtained CCAA protection in May 2024 after defaulting on a $20 million vendor take-back mortgage.

Before filing, the real estate developer had contacted more than 60 potential investors or purchasers. The reported objective was to identify a third party willing to satisfy the mortgage and prior-ranking claims. No such third party was found at that stage.

One of the project’s principals incorporated 1000861289 Ontario Inc. to act as a stalking horse bidder. A stalking horse bidder is a proposed purchaser whose bid establishes a baseline for a court-supervised sale process. The investment agreement was approved as the stalking horse bid for a sales and investment solicitation process, or SISP. It ultimately became the only qualified bid received.

The proposed transaction then encountered a significant construction-lien priority issue. Construction lien claimants successfully challenged the priority of the first mortgagee, requiring the parties to restructure the transaction.

In 2025, the investor and the real estate developer negotiated an amended transaction. Under that arrangement, the investor would pay or assume claims ranking ahead of the construction liens and contribute $22 million in cash at closing.

The court approved the revised transaction in September 2025, but closing depended on the investor securing exit financing. The DIP facility (debtor-in-possession financing, meaning funding advanced while a debtor remains under court protection) was increased from $5.875 million to $7.2 million to fund the project while the parties worked toward closing.

By February 2026, the required financing had not been secured. The transaction did not close. Further DIP funding was unavailable, and the CCAA stay expired on February 28, 2026 without renewal.

The DIP lender later declared defaults, delivered a formal demand in August 2026 and sought the appointment of a court-appointed receiver. The investor, which held two perfected construction lien claims totalling more than $25 million, pursued its own receivership application nominating a different licensed insolvency trustee to act as court-appointed receiver.

On September 8, 2026, Justice Cavanagh approved the investor’s receivership application nominating its choice of receiver. That licensed insolvency trustee had previously acted as CCAA monitor and was familiar with the project, prior marketing efforts, stakeholders and outstanding issues. The court concluded that the CCAA proceedings had not produced a viable transaction for this real estate developer and its stakeholders and that a neutral third-party court officer was needed to control the next stage.

The facts are specific to this real estate developer proceeding. They do not establish that any party acted improperly. They do show how a long restructuring can ultimately transition into receivership when a transaction remains conditional and does not close.

Partially completed GTA real estate developer residential development presented in a calm, neutral editorial style

Real estate developer: What is happening at Hedge Road Landing in Georgina?

Hedge Road Landing is a semi-complete residential subdivision on Lake Simcoe in Georgina, Ontario. Its circumstances are different.

On August 24, 2026, the real estate developer companies obtained CCAA protection on application of the senior secured lender. The project faced unpaid loans totalling approximately $42.9 million as of August 13, 2026, together with construction delays and liquidity issues.

The proceeding is creditor-led. That means the senior lender, rather than the project companies alone, initiated the court-supervised restructuring process.

The court-ordered stay of proceedings remains in place until November 13, 2026. The defined period is intended to allow restructuring work and the completion of remaining units to be pursued in an orderly manner without any enforcement action or litigation either begun or continued against this real estate developer and the project.

This is a live, ongoing proceeding. It should not be described as either a failure or a success. Whether the project achieves its restructuring objectives will depend on what happens during that period, including financing, construction progress, sales and stakeholder cooperation.

The contrast with the 1111 Clarkson Road real estate developer project is therefore not that one process has already succeeded. The contrast is that Hedge Road Landing has a defined restructuring window during which a plan can be pursued, while 1111 Clarkson ultimately reached receivership after the proposed transaction failed to close.

Real estate developer: Why do long restructuring processes sometimes end in receivership?

A real estate developer restructuring seeks to preserve or enhance enterprise value. Receivership generally focuses on taking control of assets and realizing on them for creditors.

A long process may end in receivership when:

  1. The proposed financing never becomes firm;
  2. A sale process produces no qualified or executable transaction;
  3. Interim funding is exhausted or unavailable;
  4. Construction or operating losses continue;
  5. Priority disputes prevent closing; or
  6. The project’s value changes faster than the restructuring plan.

The CCAA itself is not the problem. It can provide breathing room, protect a business from enforcement, facilitate a sale and create a platform for compromise. Many CCAA proceedings produce successful reorganizations or transactions.

The issue is whether the restructuring continues to create more value than it consumes. A plan that is credible, funded and capable of closing justifies spending the time. A plan dependent on uncertain financing, repeated extensions or unresolved priority issues requires constant reassessment.

How do CCAA, a BIA proposal and receivership differ?

The following is general information only. The correct process depends on the company’s facts, assets, liabilities, financing and objectives.

ProcessWhat it isWho typically initiates itDebtor’s role and controlTypical purposeWhat it may mean going forward
CCAA restructuringA court-supervised restructuring under the Companies’ Creditors Arrangement Act, generally used for larger or more complex insolvencies.Usually the debtor, although a qualifying secured creditor may also apply.The debtor often remains in possession, subject to court orders, monitor oversight and financing conditions.Compromise debts, obtain financing, sell or recapitalize the business, and continue operations where viable.The business may continue, be sold, recapitalized or eventually move into receivership or bankruptcy if the plan fails.
BIA Division I ProposalA formal proposal to creditors under the Bankruptcy and Insolvency Act, often used by small and mid-sized businesses.Usually the debtor, with the process administered through a Licensed Insolvency Trustee.Management generally continues operating the business, subject to proposal requirements and creditor protections.Offer creditors a structured compromise or payment plan while avoiding bankruptcy.If creditors accept and the proposal is completed, the business may continue; if it is refused or fails, bankruptcy may follow.
ReceivershipA process in which a receiver takes control of and realizes on some or all of the debtor’s assets.Often a secured lender, either privately or by court application; other stakeholders may also seek relief.Control generally shifts away from the debtor to the receiver, subject to the receivership order.Preserve, market, sell or otherwise realize on assets and distribute proceeds according to priorities.The business may be sold or completed under new ownership, but the debtor’s control is substantially reduced.

Scroll the table sideways to see every column. General information only. The appropriate process depends on the company’s facts, assets, liabilities, financing and objectives.

A proposal or CCAA process is not automatically better than receivership. The right question is which process best preserves value and provides a realistic path forward.

Professionals reviewing a real estate developer construction schedule and cash-flow documents in a neutral meeting room

Why do construction liens make a distressed project more complicated?

Valid construction liens affect both the amount of debt and the priority of claims against the land. A real estate developer may believe that its mortgage or investment structure provides sufficient security, while lien claims create competing legal and financial issues.

Construction-lien disputes can affect:

  • The priority of a mortgage or other security;
  • The amount required to complete the project;
  • The ability to sell the property free and clear;
  • The availability and cost of DIP financing;
  • The willingness of trades to return to the site; and
  • The distribution of sale proceeds.

Trades and suppliers should protect their position early. That may include documenting contracts, preserving lien rights, registering liens within applicable deadlines, confirming holdback issues and obtaining professional advice before signing a release or accepting a payment arrangement.

A real estate developer should not wait until liens have accumulated to understand their effect. A project’s capital stack, lien exposure and completion budget should be reviewed together. The 1111 Clarkson Road facts show how priority challenges can alter an entire transaction.

When should a GTA real estate developer pick up the phone?

I recommend seeking advice promptly when any of these signs appear:

  • A missed payment to a lender;
  • A default under a loan, mortgage or forbearance agreement;
  • A formal demand or enforcement threat;
  • Growing construction liens or unpaid holdbacks;
  • CRA arrears or unremitted source deductions;
  • A stalled construction project;
  • A key investor, purchaser or joint-venture partner walking away;
  • Inability to fund the next construction phase;
  • A requirement for additional DIP or bridge financing; or
  • A cash-flow forecast that depends on an uncertain closing.

The first step is not necessarily filing for CCAA protection, making a BIA Division I Proposal or accepting receivership. The first step is understanding the facts: cash on hand, committed financing, completion costs, asset value, creditor priorities, tax obligations and realistic transaction prospects.

That analysis can reveal a consensual workout, refinancing, asset sale, proposal or restructuring path while those options are still available.

Frequently Asked Questions (FAQ)

Is a CCAA a failure if the proceeding ends in receivership?

No. A CCAA proceeding is a tool, not a guarantee. It may provide a necessary opportunity to seek financing, sell a business or compromise debt. If the intended transaction does not close and receivership follows, the court process may still have clarified the asset, claims and available alternatives. The key question is whether the process remained value-enhancing and realistic.

Does a receiver mean the business is over?

Not always. A receiver may sell the business as a going concern, complete a project, refinance assets or conduct an orderly sale. However, the debtor usually loses control over the assets covered by the receivership order. The outcome depends on the receiver’s mandate, available funding, asset value and stakeholder priorities.

What should unpaid trades and suppliers do?

They should preserve records, review their contracts and invoices, monitor lien deadlines and obtain advice promptly. They should also determine whether they have lien, trust, construction-charge or other rights. A trade should not assume that waiting for a restructuring will protect its position.

Can a restructuring be started too late?

Yes. A restructuring may become impractical if funding has run out, assets have deteriorated, key personnel have left, liens have multiplied or no credible transaction remains. Starting earlier does not guarantee success, but it generally preserves more options.

Is a creditor-led CCAA process unusual?

It is less familiar to some business owners, but a qualifying secured creditor may initiate a CCAA application. Hedge Road Landing illustrates how a senior secured lender can seek court protection to create an orderly period for restructuring and project completion.

Should every GTA real estate developer use the CCAA?

No. The CCAA is often appropriate for larger or complex files, but a BIA Division I Proposal, negotiated workout, refinancing, sale or receivership may be more suitable in another situation. Professional advice is essential because the wrong process can consume time and money without solving the underlying problem.

What is the main lesson from these two projects?

The lesson is not that CCAA proceedings are bad or that every distressed project should move immediately into receivership. The lesson is that time must serve a defined purpose. Acting early may preserve financing, purchasers, trades, project value and transaction flexibility.

Source note

The case discussion is based on reporting by Insolvency Insider Canada dated September 13, 2026 and August 30, 2026, Storeys dated September 18, 2026, and Office of the Superintendent of Bankruptcy CCAA records and related materials. The Hedge Road Landing CCAA proceeding is ongoing as of the date of publication.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future, call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

————————––

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

IRA SMITH is President of Ira Smith Trustee & Receiver Inc., a CPA CA and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes corporate restructuring, receivership, corporate bankruptcy administration and consumer insolvency. Ira provides practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, individuals and professionals. He remains current with developments in Canadian insolvency law and applies that knowledge to help clients make informed decisions, reduce stress and regain control of their financial future.Calm professional advisers reviewing real estate developer plans for a GTA residential development under construction

#RealEstateDeveloper #GTAInsolvency #CorporateRestructuring #CCAA #Receivership #ConstructionLiens #RealEstateDevelopment #ConstructionFinance #OntarioBusiness #FinancialRestructuring #StartingOverStartingNow

Categories
Brandon Blog Post

Toronto Business Closures Are Surging: Why BMO’s Per-Capita Insolvency Argument Misses the Bigger Picture

Two professionals reviewing a cash flow forecast and strategic restructuring plan for a Toronto business

I hope you, your family, and your Toronto business are safe and managing as well as possible in a difficult economic environment. If you are a GTA business owner watching sales weaken, costs rise, or creditors become more persistent, you are not alone, and asking for help early is not a sign of failure. It is a practical step towards regaining control.

The latest Toronto business and Canadian insolvency data tell a complicated story. New businesses continue to open, but an unusually large number are also closing. At the same time, formal insolvency filings are rising, while many households and businesses may be managing distress outside the formal insolvency system.

Toronto Business: Key Takeaways

  • The Toronto Census Metropolitan Area (CMA) recorded approximately 10,870 Toronto business openings in April 2026, the highest April level in at least 11 years.
  • Toronto also recorded approximately 10,720 Toronto business closures, the second-highest April total on record, behind only April 2020.
  • Active businesses fell to 187,700 in April 2026, marking a seventh consecutive monthly decline and the lowest level since June 2022.
  • Canada recorded 13,254 insolvency filings in June 2026, up 11.5% year over year and more than double the June 2020 volume.
  • BMO Capital Markets’ per-capita analysis provides one useful perspective. Still, it does not capture who has access to credit, who is filing, or how many businesses and households are struggling without filing.
  • For Toronto business owners, early advice from an accountant and a Licensed Insolvency Trustee can preserve more restructuring options.

Toronto Business: Highlights

Toronto Business: What is Toronto business data telling us?

The Toronto CMA is experiencing both entrepreneurial activity and business contraction at the same time.

According to Better Dwelling’s August 5, 2026 report, approximately 10,870 businesses opened in April 2026. That was the most openings recorded for an April in at least 11 years.

That might sound encouraging. It is.

However, approximately 10,720 businesses also closed during the month. This was the second-highest April closure total on record, surpassed only by April 2020, when pandemic lockdowns disrupted the economy.

The result is a high-churn environment. Toronto business churn means businesses are opening and closing at an unusually rapid rate. Churn can reflect innovation and opportunity, but it can also indicate that owners are entering markets without enough financial cushion to withstand weaker demand, higher operating costs, tighter credit, or delayed customer payments.

The number of active businesses in the Toronto CMA fell to 187,700 in April 2026. This was the seventh consecutive monthly decline. The active Toronto business count was down approximately 0.9% year over year and at its lowest level since June 2022, nearly a four-year low.

This is the real-world business story behind the headline. Toronto is not simply seeing fewer businesses. It is seeing significant movement in both directions, while the total base of active businesses continues to shrink.

Business professionals reviewing positive and negative cash flow Toronto business projections during a restructuring discussion

Toronto Business: Why is BMO’s per-capita argument incomplete?

BMO Capital Markets senior economist Robert Kavcic has offered a perspective that deserves to be understood fairly.

As reported by Better Dwelling on August 13, 2026, Mr. Kavcic acknowledged that consumer insolvencies were near the highest level since the 2009 recession. His argument was that, after adjusting for Canada’s population growth, insolvencies had “basically just normalized back to pre-pandemic conditions.”

He concluded that “the real story is that there is really no story.”

A per-capita measure, a calculation that divides a total by the size of the population, can be useful. It can help compare conditions across different time periods when the population has changed. BMO is right that raw totals do not tell the entire story.

The difficulty is that population growth does not necessarily equal comparable growth in credit exposure.

Better Dwelling reported that approximately 40% of Canada’s population growth over the past five years came from non-permanent residents, including temporary workers and international students. These groups typically have more limited access to unsecured credit, the type of credit that does not require collateral.

That matters because consumer insolvency filers often have an established borrowing history. According to the Office of the Superintendent of Bankruptcy data cited by Better Dwelling, 57% of consumer insolvency filers in 2024 had a bank loan, with a median value of approximately $20,000. In addition, one in five filers had filed before.

This profile does not necessarily match the typical non-permanent resident. Therefore, using total population as the denominator may dilute the apparent rate of insolvency without accurately measuring the financial stress among established borrowers.

The broader lesson is not that per-capita statistics are useless. The lesson is that they must be qualified. A business owner, lender, policymaker, or household needs to know not only how many people live in Canada, but also who is borrowing, who is falling behind, and who is taking formal action.

The June 2026 figures remain significant. Canada recorded 13,254 insolvency filings, an 11.5% increase from June 2025 and more than double the June 2020 volume. Only June 2009 recorded more filings. The trailing 12-month total reached approximately 150,505 filings, up 5.3% year over year.

Those numbers do not prove that every household or Toronto business is in crisis. They do show that financial distress is material and deserves more than a single reassuring ratio.

Toronto Business: What kinds of financial distress are being missed?

Raw insolvency counts and per-capita ratios can both understate the pressure facing the economy because they capture only part of the problem.

There are at least three different forms of financial distress:

Form of distressWhat it isHow it appears in the dataWhy it matters to a business owner
Formal insolvency filingA bankruptcy or proposal filed under Canada’s insolvency legislation. A proposal is a formal arrangement intended to compromise or restructure debts.It appears in official insolvency statistics reported by the OSB.It may provide legal protection and a structured path forward, but waiting too long can reduce available options.
Silent business closureA business stops operating, winds down, or does not renew operations without making a formal insolvency filing.It appears in business-opening and business-closure data, but not necessarily in insolvency statistics.Suppliers, employees, landlords, and customers may still be affected. The owner may also remain personally exposed through guarantees or other obligations.
Household debt stressA household manages financial pressure through arrears, refinancing, payment deferrals, or high-interest credit without filing an insolvency proceeding.It may appear indirectly in arrears or credit data and may not appear in formal insolvency counts for months or years.Household stress can reduce consumer spending, delay business payments, and weaken the customer base on which a business depends.

Insolvency is also a lagging indicator. That means a formal filing often occurs after months or years of financial deterioration. Before filing, a business may have used savings, borrowed from family, increased credit-card balances, refinanced assets, delayed tax remittances, or negotiated informal payment arrangements.

By the time the filing appears in the statistics, the underlying financial pressure may already be much more severe.

This is why a Toronto business owner should not wait for a formal insolvency number, or a missed payment, to decide whether advice is necessary. Early advice is about information, not commitment.

Toronto Business: What does this mean for GTA business owners?

For a GTA business owner, the important question is not whether the economy is technically “normal” on a per-capita basis. The important questions are more immediate:

  • Are sales sufficient to cover operating costs?
  • Are customers paying more slowly?
  • Are supplier terms becoming stricter?
  • Are tax arrears accumulating?
  • Are loan renewals or refinancing becoming more difficult?
  • Have you used personal credit to support the company?
  • Have you signed personal guarantees for corporate borrowing or leases?
  • Is the Toronto business profitable before debt payments, but unable to meet its total obligations?

A company can be viable, meaning it has a fundamentally workable business model, while still being financially unsound because of accumulated debt, temporary cash-flow disruption, or an unsustainable repayment schedule.

That distinction is important. A viable company may have restructuring options that disappear if the owner waits until assets are seized, key employees leave, or critical suppliers stop extending credit.

A corporate restructuring plan may involve negotiating with creditors, changing payment terms, selling non-core assets, reducing expenses, or using a formal proposal. A commercial proposal, sometimes called a Division I Proposal, is a legal process that can allow a financially troubled but viable company to compromise debts and continue operating, subject to the required approvals.

The right solution depends on the company’s structure, assets, liabilities, cash flow, tax position, employees, secured lenders, and personal guarantees. There is no universal answer.

Businessperson protected by a shield representing a Toronto business director protection and early insolvency advice

Toronto Business: What should a worried business owner do now?

If you are concerned about your GTA or City of Toronto business, I recommend taking these steps:

  1. Prepare a current cash-flow forecast.
    List expected sales receipts, payroll, rent, taxes, loan payments, supplier obligations, and other essential expenses. A cash-flow forecast is a practical estimate of money coming in and going out over a defined period.
  2. Speak with your accountant early.
    Your accountant can help identify profitability problems, tax obligations, cash-flow gaps, and whether the business can realistically recover under its current structure.
  3. Consult a Licensed Insolvency Trustee.
    A Licensed Insolvency Trustee can explain formal options, including a proposal or bankruptcy, and help distinguish between corporate obligations and your personal exposure.
  4. Review personal guarantees and director liability.
    If you personally guaranteed a corporate loan, lease, credit facility, or supplier account, the corporation’s financial problems may affect you directly. Certain tax and payroll obligations can also create potential director exposure. Obtain professional advice before transferring assets, repaying selected creditors, or closing the company.
  5. Assess whether the core business is viable.
    Ask whether the company can generate positive operating cash flow after a realistic restructuring of its debt and costs. If the answer is yes, a restructuring proposal may be a lifeline. If not, an orderly wind-down may be more appropriate.
  6. Act before the crisis becomes irreversible.
    Early action does not mean you have decided to file. It means you are preserving information, time, credibility, and options.

We know the tension placed upon Toronto business owners and their families. It is not your hope, commitment, or personal worth that these statistics measure. Financial distress is a business problem that requires a business solution.

For additional context, our discussion of commercial proposals and corporate restructuring explains how a formal proposal may help a viable company continue operations. Our article on personal bankruptcy also discusses why a corporation and its owner must be assessed separately.

Toronto Business: Frequently Asked Questions (FAQ)

Are Toronto’s business closures the same as business insolvencies?

No. A business closure means an operation has stopped or ceased to be active. It does not necessarily mean the business filed a bankruptcy or proposal. Some businesses close quietly, while others may restructure informally or continue under a different ownership or operating model.

Does BMO’s per-capita analysis have value?

Yes. Per-capita analysis can help account for population changes. The concern is relying on it alone. It may not reflect differences in credit access, borrowing behaviour, business exposure, or the number of people experiencing stress without filing.

Why are insolvency filings considered a lagging indicator?

A formal insolvency filing often follows a long period of missed payments, borrowing, refinancing, arrears, or attempts to negotiate with creditors. The filing is usually evidence that earlier coping strategies have stopped working.

Should I wait until my business misses a payment before seeking advice?

No. Early advice is generally more useful because it allows you to understand your options before creditors take enforcement action, suppliers withdraw terms, or essential assets become unavailable. A consultation does not obligate you to file.

Can a business owner be personally responsible for corporate debt?

Possibly. Personal guarantees, the legal structure of the business, and certain tax or payroll obligations can create personal exposure. This is fact-specific, so speak with your accountant and a Licensed Insolvency Trustee before making major financial decisions.

Is a proposal the same as bankruptcy?

No. A proposal is a formal arrangement to compromise or restructure debts, while bankruptcy is a separate legal process. Whether a proposal is appropriate depends on the company’s viability, assets, liabilities, cash flow, and creditor situation.

The message for Toronto and the GTA is balanced but clear: new businesses are still being created, but active businesses are declining, closures are elevated, and formal insolvency filings are rising. That is a story worth paying attention to, not to create panic, but to encourage timely, informed action.

Source note: Statistics and quotations in this article are based on the two Better Dwelling reports published on August 5, 2026, and August 13, 2026. The underlying Statistics Canada and Office of the Superintendent of Bankruptcy data are attributed as reported by Better Dwelling. BMO’s position is attributed to BMO Capital Markets senior economist Robert Kavcic.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future; call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Ira Smith is President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Ira stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.Image of a worried business owner as Toronto business closures are increasing in 2026

#TorontoBusiness #GTABusiness #BusinessClosures #CorporateRestructuring #BusinessInsolvency #DebtRestructuring #CommercialProposal #DivisionIProposal #BusinessBankruptcy #FinancialDistress #LicensedInsolvencyTrustee #StartingOverStartingNow
Categories
Brandon Blog Post

Can a Secured Lender Credit-Bid to Buy a Lawsuit Against Itself? Ontario Court of Appeal to Decide

A high-resolution photographic rendering of a gavel resting on top of a stack of legal documents and Canadian currency with a professional corporate feel, representing the lawsuit a bankrupt company has against its secured lender.

If you are reading this while navigating a complex financial restructuring or managing the pressures placed on your company by your secured lender and are fearful of corporate insolvency, please know that you are not alone. At Ira Smith Trustee & Receiver Inc., we understand that legal jargon and courtroom battles can feel overwhelming when you are simply trying to find a path forward. We are here to guide you through these technical waters with clarity and compassion.

Secured Lender Key Takeaways

  • A Landmark Question: The Ontario Court of Appeal is set to decide if a secured lender can use their debt to “buy” a lawsuit that a Licensed Insolvency Trustee could file against it.
  • Credit Bidding vs. Cash: Traditionally, credit bidding allows a secured lender to bid the value of their debt. The case discussed below begins to question if that applies to assets that aren’t part of their original security.
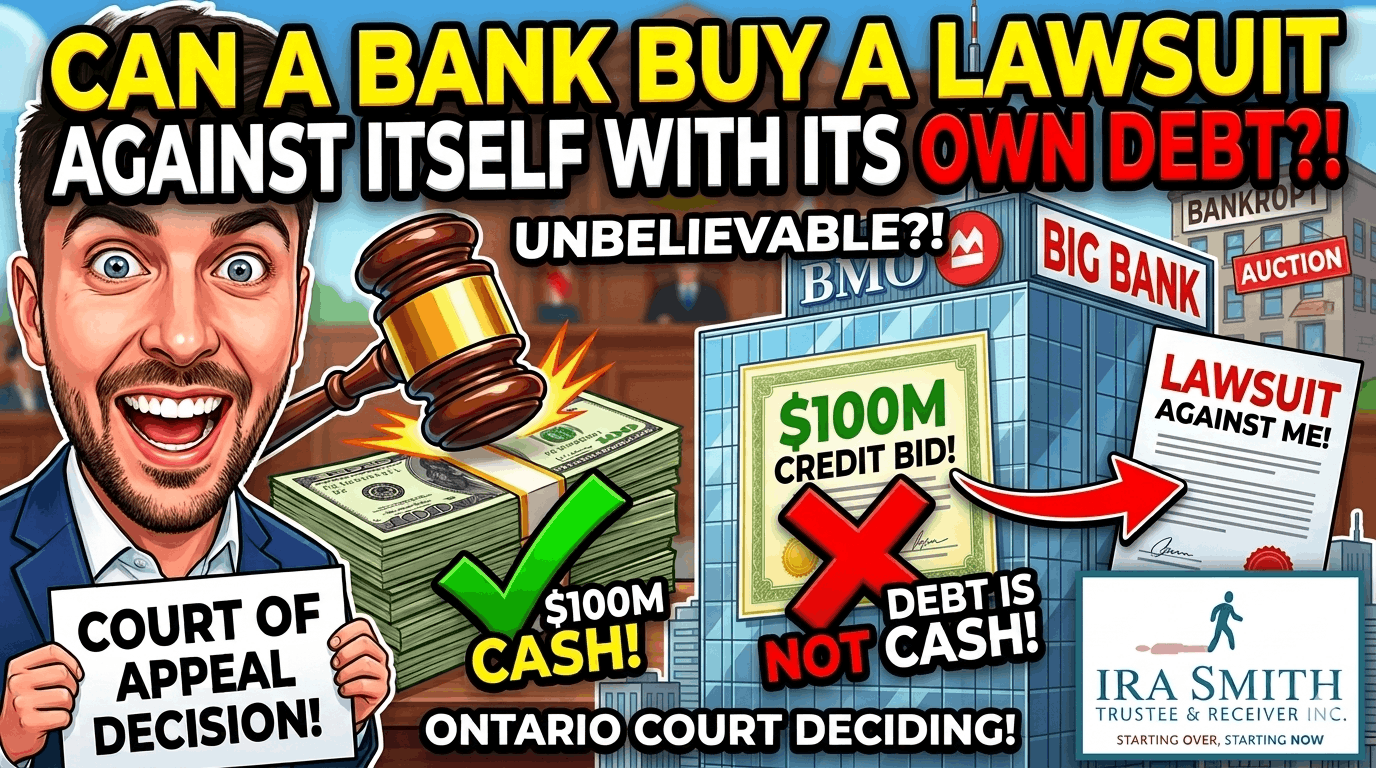
  • The Avida Case: A judge on the Ontario Commercial List recently allowed Bank of Montreal (BMO) to participate in an auction to be run by the Trustee and credit-bid to purchase a cause of action (a legal claim) against BMO, but that decision is now being appealed.
  • Why It Matters: The final ruling will impact how receivers and trustees recover money for creditors and whether lenders can effectively “neutralize” legal claims without paying cash.

Secured Lender Highlights

  • What is a Credit Bid?
  • The Case of Avida 2015 Inc. (Re)
  • The Conflict: Can a Lender Bid Debt for a Lawsuit?
  • Why the Court of Appeal is Stepping In
  • Comparison: Credit Bidding vs. Cash Bidding
  • What This Means for You and Your Business
  • Frequently Asked Questions (FAQ)

Secured Lender: What is a Credit Bid?

Before we dive into the details of the Avida 2015 Inc. (Re), 2026 ONCA 478 (CanLII) case, let’s define a term that is central to this debate. In the world of insolvency, a credit bid occurs when a secured creditor, someone who has a legal claim over specific assets, uses the money they are already owed as “currency” to buy those assets in a receiver’s or trustee’s Sale and Investment Solicitation Process (SISP).

Normally, if a business goes bankrupt, the Licensed Insolvency Trustee (the person appointed to manage the bankruptcy) tries to sell the business assets for cash. However, a secured lender often has the right to say, “Instead of you selling my collateral to someone else for cash, I will bid on all or part of the debt I am owed to take ownership of it myself.”

Assets of this type are often physical, like equipment or real estate. But what happens when the asset is a cause of action, essentially, the right to sue someone? And what happens when that someone to be sued is the secured lender itself?

Two professionals in a Toronto office reviewing a 'Cash Flow Forecast' chart, including the payments that need to be made to the secured lender, focused on 'Strategic Restructuring.'


Secured Lender: The Case of Avida 2015 Inc. (Re)

The story of Avida 2015 Inc. brings this technical question into sharp focus. In this bankruptcy proceeding, the Trustee identified a valuable asset: a cause of action against the Bank of Montreal (BMO). In simpler terms, the Trustee believed the estate had a legal claim to sue BMO for money.

The Trustee decided to put this lawsuit up for auction. BMO, being a secured lender and a major creditor in the bankruptcy, wanted to participate in the auction. They didn’t want to bid cash, though; they wanted to use a credit bid based on the secured debt they were already owed by Avida.

On September 22, 2025, a bankruptcy judge made a significant ruling: BMO was permitted to bid in the auction using a credit bid up to the face value of its secured debt.

This caused immediate concern for other stakeholders. If BMO could buy the lawsuit against itself using its own debt, it could effectively end the litigation without ever having to write a cheque. The appellant in this case, David Reale, argued that BMO should be required to pay cold, hard cash like any other bidder.


The Conflict: Can a Secured Lender Bid Debt for a Lawsuit?

The core of the dispute is whether a credit bid can be used to acquire an asset that does not actually fall under the lender’s security agreement.

Think of it this way: if a bank has a mortgage on a building, it makes sense that they can credit-bid for that building. But does that bank also have the right to credit-bid for a legal claim that isn’t part of that mortgage?

The appellant argues that allowing a secured lender to do this “chills” the auction. Who would want to bid cash against a bank that can bid millions of dollars in “debt” that it already holds? This could prevent the Trustee from getting the best possible value for the estate’s creditors.


Secured Lender: Why the Court of Appeal is Stepping In

This isn’t just a minor disagreement over a single auction. On June 17, 2026, a judge of the Court of Appeal for Ontario granted leave to appeal the original judge’s decision. They noted that this is “a matter of importance… to bankruptcy proceedings more generally.”

As of June 29, 2026, Justice Zarnett issued a case management ruling (2026 ONCA 478) to set the stage for the full hearing. We now have a timeline for when these big questions will be answered:

  • July 15, 2026: Deadline for the appellant to perfect the appeal.
  • July 31, 2026: BMO’s opportunity to file its response.
  • August 19, 2026: Deadline for other interested parties to intervene.

This case will likely set a major precedent for how a secured lender interacts with receivership and bankruptcy estates in Ontario for years to come. We will keep an eye on this case and update you in a future Brandon’s Blog.

A professional digital composite image of a legal folder labeled 'CAUSE OF ACTION' against a secured lender with a 'FOR SALE' tag attached.


Secured Lender Comparison: Credit Bidding vs. Cash Bidding

To help you understand why this battle is so fierce, we have put together a comparison of the two bidding methods:

FeatureCredit BiddingCash Bidding
Payment MethodOffsetting the secured debt owed by the estate.Liquid cash payment into the estate.
Liquidity for EstateLow (does not provide cash for other creditors).High (provides immediate cash to the trustee).
Primary AdvantageProtects the lender’s security value.Maximizes cash recovery for unsecured creditors.
Legal StatusCommon practice, but subject to court discretion.Standard procedure for all bankruptcy auctions.
ControversyDisputed when used to buy a lawsuit against the bidder.Generally undisputed if the price is fair.


Secured Lender: What This Means for You and Your Business

Whether you are a business owner facing a corporate restructuring or a creditor trying to recover what you are owed, the Avida decision matters.

If the Court of Appeal rules that credit bidding is restricted to only the assets specifically listed in a security agreement, it gives Trustees more power to raise cash by selling the unsecured assets. This could lead to higher payouts for unsecured creditors.

On the other hand, if the court supports BMO’s position, a secured lender will have a powerful tool to protect itself from litigation costs during an insolvency administration, such as a receivership or bankruptcy proceeding. It essentially allows them to use all or a portion of the “value” of their unpaid debt to “buy” their way out of a lawsuit.

We know the tension put upon you when these legal battles occur. Our goal is to ensure you have the information you need to make practical decisions during a financial crisis.

A confident woman breaks free from heavy chains, symbolizing escape from financial burdens and her secured lender


Secured Lender Frequently Asked Questions (FAQ)

1. Can any creditor use a credit bid?
Typically, only secured creditors can credit-bid. Unsecured creditors (those without a specific lien or charge on an asset) have to pay cash if they want to buy something from a receivership or bankruptcy estate. They have no credit to bid!

2. Why would a Trustee sell a lawsuit?
Lawsuits are expensive and time-consuming. If a Trustee doesn’t have the funds to pay lawyers to fight a case, they might sell the cause of action to a third party who is willing to take the risk and pay cash upfront for the right to pursue it.

3. Is this decision final?
No. As of late June 2026, the Ontario Court of Appeal has only set the schedule for the case. We will likely not have a final decision until late 2026 or early 2027.

4. What does “perfecting an appeal” mean?
Perfecting an appeal is the technical process of filing all the necessary documents, transcripts, and legal arguments with the court so that the appeal is ready to be heard by the judges.


Secured Lender: The Path Forward

Navigating the world of bankruptcy and corporate insolvency is rarely straightforward. Cases like Avida 2015 Inc. remind us that the law is constantly evolving to find a balance between the rights of lenders and the need for a fair process for everyone.

At Ira Smith Trustee & Receiver Inc., we don’t just see numbers and legal files; we see people and businesses looking for a fresh start. We are committed to staying at the forefront of these legal developments so we can provide you with the best possible advice.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future, call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Brandon stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.


An image of the secured lender bank tower, an image of its borrower's bankruptcy and a lawsuit the borrower has against the bank to describe this Court of Appeal for Ontario case this Brandon's Blog is about.

#SecuredLenders #CreditBid #InsolvencyLaw #OntarioCourtOfAppeal #CorporateRestructuring #BankruptcyOntario #FreshStart

Categories
Brandon Blog Post

BIA vs CCAA Proceedings Toronto: Which Restructuring Strategy Saves Your Business?

BIA vs CCAA proceedings Toronto: A comprehensive guide to business restructuring and corporate debt relief.

BIA vs CCAA Introduction

Good morning. If you are reading this, you are likely navigating one of the most challenging periods in your professional life. We want to start by acknowledging the immense pressure you are under. Running a business in the Greater Toronto Area (GTA) is demanding enough without the added weight of financial distress, creditor calls, and the fear of losing everything you have built. Please know that you are not alone, and your safety and well-being are paramount. Financial crisis is a hurdle, not the end of your story. We are here to help you find the path back to stability.

In this Brandon’s Blog, I talk about how using either the Bankruptcy and Insolvency Act (BIA) or the Companies’ Creditors Arrangement Act (CCAA), can be navigated to restructure and save your business.

BIA vs CCAA Key Takeaways

  • BIA Division 1 Proposals are typically faster and more cost-effective for small to medium-sized enterprises (SMEs) with less complex debt.
  • CCAA Proceedings are reserved for larger corporations with debts exceeding $5 million, offering greater judicial flexibility.
  • A “Stay of Proceedings” is a legal shield that immediately stops creditors from taking legal action or seizing assets while you restructure.
  • Failing a BIA Proposal leads to automatic bankruptcy, whereas a CCAA failure allows for more structured exits or liquidations.
  • Choosing the right strategy depends on your debt load, the complexity of your operations, and your ultimate goal for the business.

Highlights

  1. The Lifeline of Business Restructuring
  2. What is a BIA Division 1 Proposal?
  3. The CCAA: For Complex Corporate Challenges
  4. Direct Comparison: BIA vs. CCAA
  5. Which Strategy is Right for Your Toronto Business?
  6. Frequently Asked Questions (FAQ)
  7. Conclusion: Starting Over, Starting Now

The Lifeline of Business Restructuring

When a business can no longer meet its financial obligations, it enters a state of insolvency. This is a technical term meaning the company’s liabilities exceed its assets or it cannot pay its bills as they come due. In Canada, we have two primary “lifelines” to help businesses avoid total liquidation: the Bankruptcy and Insolvency Act (BIA) and the Companies’ Creditors Arrangement Act (CCAA).

Both pathways are designed to give a “fresh start” to a viable business by allowing it to restructure its debts and continue operating. However, the choice between them is critical. Making the wrong move can lead to the very outcome you are trying to avoid: the permanent closure of your company. Whether you are managing a manufacturing plant in Vaughan or a tech startup in downtown Toronto, understanding these frameworks is the first step toward regaining control.

Corporate debt restructuring in Toronto thourhg BIA Division 1 Proposals or CCAA proceedings for Ontario businesses: Breaking chains representing breaking free from financial insolvency and creditor pressure.


What is a BIA Division 1 Proposal?

The BIA Division 1 Proposal is the most common tool used by small and medium-sized businesses in Ontario to manage insolvency. It is a formal, legally binding agreement between a debtor and their creditors to pay back a portion of the debt over time or to restructure the business operations.

How the Process Works

The process usually begins with filing a Notice of Intention (NOI). This filing triggers an immediate Stay of Proceedings, which acts as a legal “stop button” for all lawsuits, wage garnishments, and asset seizures. This gives the company an initial 30 days, extendable up to six months with court approval, to develop a restructuring plan.

A Licensed Insolvency Trustee (LIT) acts as the Proposal Trustee, overseeing the process and ensuring fairness for both the debtor and the creditors. Once the proposal is drafted, it is presented to the creditors for a vote. To pass, the proposal requires a “double majority”:

  1. A majority in number of creditors who vote.
  2. Two-thirds (66.7%) of the total dollar value of the claims.

Why Choose the BIA?

  • Predictability: The rules are clearly defined in the Act, leaving less room for legal ambiguity.
  • Cost-Efficiency: It involves fewer court appearances than a CCAA proceeding, making it significantly more affordable for smaller companies.
  • Speed: The deadlines are strict, forcing a resolution relatively quickly.

However, there is a catch. If the creditors reject the proposal, or if the court refuses to approve it, the company is automatically assigned into bankruptcy. This “all or nothing” nature makes the quality of the initial proposal and the advice of your business debt restructuring expert vital.


The CCAA: For Complex Corporate Challenges

While the BIA is a set of rigid rules, the Companies’ Creditors Arrangement Act (CCAA) is more like a blank canvas. It is federal legislation designed specifically for large corporations that need a more customized approach to restructuring.

The $5 Million CCAA Threshold

To qualify for CCAA, a company (or a group of affiliated companies) must have total debts exceeding $5 million. If your debt is below this mark, the BIA is your only option.

The Power of the Court

The defining feature of CCAA is judicial discretion. Unlike the BIA, where the process is largely administrative, CCAA is entirely court-driven. This allows a judge in the Ontario Superior Court of Justice to “craft” orders that fit the unique needs of a complex business. This might include:

  • Dealing with multiple classes of creditors separately.
  • Approving a stalking horse bidder process to sell assets while under protection.
  • Granting a broader “Stay of Proceedings” that can extend to third parties or directors.

Why Choose CCAA?

CCAA is ideal when a company has a complicated capital structure, international operations, or multiple layers of secured debt. It offers more flexibility and, crucially, does not result in automatic bankruptcy if the plan is rejected. Instead, the company simply loses its legal protection, and creditors are free to pursue their remedies.

Professional restructuring consultation on BIA Division 1 Proposals and CCAA proceedings for Ontario businessesin in the GTA with Ira Smith Trustee & Receiver Inc., a Vaughan Licensed Insolvency Trustee.


Direct Comparison: BIA vs. CCAA

To help you decide which path fits your situation, here is a direct comparison of the two restructuring frameworks:

We know the tension put upon you when making these decisions. Choosing between these two paths isn’t just a legal formality; it’s a strategic decision that affects your employees, your reputation, and your future.


BIA vs CCAA: Which Strategy is Right for Your Toronto Business?

Determining the right strategy requires a deep dive into your company’s financial health and operational goals. For a local GTA business owner, perhaps a restaurant group with a few locations or a mid-sized construction firm, the BIA Division 1 Proposal is often the “lifeline” of choice. It provides the necessary protection without the prohibitive costs of a court-heavy CCAA process.

However, if you are managing a large enterprise with diverse assets and massive liabilities, the CCAA offers the “surgical precision” needed to restructure without the looming threat of automatic bankruptcy.

At Ira Smith Trustee & Receiver Inc., we specialize in identifying the most efficient route for your specific needs. We focus on the “why” behind the numbers, saving jobs, protecting your legacy, and giving you the peace of mind to sleep through the night again.

Visual comparison of documents for BIA Division 1 Proposals and CCAA proceedings for Ontario businesses.


Frequently Asked Questions (FAQ)

Q: Can a small business use CCAA if they have less than $5 million in debt?
No. The $5 million threshold is a strict statutory requirement. For debts under this amount, the BIA Division 1 Proposal is the designated restructuring tool.

Q: Will my creditors find out about the restructuring?
Yes. Both BIA and CCAA are public processes. All known creditors must be notified so they can participate in the voting or court proceedings.

Q: Can I keep running my business during a BIA or CCAA process?
Absolutely. The entire point of these “debtor-in-possession” (DIP) proceedings is to allow management to continue running the day-to-day operations while the debt is restructured.

Q: What is a “Stay of Proceedings”?
Think of it as a legal shield. It is an order that prevents creditors from starting or continuing any legal actions, seizures, or collection efforts against you while you are under restructuring protection.


BIA vs CCAA Conclusion

Navigating the choice between BIA and CCAA proceedings in Toronto can feel like walking through a minefield. But you don’t have to do it alone. Whether your business needs the structured simplicity of a BIA Proposal or the sophisticated flexibility of a CCAA filing, the goal is the same: Starting Over, Starting Now.

By taking action today, you are choosing to lead your company through the storm rather than letting the storm dictate your future.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future. Call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Brandon stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.

Categories
Brandon Blog Post

THE ULTIMATE GUIDE TO SURVIVING TERRIBLE TARIFFS ANXIETY: PROTECTING VAUGHAN, ONTARIO MANUFACTURERS FROM U.S. BORDER COSTS

Undeniably, large tariffs don’t just cut into your profit margins—it wipes them out overnight. However, panic is an inadequate response when your auto parts manufacturing business in Vaughan, Ontario, faces an immediate cash flow crisis. Consequently, this guide delivers actionable strategies to leverage corporate debt restructuring and protect your company from impending U.S. trade tensions.

Key Takeaways:

  • Margin wipeout: Tariffs directly hit cash flow, making debt repayment impossible for many suppliers.
  • Action over panic: Mitigating the impact of tariffs requires immediate financial restructuring, not just operational shifts.
  • Legal protection: Tools like a Division I Proposal stop creditor collections while you fix your supply chain.
  • Expert help: Ira Smith Trustee & Receiver Inc. can guide your Ontario manufacturing business back to profitability, whether it is located in Woodbridge, Ontario, or anywhere else in the Greater Toronto Area.

What is Tariffs-Induced Anxiety?

Tariffs-induced anxiety is the severe financial stress experienced by business owners facing sudden, crippling border taxes on their exported goods. Indeed, this fear is completely justified for companies operating within Ontario’s deeply integrated automotive network. Often, executives lose sleep wondering how they will meet payroll when cross-border shipping costs unexpectedly double overnight. Statistically, Ontario’s auto sector supports over 100,000 direct jobs. — Source: [Government of Ontario, 2023].

Consequently, this widespread economic anxiety affects not just CEOs, but thousands of hardworking families across the province. Ontario manufacturers facing tariffs anxiety can achieve supply chain resilience by legally renegotiating vendor debt and pausing creditor payments through a licensed insolvency trustee. Ultimately, acknowledging this anxiety is the vital first step toward implementing a strategic financial turnaround.

Why Mitigating The Impact of Tariffs Matters

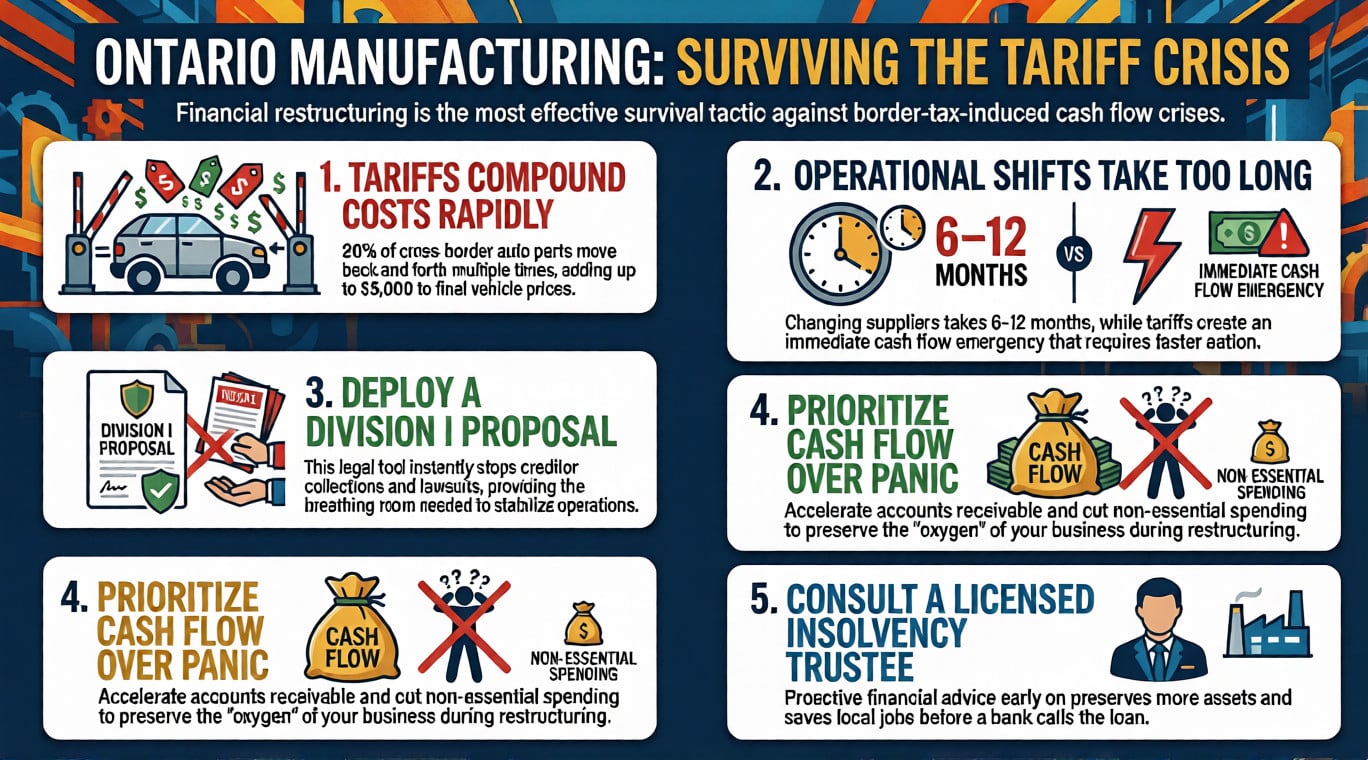
Fundamentally, mitigating the impact of tariffs matters because ignoring these costs will instantly push a healthy manufacturing business into severe corporate insolvency. Actually, the automotive supply chain relies heavily on parts that cross the border multiple times before final assembly. Crucially, cross-border friction and tariffs can add up to $5,000 to the final price of a vehicle. — Source: [TD Economics, 2019]. Therefore, addressing these costs immediately prevents minor cash flow hiccups from becoming fatal financial wounds.

Furthermore, increased costs at the border inevitably result in lower consumer sales and drastic production cuts. Naturally, when assembly lines slow down, smaller suppliers are left with overflowing inventories and no incoming revenue. Unfortunately, commercial insolvencies in Canada surged by 41.4% year-over-year. — Source: [Office of the Superintendent of Bankruptcy, 2024]. Thus, securing professional financial advice early is the only way to avoid becoming another grim statistic.

Core Automotive Supply Chain Resilience Strategies

Strategically, automotive supply chain resilience requires a combination of aggressive cost-cutting, geographic diversification, and formal legal debt relief. First, business owners must recognize that relying solely on operational changes is rarely enough to offset a massive border penalty. Actually, panic is not a strategy; restructuring is a survival tactic. Consequently, proactive executives must explore both operational and financial pathways to secure their company’s future.

The Difference Between Operational Adjustments and Financial Restructuring

Crucially, the difference between operational adjustments and financial restructuring lies in how they address existing corporate liabilities. Initially, operational adjustments involve changing suppliers, moving warehouses, or physically altering how your goods are manufactured. While these operational shifts are necessary for long-term survival, they do absolutely nothing to eliminate the debt you have already accumulated. Conversely, formal financial restructuring specifically attacks your current debt load, providing immediate legal relief from aggressive creditors.

Moreover, operational changes typically require months or even years to fully implement across a complex supply chain. Meanwhile, tariffs-induced anxiety has undeniably dampened hiring plans for 40% of manufacturers. — Source: [First National, 2024]. Therefore, relying solely on operational pivots leaves your company highly vulnerable to bankruptcy during the lengthy transition period. Distinctly, combining both approaches guarantees that your business survives today while preparing adequately for tomorrow’s trade landscape.

Protecting Cash Flow Instantly

Initially, protecting your cash reserves is the absolute most critical step when surviving sudden Ontario manufacturing tariffs. First, audit all your current expenses and aggressively eliminate any non-essential corporate spending. Next, accelerate your accounts receivable by offering small incentives to clients who pay their invoices ahead of schedule. Ultimately, cash is the oxygen of your business, and preserving it gives you time to implement broader cross-border trade strategies.

Renegotiating Vendor Contracts Legally

Legally, renegotiating vendor contracts is a mandatory step when building robust automotive supply chain resilience. Firstly, you must proactively review every single supply agreement to identify clauses related to sudden international tax increases. Often, legacy contracts force the manufacturer to absorb all unexpected border costs entirely. Strikingly, over 70% of Ontario auto parts are destined for the American market. — Source: [Canadian Vehicle Manufacturers’ Association, 2023]. Unquestionably, absorbing a large hit on such a massive volume will immediately bankrupt most mid-sized parts suppliers in Ontario.

Subsequently, executives must initiate transparent conversations with their largest clients and most critical suppliers. Tactically, explaining your financial reality using data builds trust and encourages collaborative problem-solving across the supply network. However, if major clients refuse to share the tariffs burden, you must seriously consider utilizing formal corporate legal restructuring. Ultimately, a contract that guarantees massive financial losses is a contract that must be legally restructured or abandoned.

Importantly, when operational tweaks fail, formal Corporate Restructuring Services provide the ultimate safety net for struggling manufacturers. Specifically, according to Brandon Smith of Ira Smith Trustee & Receiver Inc., mitigating the impact of the U.S. tariffs on Ontario’s automotive supply chain requires utilizing corporate restructuring tools, such as a Division I Proposal, to protect cash flow and avoid bankruptcy. Basically, a Division I Proposal allows your business to legally pause creditor payments while you negotiate a fair financial settlement. Consequently, you remain entirely in control of your daily operations while systematically shedding unmanageable corporate debt.

Additionally, this legal protection immediately halts hostile actions from aggressive vendors or anxious lenders. Suddenly, bank accounts are unfrozen, and threatening collection calls cease completely. Ultimately, filing a formal proposal provides the critical breathing room needed to pivot your operations without the constant threat of facility closure.

An infogrphic showing the steps that Vaughan, Ontario manufacturing companies can enter bankruptcy protection to restructure with a licensed insolvency trustee as a result of tariffs reducing profitability and causing debt problems.
tariffs

Practical Tools for Cross-Border Trade Strategies

Effective cross-border trade strategies utilize specialized financial forecasting software alongside expert legal restructuring frameworks to neutralize border taxes. Fortunately, executives do not need to invent these survival blueprints from scratch. Instead, proven methodologies exist to help map out supply chain vulnerabilities and legally restructure outstanding vendor liabilities. Clearly, U.S.-bound auto shipments account for nearly 30% of Ontario’s international exports. — Source: [Statistics Canada, 2023].

Visually, exploring your options helps demystify the complex corporate turnaround process. Below is a structured comparison of the tools available to combat rising U.S. trade tensions. Specifically, this table contrasts operational adjustments with formal legal protections.

Strategy TypeTool / MethodPrimary BenefitSpeed of Impact
OperationalSupplier DiversificationBypasses border tariffs entirelySlow (6-12 Months)
FinancialCash Flow ForecastingHighlights upcoming cash crunchesFast (Immediate)
Legal ReliefDivision I ProposalStops creditor lawsuits instantlyModerate (with immediate legal protection)
Legal ReliefCorporate BankruptcyCloses unviable businesses legallyModerate (with immediate legal protection)

Thankfully, utilizing these tools prevents the emotional exhaustion that typically accompanies severe corporate financial crises. Interestingly, up to 80% of cross-border auto parts move back and forth multiple times before final assembly. — Source: [Cox Automotive, 2024]. Therefore, mapping these movements with digital tools allows you to accurately predict exactly where the tariffs will inflict the most damage.

What’s Next for Defeating U.S. Trade Tensions

Undoubtedly, the next crucial step for defeating business insolvency Ontario is scheduling a confidential assessment with a Licensed Insolvency Trustee. Simply, waiting for politicians to resolve international trade disputes is a guaranteed way to bankrupt your factory. Instead, you must immediately take decisive control over your company’s balance sheet and outstanding creditor obligations. Ultimately, supply chain resilience is not just about moving factories; it is about restructuring your corporate debt.

Presently, the dedicated experts at Ira Smith Trustee & Receiver Inc. are ready to analyze your unique financial situation thoroughly. First, we will discreetly review your cash flow statements, vendor contracts, and outstanding loan obligations. Next, we will craft a customized restructuring plan designed to pause debt collections and stabilize your manufacturing operations. Emphatically, Contact Us today to secure the immediate legal protection your Ontario business desperately requires.

Evidently, taking proactive action today significantly increases your chances of achieving a successful corporate turnaround. Habitually, businesses that seek professional insolvency advice early preserve more assets and save more local jobs. Therefore, do not let temporary international border disputes destroy the incredible enterprise you have spent years building.

Tariffs Frequently Asked Questions (FAQ)

Naturally, business owners have many pressing questions when facing unprecedented cross-border trade challenges. Below, we address the most common concerns regarding Vaughan, Ontario manufacturing tariffs and corporate survival. Read these expert answers to quickly understand your legal options and operational realities.

Q1: How do the U.S. tariffs impact Ontario automotive supply chains?

A: Financially, the U.S. tariffs drastically increase the cost of materials and finished goods crossing the international border. Because auto parts often cross the U.S.-Canada border multiple times during assembly, this tax compounds rapidly. Consequently, this compounded tax wipes out supplier profit margins, reduces consumer sales, and causes severe cash flow shortages for Ontario manufacturers.

Q2: What are the best cross-border trade strategies to mitigate the U.S. tariffs’ impact?

Operationally, to mitigate tariff impacts, businesses should immediately audit their supply chains to source local Canadian materials where possible. Additionally, companies must update sales contracts to pass on sudden tariff costs directly to end buyers. Most importantly, manufacturers must use legal financial restructuring to free up cash flow trapped by unsustainable debt loads.

Absolutely, corporate restructuring is specifically designed to save viable manufacturing businesses from unexpected macroeconomic debt shocks. Furthermore, according to Brandon Smith of Ira Smith Trustee & Receiver Inc., tools like a Division I Proposal allow businesses to pause creditor payments and renegotiate their debts legally. Ultimately, this legal mechanism provides the crucial breathing room needed to adjust to new tariffs realities and avoid Corporate Bankruptcy.

Brandon’s Take On Tariffs

You’ve worked too hard to let your livelihood get choked out by roadwork you can’t control. Making a move now, instead of waiting for the bank to call the loan, is the smartest thing you can do. The longer you wait and bleed cash, the fewer options you’ll have.

At Ira Smith Trustee & Receiver Inc., we’re in the business of finding permanent solutions for Vaughan business owners. We give you a confidential, zero-judgment space to figure out your next move—whether that’s fighting your landlord or completely restructuring your debt.

Reach out to Ira Smith Trustee & Receiver Inc. today for a FREE, no-obligation chat. Let’s look at your books, figure out your rights, and build a plan to get you through the dust. Call us at (416) 948-6933, hit up IraSmith.com, or just walk into our office at 167 Applewood Crescent in Vaughan. You aren’t doing this alone. We’re here to help you get out of the gridlock.

Ira Smith Trustee & Receiver Inc. has the expertise and experience to guide you through these perilous waters. As Licensed Insolvency Trustees, we are uniquely qualified to assess your company’s financial situation, advise on the best course of action, and help you understand and mitigate your personal risks. We can help you understand your options, assess your personal risk, and develop a strategy to protect your future. Our approach is empathetic, non-judgmental, and focused on finding the best possible outcome for you and your company.

Contact us for a free, confidential consultation. The sooner you act, the more options you have, and the better protected you will be. Let us help you navigate your path to a brighter financial future.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy and is a member of the Canadian Association of Insolvency and Restructuring Professionals.

—————————————————————————

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and my professional expertise as a licensed insolvency trustee. The information provided does not constitute legal or financial advice for your specific circumstances.

Every situation is unique and involves complex legal and factual considerations. The outcomes discussed in this article may not apply to your particular situation. Situations are fact-specific and depend on the particular circumstances of each case.

Don’t hesitate to get in touch with Ira Smith Trustee & Receiver Inc.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a licensed insolvency trustee serving clients across Ontario. With extensive experience in complex court-ordered receivership administration and corporate insolvency & restructuring proceedings, Brandon helps businesses, creditors, and professionals navigate challenging financial situations to achieve optimal outcomes.

Brandon stays current with landmark developments in Canadian insolvency law. He brings this cutting-edge knowledge to every client engagement, ensuring his clients benefit from the most current understanding of their rights and options.

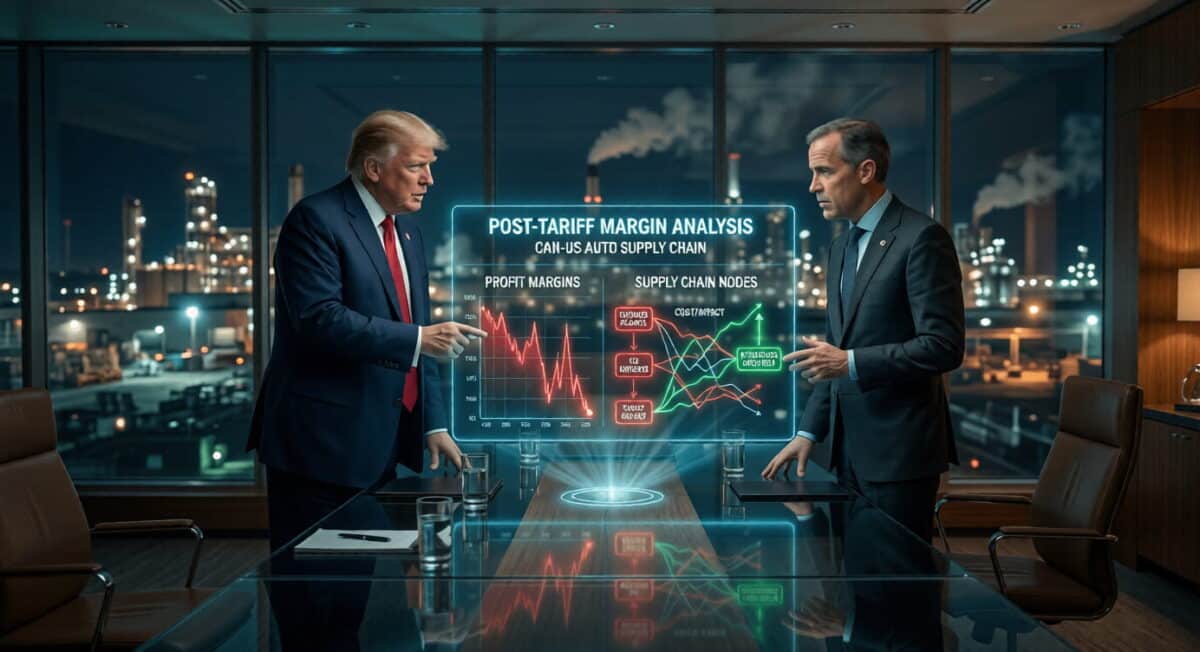
Data visualization of a post-tariffs margin analysis for an Ontario automotive parts manufacturer with President Donald Trump and Prime Minister Mark Carney
tariffs


Categories
Brandon Blog Post

BANKRUPTCY AND BUSINESS FAILURE: WHY THE STATISTICS UNDOUBTEDLY DO NOT TELL THE FULL STORY


bankruptcy and business

Bankruptcy and Business: Introduction

As a licensed insolvency trustee, (previously referred to as a trustee in bankruptcy), my role involves assisting individuals and businesses in managing the complexities associated with entrepreneurship. The conclusion of a business often occurs without fanfare; it is not typically marked by formal announcements or celebratory farewells but rather unfolds quietly amidst the ongoing activity of the market. Despite rising bankruptcy and business failure through the recorded insolvency numbers, many businesses close without it showing up in the insolvency statistics, revealing a deeper truth about economic resilience.

For every corporate insolvency file that I administer, be it the legal process of a bankruptcy protection financial restructuring or a bankruptcy liquidation, there have been many more inquiries from entrepreneurs where the best advice I can give is rather than spending money on corporate bankruptcy, just shut down the business yourself.

In this Brandon’s Blog, which is aimed at Canadian entrepreneurs and their professional advisors, be they financial advisors, lawyers or accountants, I explore the complexities of bankruptcy and business failures, where one fact stands out: the numbers can be deceiving. The current rise in reported business insolvencies has raised eyebrows. But what’s behind these figures? Many businesses close their doors without formally declaring bankruptcy.

Bankruptcy and Business: Types of Business Structures Affected by Bankruptcy

It is essential to understand the different types of business structures that can be affected by or are eligible for bankruptcy. In this section, I’ll explore the impact of bankruptcy on sole proprietorships, partnerships, and incorporated companies.

Sole Proprietorships

A sole proprietorship is a business owned and operated by one individual personally. In the event of bankruptcy, the sole proprietor’s personal assets, including their home, savings, and other personal property, can be used to pay off business debts. This is because, from a legal perspective, the business and the individual are considered one and the same.

Partnerships

A partnership is a business owned and operated by two or more individuals. In the event of one or more partners filing for personal bankruptcy, the partnership’s assets are typically divided among the partners, and each partner is responsible for paying off their share of the debts. However, if one partner files for bankruptcy protection, then the partnership is automatically dissolved. If one partner is unable to pay their share, the other partners are responsible for paying off the remaining business debts.

Incorporated Companies

An incorporated company, also known as a corporation, is a separate legal entity from its shareholders. In the event of bankruptcy, as the corporation is a separate entity, the corporation’s assets are typically liquidated to pay off its debts, and the shareholders are not personally responsible for paying off the debts. However, if the corporation is insolvent, the shareholders may still be at risk of losing their investment.

Key Takeaways

  • Sole proprietorships: The business and the individual are considered one and the same, and personal assets can be used to pay off business debts.
  • Partnerships: Partners are responsible for paying off their share of the debts, or alternatively, each partner is responsible for paying off the entire amount of all debts. If one partner is unable to pay, and especially if one or more partners file for personal bankruptcy, the other partners are responsible for paying off the remaining business debts.
  • Incorporated companies: The corporation’s assets are typically liquidated to pay off its debts, and shareholders are not personally responsible for paying off the debts, but may still be at risk of losing their investment.

Why Understanding Business Structure is Important

Understanding the type of business structure you have is essential in the event of insolvency, as it influences the appropriate debt relief solution that can be developed and executed. The relationship between bankruptcy and your business structure will affect how your assets are managed and how your debts are settled. For instance, if you operate as a sole proprietorship, you may be personally liable for the repayment of business debts. In contrast, if your business is incorporated, your personal assets are typically safeguarded from creditors.

Bankruptcy can impact any business structure; sole proprietorships, partnerships, and corporations. It is important to comprehend the specific business structure you operate under and the implications a bankruptcy protection filing may have on both you and your business. For Canadian entrepreneurs facing challenges with business debt, it is advisable to consult a licensed insolvency trustee to explore available options and make informed decisions regarding your financial situation.

Although parts of the balance of this article will focus on the corporate business structure, most will also be applicable to Canadian business regardless of the business structure.

bankruptcy and business

Understanding Bankruptcy and Business in Canada: A Guide for Businesses

As a Canadian entrepreneur, it is important to recognize that operating a business involves various risks and challenges. Even with diligent management, financial difficulties may arise that jeopardize the viability of your company. In these circumstances, it is essential to be well-informed about the options at your disposal. One widely recognized and effective solution in such situations is corporate bankruptcy.

What is Corporate Bankruptcy in Canada?

Corporate bankruptcy, arising from a corporate insolvency, occurs when a business is unable to pay its overwhelming debts as they become due – that is the definition of an insolvent company. This can happen due to a variety of reasons, including poor cash flow management, increased competition, unexpected expenses, or even a downturn in the economy. When a business becomes insolvent, it may be forced to cease operations, leading to financial losses for its creditors, employees, and shareholders.

Types of Bankruptcy For Corporations in Canada

There are two main types of corporate bankruptcy in Canada: proposal and bankruptcy.

  • Proposal: A corporate proposal is an alternative to bankruptcy. It is a formal payment plan under the Bankruptcy and Insolvency Act (Canada) BIA that allows a business a period of time to settle its debts with its creditors. The proposal is presented to the creditors, who then vote on whether to accept it. If accepted, the proposal then goes to court for approval. When the court approves the proposal, it then is binding on the debtor business and the creditors.

Once the proposal becomes binding, the business can restructure its debt and continue operating by making the monthly payments to the Trustee that it promised to make for the benefit of its creditors. This is otherwise known as a corporate restructuring plan.

  • Bankruptcy: Bankruptcy is also a formal process under the BIA where the business assets are liquidated by selling off its assets. The Trustee then uses the net proceeds of sale to pay for the cost of the corporate bankruptcy process and then to distribute what remains to the unsecured creditors on a pro rata basis according to their claims.

Benefits of Corporate Bankruptcy in Canada

While bankruptcy protection may seem like a last resort, it can actually be a beneficial option for businesses facing financial difficulties. Some of the benefits of corporate bankruptcy in Canada include:

  • Protection from Creditors: Bankruptcy provides a stay of proceedings, which means that creditors cannot take or continue legal action against the business or its assets.
  • Reorganization: Bankruptcy allows businesses to restructure their debt and reorganize their operations to become more sustainable.
  • Fresh Start: Bankruptcy can provide a fresh start for businesses, allowing them to emerge from insolvency and start anew.

When to Consider Corporate Bankruptcy in Canada

If your business is experiencing financial difficulties, it’s essential to seek professional advice from a licensed insolvency trustee. Here are some signs that may indicate it’s time to consider corporate bankruptcy:

  • Cash Flow Problems: Cash flow problems can indicate underlying financial issues within a business. If a company is consistently struggling to pay its bills on time, it is essential to investigate the root causes of this cash flow challenge, as it may reflect broader financial health concerns.
  • High Debt Levels: When a business is burdened with significant debt and faces challenges in meeting its repayment obligations, considering bankruptcy may be a viable option to explore.
  • Loss of Key Customers or Suppliers: Loss of key customers or suppliers can indicate underlying issues within a business that require attention. It is important to analyze the reasons behind this loss, as it may reflect broader challenges affecting the organization’s performance and stability. Addressing these issues promptly can help mitigate potential negative impacts on operations and profitability.

Corporate bankruptcy in Canada is a multifaceted process that can present challenges for businesses in financial distress. However, it can serve as an effective mechanism for companies to address their financial challenges and restructure. By familiarizing themselves with the available options and consulting with qualified professionals, businesses can effectively navigate the bankruptcy process, potentially emerging in a more resilient and sustainable position. Entrepreneurs in Canada facing significant business debt are encouraged to reach out to a licensed insolvency trustee to explore their available options.

Bankruptcy and Business: The Overlooked Landscape of Business Closures

Understanding Bankruptcy and Business Insolvency Filing vs. Closure

Have you ever wondered the difference between a business going bankrupt and closing its doors? It’s important. Business insolvency is the financial condition that the business cannot pay all of its debts as they come due. Business bankruptcy is a legal process where a business files for bankruptcy in order to deal with the distribution of its assets among its creditors in a fair and orderly fashion, as far as the money can go. On the other hand, closure can happen for many reasons, like poor management or market changes. Bankruptcy and business failure many times go hand in hand, but just as often, they don’t.

Reasons For Bankruptcy and Business Failure

Understanding the Common Causes

As a licensed insolvency trustee, I’ve seen firsthand the devastating impact of business bankruptcy on entrepreneurs, employees, and the economy as a whole. While no business is immune to financial difficulties, understanding the common reasons for business bankruptcy can help entrepreneurs take proactive steps to mitigate risks and avoid insolvency.

In this section, we’ll explore the three main categories of reasons for business bankruptcy: Financial Challenges, Operational Issues, and External Factors.

Financial Challenges

Financial challenges are often the most obvious reason for business bankruptcy. Some common financial challenges that can lead to insolvency include:

  • Cash flow management issues: Inability to manage cash flow can lead to delayed payments, missed deadlines, and ultimately, insolvency.
  • High debt levels: Carrying too much debt can put a significant strain on a business’s finances, making it difficult to meet financial obligations.
  • Inadequate funding: Insufficient startup capital or ongoing funding can hinder a business’s ability to grow and operate successfully.
  • Poor budgeting: Failing to create a realistic budget or failing to stick to it can lead to financial difficulties.

Operational Issues

Operational issues can also contribute to business bankruptcy. Some common operational issues that can lead to insolvency include:

  • Inefficient operations: Poorly managed operations can lead to wasted resources, increased costs, and decreased productivity.
  • Lack of scalability: Failing to adapt to growth or changes in the market can lead to operational inefficiencies and financial difficulties.
  • Poor management: Ineffective leadership or management can lead to poor decision-making, which can ultimately result in insolvency.
  • Failure to innovate: Failing to innovate or adapt to changes in the market can lead to stagnation and financial difficulties.

External Factors

External factors can also play a significant role in business bankruptcy. Some common external factors that can lead to insolvency include:

  • Economic downturns: Economic recessions or downturns can lead to reduced consumer spending, decreased demand, and financial difficulties.
  • Competition: Increased competition can lead to reduced market share, decreased revenue, and financial difficulties.
  • Regulatory changes: Changes in regulations or laws can lead to increased costs, decreased revenue, and financial difficulties.
  • Natural disasters: Natural disasters or other external events can lead to significant financial losses and insolvency.

By understanding the common reasons for business bankruptcy, entrepreneurs can take proactive steps to mitigate risks and avoid insolvency. This includes creating a solid business plan, managing cash flow effectively, and staying adaptable to changes in the market. As a licensed insolvency trustee, I’ve seen firsthand the devastating impact of business bankruptcy on entrepreneurs and the economy. By being aware of the common causes of business bankruptcy, entrepreneurs can take steps to avoid insolvency and achieve long-term success.

Statistical Insights

Recent statistics highlight an important trend that merits our attention. Following the 2008 financial crisis, we saw a notable rise in business closures, with many not opting to file for bankruptcy. This is quite surprising, isn’t it?

In the first quarter of this year, Canada experienced 2,003 insolvencies, which included 1,599 bankruptcies and 404 proposals. This marks an 87 percent increase compared to the same quarter last year and represents the highest number of insolvencies in the first three months since early 2008.

Additionally, Statistics Canada provides insights into active businesses by tracking their monthly payroll filings with the Canada Revenue Agency (CRA). Due to a slight delay in data reporting and analysis, the latest figures are from January, showing there were 936,327 active businesses in Canada. However, there were also 43,121 closures, being companies that reported employees to the CRA in December 2023 but did not in January 2024.

“The real tragedy of business closures hides in the shadows of insolvency statistics.”

In light of all this, understanding that a business can disappear without ever declaring bankruptcy is crucial. It paints a clearer picture of our economy. Whether due to management issues or other challenges affecting the viability and solvency of the business, this is a landscape that deserves attention. What are your thoughts on this?

bankruptcy and business

Bankruptcy and Business: The Hidden Truth Behind Business Closures

Understanding the Landscape of Business Failures

Did you know that the actual number of business closures is likely much higher than what insolvency figures reveal? It’s a shocking reality. Business insolvencies are soaring to heights we haven’t seen since the financial crisis of 2008. But here’s the catch: these numbers only represent a fraction of the businesses that are truly shutting down each year.

Why Do Businesses Fail?

Let’s dig into some reasons why businesses fail:

  • Lack of Cash Flow: Many businesses struggle with cash management. Without enough cash coming in, they can’t pay bills.
  • Poor Decision-Making: Sometimes, choosing the wrong direction can lead to disaster. It’s like sailing without a compass.
  • Competition: It’s a wild world out there. If you can’t keep up with your competitors, you may find yourself left behind.

The Significance of Measuring Failures

When you think about it, why are these insolvency numbers so important? They give us a glimpse into the broader economic conditions. However, they don’t paint the full picture. Countless businesses fold without ever going through the insolvency process. This raises the question: how can we better support these struggling businesses?

What Can Be Done?

We need to think creatively. Here are some strategies to consider:

  1. Strong Cash Flow Management: Maintaining robust financial practices can prevent major setbacks.
  2. Seek Guidance: Consulting with business mentors can provide invaluable insights.
  3. Flexibility is Key: Being adaptable to changing market demands can keep a business afloat.

A detailed examination of these factors reveals that each statistic embodies a narrative. Gaining insight into these dynamics enhances our understanding of the current business environment and facilitates the development of more effective solutions.

Bankruptcy and Business: Understanding Business Failures vs. Insolvency Rates

The current trend of rising bankruptcy and business failures can be alarming. We’re seeing numbers that remind us of the financial crisis back in 2008. But here’s the kicker: the official insolvency figures don’t tell the whole story. They only reflect a fraction of the businesses that close each year. So, what’s going on?

The Hidden Truth Behind Business Closures

When a business shuts down, sometimes bankruptcy and business do not go together. The business is insolvent, but as I stated in the introduction to this bankruptcy and business Brandon’s Blog, sometimes the wisest choice for owners is simply to close their doors rather than declare bankruptcy. Of course, in doing so, the business must treat its employees fairly in making sure that all wages and vacation pay are paid up in full, the books and records should be finalized, any leased equipment or consignment goods returned to their owners and all final government returns are filed.

A voluntary business closure raises a few questions:

  • Are entrepreneurs running away from the stigma of bankruptcy and business failure?
  • Do businesses fear the legal complexities of bankruptcy?

The Reality of Business Closures

Many businesses succumb to market pressures, competition, or changing consumer preferences. So even if a business doesn’t file for bankruptcy, it’s still part of a broader trend of bankruptcy and business failure.

Here are some factors contributing to these closures:

  1. Economic downturns: A slowdown can hit sales hard.
  2. Shifts in consumer behaviour: Staying relevant is crucial.
  3. Operational inefficiencies: Sometimes, a business just can’t keep up.

The data presented reflects not merely statistics, but real stories of individuals whose dreams and aspirations have faced significant challenges. Recognizing this broader context is crucial for comprehending the current realities of the business landscape.

bankruptcy and business

Bankruptcy and Business: Understanding Business Failures Beyond Insolvency Numbers

Every year, countless businesses close their doors. But did you know most failures don’t make it to the insolvency list? It’s a striking fact. There’s a lot more happening beneath the surface.

The Real Picture of Business Failures

Business insolvencies are currently rising, reaching levels reminiscent of the 2008 financial crisis. However, these numbers only tell part of the story.

  • Insolvency counts are just the tip of the iceberg. Many businesses close without ever filing for bankruptcy.
  • They might choose to liquidate assets instead, avoiding formal insolvency procedures.
  • Some simply shutter their operation quietly, leaving no trail that stats can follow.

Why Do They Close?

Now, let’s dig deeper. Why do businesses close? Here are a few key reasons:

  1. Market changes: Trends shift rapidly. A product that sells today may be yesterday’s news tomorrow.
  2. Lack of funds: Often, owners run out of cash. It’s not always about being in debt.
  3. Poor planning: Without a solid business plan, success becomes a game of chance.

It’s critical to understand these points. When we consider the broader picture, it becomes clear that the narrative of bankruptcy and business failure encompasses much more than insolvency figures. So, when you hear those numbers, remember: behind every statistic, there’s a unique story. It’s worth exploring.

Bankruptcy and Business Behind the Scenes: A Personal Journey with Business Failure

Let me describe to you, with no names of course, about an entrepreneur who recently consulted with me. He truly believed in his retail business. It was welcoming, colourful, and brimming with potential. He had dreams of providing the best customer service in town. But, not long after the grand opening, he saw that it wasn’t working out. The foot traffic was lower than he anticipated, and the expenses kept piling up. He had to close the doors within a year of opening. It felt like a hard punch to his gut.

Lessons Learned

From this experience, he learned a few invaluable lessons:

  • Resilience is Key: Every setback can teach us something. We just need to be open to those lessons.
  • Adaptability Matters: The ability to pivot quickly can save a business. If he had been more flexible and had some staying power, perhaps he could have found a way to make it work.
  • Not All Bankruptcy and Business Failures Reflect Capability: Just because a venture doesn’t succeed it doesn’t mean that the person is not capable as an entrepreneur.

The Emotional Toll

Closing his store was not just a business decision; it hit him hard on a personal level. There’s a saying:

“Failure isn’t the opposite of success; it’s part of success.”

This resonated with him throughout the process. He felt a profound sense of loss—not just for his dream, but for his team and the community, albeit small, that had begun to form around his business. It’s important to recognize that every business closure affects many lives.

He will cherish the memories, good and bad. We often think of success as the ultimate goal. However, failures

can be just as important. After all, they prepare us for the next big opportunity.

Bankruptcy and Business: The Economic Ripple Effect of Silent Failures

Have you ever stopped to think about the impact of a business closing its doors quietly? It’s alarming. Each silent closure sends ripples through our communities. But how exactly does this happen?

Understanding the Broader Economy

When a business goes unnoticed, its effects are profound. For small towns and cities, local businesses are often the lifeblood of the economy. They provide jobs and foster a sense of community. But when they fail, a series of consequences unfold.

  • Potential job losses: Every unnoticed closure often results in job losses. It’s estimated that thousands of jobs are impacted as small businesses close each year.
  • Supply chain impacts: Smaller firms are interwoven into larger supply chains. When they disappear, disruptions occur, affecting many others reliant on their goods or services.

A Community Heartbreak

The silence surrounding these closures can be deafening.

“Every business closure is a community heartbreak.”

This isn’t just a catchy phrase; it’s the reality for many.

Large corporations may withstand economic struggles, but small businesses often can’t. Imagine a local diner you frequently visit, or a beloved independent bookstore. If these establishments close, the repercussions extend beyond just lost revenue. They can alter job security and change local culture.

We often overlook just how many jobs depend on these small firms. Have you considered what happens to job seekers when they vanish?

bankruptcy and business

Bankruptcy and Business: Preventing the Silent Nightmare of Business Closure

We all know that running a business can feel like navigating through a storm. Sometimes, even the most resilient enterprises can face economic downturns that threaten their very existence. So, how do we ensure survivability? Here are some strategies to consider:

1. Embrace Innovation

  • Adapt to Market Trends: Staying ahead means constantly evaluating what’s working and what’s not. Are your customers shifting their preferences? Innovate to meet their needs.
  • Leverage Technology: Digital tools can streamline operations and reach wider markets. Tools like social media and e-commerce platforms can significantly boost visibility.

2. Cultivate Adaptability

We must understand that adaptability is key. If we don’t learn and pivot, we risk stagnation. Have you ever noticed how quickly the business landscape shifts? Continuous learning is not just a phrase; it’s a necessity. Training programs and workshops can enhance our expertise.

3. Build Community Support

One of the most effective strategies is building a strong support system. Entrepreneurs often feel isolated—this needn’t be the case. Engaging in community networks or mentorship programs can provide valuable guidance.

Imagine a gardener tending to a plant. It needs nurturing, sunlight, and sometimes a bit of pruning. Similarly, businesses thrive in supportive environments where they can learn and adapt. We need to reinforce this sense of community, where sharing experiences can lead to encouragement and growth.

Finally, I want to acknowledge that the journey is indeed tough. Yet, it is essential to focus on personal resilience. Everyone faces challenges. But through understanding and support, we can not only overcome but also flourish!

I urge you to seek out success stories, too. Businesses that have pivoted successfully often serve as a beacon of hope. They illuminate paths we never considered. By sharing our experiences and challenges, we help each other to thrive.

Bankruptcy and Business: Shining a Light on Shadows

As we’ve explored the complexities of business failures, one fact stands out: the numbers can be deceiving. The current rise in business insolvencies has raised eyebrows. But what’s behind these figures? Many businesses close their doors without formally declaring bankruptcy. This distinction is critical for understanding the health of our economy. Not all failures are recorded in official statistics. Every year, countless ventures close down quietly, leaving little trace. Each shuttered business represents dreams, investments, and hard work.

As we wrap up our discussion, it’s clear that *business failures* are more common than we often admit. Many business owners might feel isolated, and that’s understandable. But recognizing the reality of these failures is essential. It reminds us that every entrepreneur’s journey is difficult yet filled with opportunities to learn and grow.

Here are some key points we’ve explored:

  1. The numerous factors that contribute to business closures.
  2. The impact of community support on a business’s survival.
  3. How understanding failures can lead to future successes.

    bankruptcy and business
    bankruptcy and business

Bankruptcy and Business in Canada: FAQ

1. What is the difference between a business closing and a business going bankrupt?

Business closure and bankruptcy are distinct concepts in the realm of business operations.

Business closure refers to the termination of a business’s operations for various reasons. These reasons may include factors such as ineffective management, shifts in market conditions, or a deliberate choice by the owner to cease operations.

On the other hand, business bankruptcy is a legal process defined by the BIA in Canada. This occurs when a business officially declares its inability to meet its financial obligations. The bankruptcy process typically involves either restructuring debts through a formal proposal or liquidating business assets to repay creditors.

It is important to note that while bankruptcy often results in the closure of a business, not all closures are accompanied by bankruptcy proceedings. A business can close without filing for bankruptcy, opting instead to liquidate its assets and settle any outstanding debts on its own.

2. What are the main types of corporate bankruptcy in Canada?

Canada provides two main avenues for corporations encountering bankruptcy:

  • Proposal: This option involves submitting a formal payment plan to creditors for their approval. If the proposal is accepted and subsequently sanctioned by the court, the business can restructure its debts, continue its operations, and repay creditors over an extended period.
  • Bankruptcy: In this scenario, the corporation liquidates its assets to settle debts with creditors. The proceeds from the asset sales are allocated to creditors, starting with secured creditors, followed by a proportional distribution of any remaining funds to unsecured creditors.

3. What are some common reasons for business failure?

Business failure can result from various issues that can be categorized into three main areas:

Financial Challenges:

  • Poor cash flow management
  • High levels of debt
  • Insufficient funding
  • Ineffective budgeting practices

Operational Issues:

  • Inefficient operational processes
  • Inability to scale operations
  • Subpar management practices
  • Lack of innovation

External Factors:

  • Economic downturns
  • Heightened competition
  • Changes in regulations
  • Natural disasters

4. Why is the number of business closures likely higher than official insolvency statistics suggest?

Many businesses choose to close their doors without formally filing for bankruptcy. This could be due to several reasons:

  • Avoiding the stigma of bankruptcy: Some entrepreneurs may perceive bankruptcy as a personal failure and opt for a quiet closure.
  • Complexity and cost of bankruptcy proceedings: The legal processes involved in bankruptcy can be daunting and expensive, deterring some businesses.
  • Strategic decision to liquidate independently: Owners may decide to manage the closure process themselves, selling assets to settle debts outside of formal insolvency proceedings.

5. What are the economic consequences of unrecorded business closures?

Unrecorded closures have a significant impact on the economy:

  • Job losses: Closures, whether reported or not, often lead to job losses, impacting individuals, families, and communities.
  • Supply chain disruptions: Small businesses are often integral to larger supply chains. Their closures can disrupt these networks, impacting other businesses reliant on their goods or services.
  • Reduced economic activity: Closures reduce overall economic activity in communities, impacting local spending, tax revenue, and overall economic health.

6. What are some strategies to help businesses avoid closure?

  • Embrace innovation: Adapting to market trends, leveraging technology, and developing new products or services can help businesses remain competitive.
  • Cultivate adaptability: Continuous learning, training, and willingness to adjust strategies can improve resilience in the face of change.
  • Build community support: Engaging with local networks, seeking mentorship, and fostering collaboration can provide valuable resources and guidance.
  • Prioritize financial management: Strong cash flow management, responsible budgeting, and careful debt management are crucial for business stability.

7. How can we better understand the true landscape of business closures?

  • Improved data collection: Implementing better tracking mechanisms to capture closures beyond formal insolvency filings could provide a more accurate picture of business failure rates.
  • Research and analysis: Studying the reasons behind unrecorded closures can offer insights into common challenges and potential solutions.
  • Open dialogue and awareness: Encouraging entrepreneurs to share their experiences, both successes and failures, can normalize conversations about business closure and facilitate learning.

8. What is the key takeaway from understanding the difference between business closures and bankruptcy?

Recognizing that business closures are more prevalent than official insolvency statistics indicate is crucial. It highlights the challenges faced by entrepreneurs and emphasizes the need for support systems, innovation, adaptability, and sound financial management to foster business success and resilience. Acknowledging the silent failures allows for a more accurate understanding of the economic landscape and can help policymakers and support organizations develop strategies to address these challenges and better support businesses.

Bankruptcy and Business: Conclusion

So, why is it important to acknowledge these failures? It’s simple. They are not just numbers on a report; they are the culmination of hard work, dreams, and sometimes missteps. When a business fails, it can feel like a dark cloud, but it can also be the start of something new.

I hope you enjoyed this bankruptcy and business Brandon’s Blog. Do you or your company have too much debt? Are you or your company in need of financial restructuring due to distressed real estate or other reasons? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or someone with too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding the bankruptcy process. We can get you debt relief freedom using processes that are a bankruptcy alternative.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a plan, we know that we can help you.

We know that people facing financial problems need a realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team.

That is why we can develop a restructuring process as unique as the financial problems and pain you are facing. If any of this sounds familiar to you and you are serious about finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation. We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The information provided in this Brandon’s Blog is intended for educational purposes only. It is not intended to constitute legal, financial, or professional advice. Readers are encouraged to seek professional advice regarding their specific situations. The content of this Brandon’s Blog should not be relied upon as a substitute for professional guidance or consultation. The author, Ira Smith Trustee & Receiver Inc. as well as any contributors to this Brandon’s Blog, do not assume any liability for any loss or damage resulting from reliance on the information provided herein.

bankruptcy and business
Categories
Brandon Blog Post

BILL C-228: WILL HUGE PENSION PRIORITY IN CANADIAN INSOLVENCY BE REAL FINALLY?

Bill C-228: Are pensions protected in Canadian insolvency proceedings?

The long-awaited Bill C-228, an Act to amend the Bankruptcy and Insolvency Act, the Companies’ Creditors Arrangement Act and the Pension Benefits Standards Act, 1985 proposes to give priority and therefore some financial security to pensions of workers in the event of a Canadian insolvency of their employer, may finally soon become law. This is a significant victory for pensioners and unions across the country who have been advocating for this change for many years.

This new law will provide much-needed protection for pensioners in case of the insolvency of pension plan sponsors. It is a major step forward in ensuring that pensioners are able to retire with dignity, security and frankly, what they bargained for.

Bill C-228: Right now pensions in bankruptcy can be taken away

The Canadian insolvency system has come under heavy analysis and criticism for years for its treatment of pensioners when the employer goes bankrupt or files for bankruptcy creditor protection. Bill C-228 comes from a long line of private members’ bills presented in the House of Commons of Canada that never went anywhere – until now. It makes every effort to make previous employees getting a pension, and those who someday expect to get payments from their pension plan, a priority in the insolvency process.

In this Brandon’s Blog, I discuss the current status of Bill C-228 and its implications in making pensioners a priority in bankruptcy if it becomes law as presently composed.

Bill C-228
Bill C-228 An Act to amend the Bankruptcy and Insolvency Act, the Companies’ Creditors Arrangement Act and the Pension Benefits Standards Act, 1985

Bill C-228: What can cause you to lose your pension?

Underfunding is a major concern for traditional, defined-benefit pension plans (DB Pension Plans). In other words, do they have enough pension assets and therefore enough money to meet their projected future pension obligations of insolvent pension funds? Inadequate actuarial assumptions, poor investment returns, and mismanagement can lead to pension plan underfunding. In the case of corporate insolvency of a large employer with a DB Pension Plan, this issue always arises. Underfunded pensions in bankruptcy wind up hurting retirees.

The Sears Canada court-supervised liquidation forced us to again focus on the treatment of pensioners in corporate bankruptcies under the Bankruptcy and Insolvency Act (Canada) (BIA) or restructurings and liquidations under the Companies’ Creditors Arrangement Act (CCAA). It was widely reported that representative for 17,000 Sears Canada retirees says insolvency laws are unjust when it comes to underfunded pensions.

When a company is insolvent and its DB Pension Plan is underfunded, pensioners suffer pension losses and ultimately income losses. In practice, pensioners’ rights are weak and highly inadequate, especially when pension plans are underfunded.

Although pension legislation at the provincial and federal level purports to offer some protection for amounts owing to an underfunded pension plan, insolvency legislation does not preserve that protection for the majority of those amounts. The insolvency protection of pensioners and pensions in bankruptcy proceedings is therefore limited.

Dr. Janis Sarra is the founder and director of the National Centre for Business Law and a professor at the Peter A. Allard School of Law. In her opinion, Canadian pensioners and employees are among the worst-protected pensions in bankruptcy and/or insolvency among 60 countries.

The history leading to Bill C-228

Let’s look at some history of attempts to protect pensions in bankruptcy. The Canadian Association for Retired Persons (CARP), a nationwide advocacy organization for Canadian seniors and retirees, lobbied politicians on Parliament Hill about legislation changes. According to CARP, the unfunded pension liability should be given priority so that it is handled first.

There is no priority for retirees when it comes to dividing up assets in bankruptcy, and CARP wanted to protect underfunded DB Pension Plans when the employer company goes through restructuring or bankruptcy.

CARP estimated that roughly 1.3 million Canadians, aside from the retired Sears employees, may be at risk due to underfunded DB Pension Plans. The closure of Sears Canada stores made the plight of retirees a top priority for CARP.

Marilène Gill, Bloc Québécois MP, introduced a member’s BILL C-372, on Oct. 17, 2017. It was intended to change the BIA and the CCAA. The change sought to correct the injustice faced by retired workers whose pension and health insurance policy benefits are not secured when their company declares bankruptcy or undergoes restructuring.

On October 17, 2017, Bill C-372 passed its first reading. The House rarely passes private member’s bills like this one. The Liberal Party did not support taking it further and allowed it to die.

Hamilton Mountain NDP MP Scott Duvall asked for leave to introduce Bill C-384 in the House of Commons on November 6, 2017. He proposed amending Canada’s insolvency laws so that companies must bring any pension fund to 100% before paying any other secured creditors. Additionally, it required companies to pay termination or severance pay owing before paying secured creditors. Similarly, this bill passed the first reading and then died.

Then, Senator Art Eggleton, P.C., proposed BILL S-253 shortly before his retirement to amend the insolvency legislation to deal with a pension deficit in Canada. After the first reading passed on September 18, 2018, the second reading followed on September 25. By introducing this bill, the BIA and CCAA would be amended. The plan proposed to give priority to claims for unfunded obligations or solvency deficiencies of pensions. This was applicable to both solvent companies as well as companies that might become insolvent if certain shareholder payments were made. That bill never went any further.

Bill C-228
Bill C-228 An Act to amend the Bankruptcy and Insolvency Act, the Companies’ Creditors Arrangement Act and the Pension Benefits Standards Act, 1985

The current Bill C-228: Pension Protection Act

Then, Conservative MP Marilyn Gladu put forward her pension reform private member Bill C-228: An Act to amend the BIA, the CCAA and the Pension Benefits Standards Act, 1985. It passed 2nd reading on June 22, 2022.

According to the Hansard transcripts, she noted that the proposed legislation would ensure that pension funds would be paid before secured and unsecured claims. Unremitted source deductions for the Canada Pension Plan, Quebec Pension Plan, Employment insurance, and taxes would be taken first. Suppliers who take back goods delivered within a month of bankruptcy or receivership and unpaid wages or salaries would be paid next. Then payment for insolvent pensions would come next before the claims of secured and unsecured creditors.

It then got a referral to committee, the Standing Committee on Finance. Once the referral to the Finance Committee happened, it did not take long to get through the committee. The committee held three meetings between October 17 and 31. It passed through the committee and on November 23, 2022, it passed 3rd reading and Bill C-228 was adopted.

A cross-party collaboration of New Democrat, Bloc and Conservative MPs was now finally achieved in order to move forward with key legislation to protect workers’ pensions in commercial bankruptcy or insolvency proceedings. The Liberal government which previously did not have this on its radar also voted in favour. In fact, PM Trudeau has tried to take some credit for this private member’s bill in the House of Commons.

The bill has now moved on to the Senate of Canada for review and amendment before returning to the House for final approval. It passed its first reading in the Senate on November 24. It now seems to have sufficient support and momentum to ultimately become law.

The current Bill C-228: What will the Pension Protection Act do?

The purpose of the private member’s Bill C-228, which will be known as the Pension Protection Act. is to deal with the insolvency of an employer where there is an unfunded liability or solvency deficiency in an employee pension plan or the employer ceases to fund a group insurance plan. It will prioritize the pension payments for such pensioners and employee claims for pension entitlements.

The proposed legislation would also amend the Pension Benefits Standards Act, 1985 to require the annual tabling of a report on the solvency of pension plans.

The current wording of the proposed legislation proposes to accomplish pension security for retirees by amending existing legislation to deal with deficiencies of pension plans as follows:

  • BIA section 60(1.‍5)‍(a)‍, is the section that deals with employers trying to restructure through a BIA restructuring proposal. It already states that any pension amounts deducted from employees that were not paid into the pension fund must be in order for the court to consider approving the proposal.
  • It will be amended such that the court cannot approve any employer restructuring proposal unless it stipulates that any amount required to make all special payments, as determined by section 9 of the Pension Benefits Standards Regulations, 1985, that should have been paid to correct any unfunded liability or solvency deficiency will be funded by the employer.
  • It will also be amended so that any amount required to liquidate any other unfunded liability or solvency deficiency of the fund as determined at the time of the filing of the notice of intention or of the proposal if no notice of intention was filed, will be included.
  • BIA sections 81.5 and 81.6, are the sections that deal with the event of bankruptcy proceedings and receivership proceedings. They will similarly be amended.
  • CCAA section 5, which deals with the employer company with a pension plan, will be amended the same as the proposed amendments to the BIA. This will state that if the company participates in a prescribed pension plan for the benefit of its employees, the court may not sanction a compromise or arrangement unless there are the same provisions stated above to protect the interests of the employees.
  • The Pension Benefits Standards Act, 1985 will be amended to require greater annual report requirements on the solvency of pension funds and their success in meeting funding requirements, and the corrective measures taken or directed to be taken by the Superintendent of Financial Institutions to deal with any pension plan not meeting the funding requirements.

As indicated above, there appears to be enough momentum for Bill C-228 to get through the Senate and ultimately receive Royal Assent to become an Act of Parliament. This will no doubt be a major change to bankruptcy protection insolvency proceedings in Canada relating to benefit plans if it becomes the new law dealing with pension plan deficits.

We will have to see if this Bill becomes law, once implemented and if there will be any unintended consequences. Time will tell if these changes will not have negative consequences on corporate restructuring and advisory, preventing what previously would have been successful restructurings of Canadian businesses, albeit on the backs of hard-working Canadians being the employees and retirees.

No doubt the insolvency community and the lending community will have to adjust to the new business environment. I will provide you with updates as they occur.

Bill C-228
Bill C-228 An Act to amend the Bankruptcy and Insolvency Act, the Companies’ Creditors Arrangement Act and the Pension Benefits Standards Act, 1985

Bill C-228 transition period

The Bill, if passed, would introduce a four-year transition period between its implementation and the implementation of the proposed amendments. My guess is that such a long transition period has been established for two main reasons:

  1. to allow companies who currently are behind in their defined pension benefit payments to catch up; and
  2. to allow the lending community to try to figure out how they are going to adjust their commercial lending practices in this new reality.

Bill C-228: Pension reform to insolvency

I hope you enjoyed this Bill C-228 An Act to amend the Bankruptcy and Insolvency Act, the Companies’ Creditors Arrangement Act and the Pension Benefits Standards Act, 1985, Brandon’s Blog.

Revenue and cash flow shortages are critical issues facing entrepreneurs and their companies and businesses. Are you now worried about just how you or your business are going to survive? Those concerns are obviously on your mind. Coming out of the pandemic, we are now worried about its economic effects of inflation and a potential recession.

The Ira Smith Team understands these concerns of businesses and people facing a mountain of unsecured claims and financial liabilities. More significantly, we know the requirements of the business owner or the individual that has way too much financial debt. You are trying to manage these difficult financial problems and you are understandably anxious.

It is not your fault you can’t fix this problem on your own. The pandemic has thrown everyone a curveball. We have not been trained to deal with this. You have only been taught the old ways. The old ways do not work anymore. The Ira Smith Team makes use of new contemporary ways to get you out of your debt problems while avoiding bankruptcy. We can get you debt relief now.

We have helped many entrepreneurs and their insolvent companies who thought that consulting with a trustee and receiver meant their company would go bankrupt. On the contrary. We helped turn their companies around through financial restructuring.

We look at your whole circumstance and design a strategy that is as distinct as you are. We take the load off of your shoulders as part of the debt settlement strategy we will draft just for you.

We understand that people facing money problems require a lifeline. That is why we can establish a restructuring procedure for you and end the discomfort you feel.

Call us now for a no-cost consultation. We will listen to the unique issues facing you and provide you with practical and actionable ideas you can implement right away to end the pain points in your life, Starting Over, Starting Now.

Bill C-228
Bill C-228 An Act to amend the Bankruptcy and Insolvency Act, the Companies’ Creditors Arrangement Act and the Pension Benefits Standards Act, 1985


Categories
Brandon Blog Post

RESTRUCTURING OF COMPANY: SOMETIMES AN UNPOPULAR CORPORATE BANKRUPTCY IS NEEDED TO RESTRUCTURE YOUR COMPANY TO IMPROVE PROFITS

restructuring of company

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic. Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

Restructuring of company introduction

Following its bankruptcy, Canadian retailer Le Château announced that it would relaunch online under new ownership. Although extreme, in certain unique circumstances, corporate bankruptcy could be used to restructure a company’s debt and operations.

Often, companies realize they need to restructure too late when fewer options remain and saving the company is more challenging. A restructuring process started on a voluntary basis can generate greater value than a company restructuring done under the imminent threat of bankruptcy.

A restructuring plan is more likely to succeed when managers understand the fundamental business/strategic challenges their company faces. In a corporate restructuring, creditors are often required to make significant concessions, which have significant implications for them as well as for the company.

Using the Le Château case as an example, this Brandon Blog discusses certain aspects of the restructuring of company debt, assets, and operations.

restructuring of company

Restructuring of company: Le Château relaunches online following bankruptcy

Following its filing for bankruptcy protection last year, Le Château, now run by Suzy’s Inc., announced its comeback from bankruptcy by launching an eveningwear collection online before the holidays. YM Inc., which owns many brands including Suzy Shier, acquired the intellectual property assets and certain merchandise and other assets.

Herschel Segal founded Le Château Inc. in 1959 as “Le Chateau Men’s Wear”, a menswear store in downtown Montreal’s Victoria Square. Le Château began selling imported clothes from Europe when it added women’s clothing in 1962. As time passed, Le Château sold more fashionable imports to young people instead of its original traditional clothing style. Since then, Le Château has designed, imported, and retailed apparel, accessories, and footwear for women and men.

Its 240 locations at its peak made the Canadian retailer a staple of nearly every mall and shopping district in the country. Le Château Inc. (and its US subsidiary Château Stores Inc.) filed for bankruptcy protection in October 2020 under the Companies’ Creditors Arrangement Act (“CCAA”). It also announced it would close all 123 stores in Canada. The Court granted the companies permission to run a liquidation process in November 2020. It used the CCAA to liquidate its assets rather than for the restructuring of company operations and finances.

To adapt to new retail industry trends, the company implemented efforts to right-sized its brick-and-mortar locations. 122 of its 243 stores were closed during the eight years prior to filing for bankruptcy. The Company’s right-sizing efforts and its important investment in its e-commerce platform helped mitigate the decline in brick-and-mortar revenue, but not enough to compensate. During the three fiscal years prior to its insolvency filing, the Company lost about $130 million in net income. As COVID-19 arrived in March 2020, the end of Le Château was sealed. Proms, weddings, galas, and parties were cancelled, decimating the retailer’s dress sales.

Le Château began liquidating its 121 stores in November 2020, as well as its transactional website. In December 2020, the licensed insolvency trustee acting as CCAA Monitor was also appointed Receiver because all assets were secured by loans to various financial institutions. A court granted the Company’s request to approve a sale transaction with Suzy’s Inc. in June 2021. Le Château’s intellectual property, merchandise, furniture, fixtures, equipment, and signage were purchased by Suzy’s. At that point, the inventory liquidation was completed. Before the Canadian company filed for bankruptcy, the companies changed their names to plain numbered companies as part of the sale of the intellectual property.

A bankruptcy filing was made by the company formerly known as Le Château Inc. on September 2, 2021. Le Château, now run by Suzy’s Inc., has announced its comeback from bankruptcy with the launch of an eveningwear collection ahead of the holidays.

restructuring of company

Restructuring of company: Reasons for corporate restructuring

If the company is both insolvent and not viable in its existing form, the normal insolvency process would be receivership, bankruptcy or both. Instead of using the provisions of the CCAA to liquidate a major retailer, a Court-appointed receiver appointed under Quebec law as well as the Bankruptcy and Insolvency Act (Canada) would have accomplished the same thing as the CCAA process used.

In the example of Le Château, selling assets out of a financially sick corporation to a new owner who will operate the assets in a similar business is actually a form of restructuring of company operations. Because the old corporation has too much debt and too many operational problems, it cannot continue. However, as Suzy Shier has shown, there was a good business reason for them to buy certain assets, and they now plan to run a new Le Château business. A new owner was responsible for the restructuring of company operations and finances.

As a result of a financial crisis, a company may undergo restructuring to change the financial or operational aspects of its business. Restructuring can occur for several reasons, including:

  • deteriorating financial fundamentals;
  • a lack of profitability;
  • disappointing sales revenue;
  • debt that is too high; and
  • an industry with too much competition or the company is no longer competitive.

Under financial duress, a company engages in restructuring when it makes significant changes to its financial or operational structure. In reorganizing internally, a company’s operations, processes, departments, or ownership may change, enabling it to be more integrated and profitable. If shareholders and creditors reach an agreement on a reorganization of assets, issuance of equity to reduce debt, or bankruptcy as long as the business maintains operations, the company may sell its assets.

Restructuring a company usually involves cutting costs, such as payroll, or shrinking the company through asset sales. After restructuring is completed, the business operations should become smoother and more economically sound.

restructuring of company

Restructuring of Company: The company restructuring process

Restructuring a company has many benefits, as well as many reasons for a company to restructure. The benefits of corporate reorganization can be summarized in two words: survival and success. The right financial advisory firm can help business owners deal with these challenging issues, whether they are reorganizing for survival or strategic repositioning for the future.

Your company should select restructuring professionals who are experienced in your specific industry as well. As soon as major problems are discovered, the company should begin restructuring its operations and finances. Early diagnosis allows a company to fully evaluate its options and avoid being cornered.

Corporate business restructuring can be divided into several stages:

  • assessing the organizational restructuring needed;
  • implementing the organizational restructuring;
  • identification of weaknesses;
  • developing detailed plans to correct these weaknesses through restructuring;
  • calculating and securing funding;
  • raising private equity to help improve operations and balance sheet;
  • evaluating the impact of implemented strategies and amending them as necessary;
  • comparing actual financial results to the budget to ensure the restructuring remains on track; and
  • making necessary corrections.

Companies often do not allow enough time to plan and implement restructurings. A successful restructuring of a company’s finances and operations depends on how much upfront assessment work was done, how detailed the plan is, and how well the restructuring strategy is implemented.

Reorganizations can take a long time depending on whether they are reactive or proactive. An example of a reactionary restructuring is when bankruptcy proceedings force a company to make changes within a specified period. A corporate executive officer who recognizes a change in consumer preferences and positions their company to be a leader in tomorrow’s market is an example of being proactive.

In today’s economy, companies face many challenges, and company restructuring can be a short- and long-term answer to maintaining company viability. Company restructuring concerns vendors and consumers, stockholders and financial relationships, employees and inventory, quality control and environmental impact, equipment and technology, and management and marketing.

In addition to the reasons for restructuring, every major restructuring has some of these common elements:

  • an improved balance sheet;
  • reduced tax obligations;
  • divesting underproductive assets;
  • Outsourcing some functions that can be more cost-effectively done by outside suppliers rather than by company employees;
  • reducing debt loads;
  • relocating operations;
  • restructuring marketing, sales, and distribution;
  • renegotiating employment contracts;
  • refinancing debts; and
  • changing the company’s public image.

Restructuring company operations and finances are expected to result in long-term survival, profitability, and viability, regardless of the reasons and the specific steps taken.

restructuring of company

Restructuring of company summary

I hope this restructuring of company Brandon Blog post was helpful for you. Are you worried about your financial situation because you are dealing with substantial debt challenges as a business owner or as an individual? Call me if you have too much debt. It is not your fault. To deal with financial problems, you have actually only been shown the old ways. These old methods no longer work.

The Ira Smith Team employs new modern methods to get you out of debt while avoiding bankruptcy. Let us help you obtain the relief you deserve.

You are under a lot of pressure. We understand your discomfort. A new approach will be designed for you that is as unique as you and your issues, both financial and emotional. Your burden will be lifted and the dark cloud hanging over you will be blown away. We will design a debt settlement strategy for you. We are confident that we can assist you right away.

People and businesses facing financial troubles need a realistic lifeline. There is no one-size-fits-all approach with the Ira Smith Team. Even though we are licensed insolvency trustees, we have found that not everyone has to declare bankruptcy in Canada. Most of our clients never declare bankruptcy. We help people and companies avoid bankruptcy.

This is why we can create a new restructuring process for paying off debt that will be custom-built for you. You’ll have a unique experience, just like the economic difficulties and discomfort you are experiencing. If any of these describe you and you are serious about finding a solution, contact the Ira Smith Trustee & Receiver Inc. group today.

Call us now for a no-cost consultation. Let us get you or your business back on track, driving to healthy and balanced trouble-free operations and eliminating the discomfort factors in your life, Starting Over, Starting Now.

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic. Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

restructuring of company
Categories
Brandon Blog Post

REVERSE VESTING ORDER: 1 REMARKABLE CREATIVE WAY TO DO FINANCIAL RESTRUCTURING

reverse vesting order

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic.

Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

If you would prefer to listen to the audio version of this Brandon Blog, please scroll to the very bottom of the page and click play on the podcast.

Vesting order and reverse vesting order

In a corporate insolvency case, a court may grant a vesting order, which authorizes the sale of a company’s assets to the buyer once the purchase price is paid. A vesting order vests ownership in the purchaser as a result of this court order. This is proof that the purchaser is entitled to transfer the assets into its name. No matter what insolvency process is used, this is the use of a vesting order.

In the past year or so, a new trend has emerged regarding the sale of the assets of insolvent companies as part of a restructuring under the Companies’ Creditors Arrangement Act (CCAA). That new trend is the use of a reverse vesting order.

In this Brandon Blog, I explain what a reverse vesting order is and why I believe its use will be a significant feature of Canadian firm restructurings in 2021 and beyond.

Reverse vesting order – A powerful tool for maximizing recovery in complex insolvencies

A reverse vesting order can be very useful in complex insolvencies. A timely recovery can benefit creditors, and the process can maximize recoveries for all parties. Reverse vesting orders are a good solution for an insolvent debtor corporation when:

  • there are a large number of secured creditors, unsecured creditors and assets;
  • all of the assets do not have an immediate buyer;
  • the company is insolvent; and
  • the company must deal with unwanted assets and a group of creditors in a particular way.

It is best used in a large-scale CCAA corporate restructuring but is not limited to that.

reverse vesting order

Reverse vesting order as a third restructuring tool

There have traditionally been two insolvency processes available to licensed insolvency trustees, insolvency lawyers, and company stakeholders. The two are (i) liquidating assets; and (ii) reorganizing companies. In general, assets are liquidated through either receivership or bankruptcy. Incorporated companies can restructure either under the provisions of the Bankruptcy and Insolvency Act (Canada) (BIA) or, for larger and more complex restructurings, under the CCAA. It is obvious that assets must be sold in order to liquidate them.

Sometimes, as part of a corporate restructuring, there are redundant and unwanted assets that can be sold to raise cash. The question is, what if the real value, especially a going-concern value of a company in a commercial insolvency case is not in its tangible assets. Rather, its real value lies in:

  • the ability to operate in a specific industry and such licenses cannot be sold by their very nature and wording – think of the cannabis and nursing home industries as two examples;
  • tax losses and tax attributes that can be monetized if the licensed insolvency trustee is also able to take over the shares; or
  • being listed on the stock exchange and thus as a public company having a greater market value than a private corporation.

As a result, it is extremely difficult to realize any value from such assets.

What is the importance of the reverse vesting order? How a reverse vesting order works will tell you all you need to know about why it is important as a third restructuring tool. Under a reverse vesting order, a newly incorporated residual corporation is added as a party to the CCAA proceedings.

As part of the CCAA restructuring, the operating debtor company transfers undesirable assets and liabilities to the newly incorporated non-operating company. With its assets and liabilities selected by the purchaser, the debtor company holds only the desirable assets and liabilities, which means its common shares can be sold rather than the company’s assets. As a result, valuable permits, contracts, tax losses, and statutory authority are preserved, which can otherwise be lost in a disposition of assets.

Why is reverse vesting order important?

A reverse vesting order is an alternative to the traditional CCAA plans of arrangement, particularly for companies operating in highly regulated environments or when there is no value remaining after the realization of secured debt and the parties intend to continue the running of the debtor company.

A reverse vesting order is an alternative to the traditional CCAA plans of arrangement, particularly for companies operating in highly regulated environments or when there is no value remaining after the realization of secured debt and the parties plan to continue operating the debtor company.

By using a reverse vesting order, existing corporations, which have been streamlined to become solvent through an innovative solution, are transferred to new investors instead of desirable assets being sold through a court-approved sale. The debtor corporation that initially filed for bankruptcy protection under the CCAA can now be removed from the restructuring proceedings. There are certain unwanted assets and unwanted liabilities that are transferred to the newly incorporated residual corporation. There can then be asset sales allowing for some sort of distribution to creditors (either in a plan of arrangement or in bankruptcy) in order to allow some creditor recovery.

A reverse vesting order may prove to be the most efficient approach to facilitate a going concern operation transfer through restructuring proceedings, letting businesses emerge from CCAA proceedings quickly without having filed a plan of arrangement, while preserving key attributes of the corporate entity and its existing corporate structure.

Legal challenges to the use of reverse vesting orders have been unsuccessful. I would like to discuss the case of Nemaska Lithium Inc.reverse vesting order

Reverse vesting order issued by Québec Superior Court after first contested hearing

In December 2019, Nemaska Lithium Inc. and related companies (Nemaska Lithium or the Nemaska entities) commenced CCAA proceedings. A lithium mining project was developed in Quebec by them. A CCAA judge approved an uncontested sale or investment solicitation process (SISP) in January 2020 that led to the acceptance of a bid that was subject to the condition that a reverse vesting order is issued.

A proposed reverse vesting order provides that Nemaska entities will be acquired by the bidder free of the claims of the unsecured creditors, which will be transferred as part of a pre-closing reorganization to a newly incorporated non-operating company.

The reverse vesting order will allow the purchaser to continue to operate the Nemaska entities in a highly regulated environment by maintaining their existing permits, licences, authorizations, essential contracts, and fiscal attributes. In essence, it is a credit bid in which the shares of the Nemaska entities are acquired in exchange for the assumption of the secured debt.

A shareholder (who was also an alleged creditor) filed motions opposing the reverse vesting order issuance on multiple grounds, including:

  • a vesting order cannot be granted for anything other than a sale or disposition of assets through a vesting order for sales of assets;
  • the reverse vesting order is not permissible under the CCAA because it allows the Nemaska entities to exit CCAA protection outside of a plan of arrangement or plan of compromise;
  • this reverse vesting order contemplated a corporate reorganization that is not permitted by securities laws; and
  • in light of the proposed transaction, the directors and officers of Nemaska Lithium Inc. should not be released.

The Honourable Justice Gouin, J.S.C., reviewed and assessed:

  • the SISP process which led to the offer;
  • the lack of alternatives to the offer;
  • the potential harm to Nemaska Lithium‘s stakeholders, including its employees, creditors, suppliers, and the Cree community;
  • stopping the restructuring process to relaunch a SISP in the future following what was already a thorough examination of the market or, alternatively,
  • bankrupting the Nemaska entities.

In light of all these factors, the judge approved the reverse vesting order on October 15, 2020. Limiting the remedies available under the CCAA would unnecessarily hinder the development of innovative solutions for more complex commercial and social issues in Canadian insolvency matters.

The decision and formal recognition of reverse vesting order by the Court of Appeal

Leave to appeal the CCAA judge‘s decision was sought by the parties who objected to the reverse vesting order being made. The Appellate Court carefully considered the judge’s decision-making process and particularly that the Québec Superior Court judge relied extensively on the principles set out by the Supreme Court of Canada in the matter of 9354-9186 Quebec inc. c. Callidus Capital Corp., namely the:

  • development of CCAA proceedings and the role of the CCAA supervising judge;
  • remedial objectives of Canadian insolvency laws to provide timely, efficient, and impartial resolution of a debtor’s insolvency, secure fair and equitable treatment of creditors’ claims against a debtor, protect the public interest, and balance the costs and benefits of restructuring or liquidating the debtor company’s assets;
  • CCAA‘s goal of preventing social and economic losses from liquidating insolvent companies by facilitating their reorganization and survival as a going concern; and
  • CCAA judge‘s broad discretion under s. 11 of the CCAA in an effort to advance the CCAA’s remedial objectives while taking into account three fundamental factors that the debtor company application must prove: (1) the requested order is appropriate in the circumstances, and (2) good faith on the part of the applicant, and (3) the applicant has been acting with due diligence.

It was determined by the Court of Appeal judge that the risk of potential harm to stakeholders outweighed any legal merits of any arguments raised by the opposing parties. Therefore, the Quebec Court of Appeal denied the leave to appeal the decision of the CCAA judge.

Canada’s Supreme Court has denied leave to appeal. Having now established reverse vesting as an option for CCAA restructurings, the law is now set in stone.

The Nemaska case is the first reverse vesting order transaction to withstand judicial scrutiny in Canada and reaffirms the flexibility of CCAA proceedings for distressed M&A transactions of distressed businesses.reverse vesting order

Reverse vesting order and distressed M&A opportunities

I hope that you found this reverse vesting order Brandon Blog interesting. Problems will arise when you or your company are in business distress, cash-starved and cannot repay debts. There are several insolvency processes available to a company or a person with too much debt.

If you are concerned because you or your business are dealing with substantial debt challenges, you need debt help and you assume bankruptcy is your only option, call me.

It is not your fault that you remain in this way. You have actually been only shown the old ways to try to deal with financial issues. These old ways do not work anymore.

The Ira Smith Team utilizes new modern-day ways to get you out of your debt difficulties with debt relief options as alternatives to bankruptcy. We can get you the relief you need and so deserve. Our professional advice will create for you a personalized debt-free plan for you or your company during our no-cost initial consultation.

The tension put upon you is big. We know your discomfort factors. We will check out your entire situation and design a new approach that is as unique as you and your problems; financial and emotional. We will take the weight off of your shoulders and blow away the dark cloud hanging over you. We will design a debt settlement strategy for you. We know that we can help you now.

We understand that people with credit cards maxed out and businesses facing financial issues need a realistic lifeline. There is no “one solution fits all” method with the Ira Smith Team. Not everyone has to file bankruptcy in Canada. The majority of our clients never do as we know the alternatives to bankruptcy. We help many people and companies stay clear of filing an assignment in bankruptcy.

That is why we can establish a new restructuring procedure for paying down debt that will be built just for you. It will be as one-of-a-kind as the economic issues and discomfort you are encountering. If any one of these seems familiar to you and you are serious about getting the solution you need to become debt-free, contact the Ira Smith Trustee & Receiver Inc. group today.

Call us now for a no-cost consultation.

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic.

Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

Categories
Brandon Blog Post

EARNOUT DEALS AND INSOLVENCY: THE BOLD WAY THEY NEED TO INTERSECT DUE TO TORONTO CORONAVIRUS

earnout
earnout

The Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.

If you would like to listen to the audio version of this Brandon’s Blog, please scroll to the bottom and click on the podcast.

Earnout introduction

Our firm has recently started consulting with a business that has been deeply negatively affected by the Toronto coronavirus. I cannot tell you what it is, but I can confirm it is not in the food and beverage industry. Their cash flow budget shows they are going to soon run out of cash. That is bad news. The good news is that they are being courted by a company that wants to acquire them. The purchaser is proposing to pay a certain amount of cash on closing with an earnout deal as an upside.

The question they asked us, and the retainer that we will get, is to review the various options available to the target company. They want recommendations in case an insolvency process must be used to get either a refinancing deal with their banker or the sale completed.

We have had a very high-level discussion so far. It was immediately obvious to me that an insolvency process was not just a potential, it was a necessity. Not because the target company is going to crater tomorrow. Rather, for a different reason.

The business is currently viable but insolvent. That is the perfect combination in order to do a debt settlement plan combined with a corporate debt restructuring. My initial impression was that we can enhance either the refinancing or the sale by doing a corporate restructuring of debt.

Such a combination will enhance either option because:

  • In a refinancing, the restructuring will allow for a finite amount of money to go towards discharging all of the company’s unsecured debt, with the majority going to future operations.
  • For the sale, the purchaser will not be taking on many liabilities which will allow for a higher negotiated selling price.

You might think that the purpose of this Brandon’s blog is to focus on corporate restructuring, but it isn’t. Rather I want to focus on giving a basic primer on earnout deals.

What is an earnout structure?

An earnout structure is the combination of all the components which add up to the negotiated earnout sales agreement (merger agreement or earnout agreement). These elements consist of the purchase price, monetary and/or operating targets to be met or exceeded, upfront payment, as well as contingent payment.

The framework of the earnout agreement will have the earnout formula spelled out. The formula and full arrangement will be described in the particular clauses within the earnout agreement

Earnout clauses are part of the legal contract between the seller and the buyer. They normally contain 7 essential elements in the merger agreement: (1) overall acquisition price (2) the amount to be paid on closing (3) what the total potential additional purchase price contingent payment is based on the earnout formula (4) the length of time that the earnout deal applies for (earnout period) (5) what the financial and operational targets are (6) how the performance will be measured, and (7) the earnout cash payment formula and time frame each measurement period to make the calculated payment.

Why agree to an earnout arrangement?

When the buyer and seller have a difference of opinion on what the purchase/sale price should be, earnout clauses can bridge that void. It is a way to attempt to negotiate a deal that will be a win for both parties.

A remedy can be found through earnout payments. The buyer agrees to a purchase price which includes both a set payment on closing and a variable amount over a defined amount of time. It is computed depending upon the future growth of the target business. The earnout payments come to be due if the targets (both in performance and time frame) are met by the target business.

How does an earnout work?

As indicated above, there is an earnout formula in the agreement of purchase and sale. The earnout formula will be based on certain milestones being met in the future over the earnout period. Examples of earnout milestones can include on or more of:

  • sales revenue of brand-new modern technologies or products;
  • certain accomplishments with a predefined client base;
  • meeting or exceeding specific key financial results; and/or
  • hitting a minimum level of financial performance measured by earnings before interest, taxes, depreciation, and amortization (EBITDA).

It is not uncommon in earnouts in m&a transactions, if the targets are not met, the seller gets absolutely nothing. This is notwithstanding there may have been performance improvement. That is because the target business did not meet the defined milestones. When putting together an earnout agreement, very close attention must be paid to both the computation and the definitions in the earnout clauses for the earnout payments. The parties must ensure that the language is as clear as it can be. If not, then disputes and probable litigation will be inescapable.

earnout
earnout

Earnout milestones and the good faith of the parties

When looking at any contract, there is a basic question. Does Canadian legislation place a duty on parties to a contract to carry out those duties honestly and in good faith? Must there be fair dealing between the parties? I believe the leading case on this topic is the decision of the Supreme Court of Canada (SCC) in Bhasin v. Hrynew, 2014 SCC 71, [2014] 3 S.C.R. 494.

The answer to that question, as decided in that case, was yes. There must be fair dealing.

Nonetheless, in doing so, the SCC stated that the buyer does not act in the capacity as a fiduciary for the seller. The court also stated that there is nothing to prevent one party to legitimately obtain an economic benefit from the merger agreement over the other. The court was not asked to, and therefore did not, express any views on if a party goes out to frustrate or prevent a milestone from being met, does that constitute bad faith? It obviously won’t be fair dealing, but the court did not opine on the issue.

Earnout and Toronto coronavirus

The coronavirus pandemic has created so much uncertainty in all of our lives. The economy is just one of them. It has created a financial crisis for many. Entrepreneurs who had prepared to put their company up for sale in 2020 have been thrown a curveball. Buyers are of course looking to take advantage of the current financial crisis conditions to pay less for a viable business than they would have just 9 or 10 months ago. Sellers want to value their business on a historical average basis so that when the coronavirus financial crisis is over and the economy returns to normal, they will be fairly compensated. Buyers are looking for an advantage based on today’s economic realities.

An earnout clause may just be the way to bridge the gap. Perhaps both an earnout and a reverse earnout may be a way to go. The business gets valued on a historical average basis, but part of the purchase price is held in escrow invested. Over the agreed-upon earnout period, if the milestones are reached, including getting back to historical average earnings, then the earnout is paid out, in whole or part, to the seller. If not, the invested escrow funds are returned to the buyer.

Earnout deals and insolvency

In the current situation, we are being retained on, the viable but insolvent company has too much unsecured debt. Nobody is going to offer them new financing in order to pay off old debts. Financing is realistically available for go-forward expenses only.

The potential purchaser is not going to agree to assume the unsecured debt. The purchaser wants to buy assets of the target business, not the shares. They are going to want to make sure that if they purchase the assets, unsecured liabilities are not going to tag along. They will not want to just rely on common law. They are going to want a court order authorizing the purchase and getting proper title through a vesting order.

An insolvency process will accomplish both. It will be a debt settlement corporate restructuring. The merger agreement or earnout agreement will give both the seller and buyer certainty. The process will be conducted under either the proposal provisions of the Bankruptcy and Insolvency Act (Canada) (BIA) or under the Companies’ Creditors Arrangement Act (Canada) (CCAA).

A portion of the purchase price will be held back and used to create a proposal fund to offer a settlement to the unsecured creditors. If the sale does not take place and the company goes into bankruptcy, our current assessment is that the unsecured creditors will receive nothing. So, an offer through a restructuring plan to the unsecured creditors will get them a better result than in the bankruptcy of the company.

With a willing buyer and seller, both in fair dealing with each other to get an agreement of purchase and sale done, I am certain that we will get the debt settlement corporate restructuring done.

Earnout summary

I hope you have enjoyed this earnout deals and insolvency Brandon’s Blog. Hopefully, you have better insight now into the fact that a sick insolvent company’s business can be saved by doing a sale of its assets to a healthy organization.

Do you or your company have too much debt? Are you or your company in need of financial restructuring? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or the person who has too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding bankruptcy. We can get you debt relief freedom.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a debt settlement plan, we know that we can help you.

We know that people facing financial problems need realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team.

That is why we can develop a restructuring process as unique as the financial problems and pain you are facing. If any of this sounds familiar to you and you are serious in finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation.

We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.

Call a Trustee Now!