Categories
Brandon Blog Post

Debtor in Possession in Canada: Which Restructuring Route Keeps Your Company Actually in Control?

I hope you and your business are safe and well. If your company is facing creditor pressure, falling cash flow, or uncertainty about whether it can keep operating, choosing a restructuring route can feel like another major risk. You don’t have to make this decision in the dark. I help directors compare the available paths against their company’s viability, creditor landscape and immediate needs.

The question owners ask me most often is not about statutes. It is about control: if we do this, do we still run our own company? That is what debtor in possession means, and in Canada the answer depends entirely on which route you choose. A debtor in possession is a company that keeps possession of its assets and continues operating the business while it restructures under court or statutory protection, rather than handing control to a receiver or a bankruptcy trustee.

Debtor in Possession Key Takeaways

  • Start with viability: A Division I Proposal or CCAA process needs a credible plan for a viable or partly viable business, not simply a pause in collections.
  • A debtor in possession keeps its assets and continues running the business during restructuring. In Canada, both a Division I Proposal and a CCAA filing generally leave the company in possession; receivership and bankruptcy do not.
  • DIP financing (debtor in possession financing) is new money advanced to a company while it restructures. Under the CCAA, the court can approve interim financing and grant the lender a charge over company assets, sometimes ahead of existing security.
  • A Division I Proposal under Part III, Division I of the Bankruptcy and Insolvency Act (BIA) is often a practical formal route for small and mid-sized Ontario companies. It has no statutory minimum debt threshold.
  • The Companies’ Creditors Arrangement Act (CCAA) generally applies when claims against a company, or affiliated companies, are more than $5 million.
  • A Division I Proposal is filed through a Licensed Insolvency Trustee (LIT); a CCAA case is court-supervised and requires a court-appointed monitor.
  • Cost, time, secured-creditor support, the number of creditor groups, leases, CRA obligations, financing needs and cross-border issues can matter in a debtor in possession restructuring as much as the total debt.
  • An unsuccessful Division I Proposal normally results in the debtor in possession restructuring being turned into a deemed assignment in bankruptcy administration now controlled by the Licensed Insolvency Trustee and not the debtor. Directors should understand that risk before filing.

Debtor In Possession Highlights

Should viability come before choosing a formal process?

Yes. The first question is not “Which statute should we use?” It is “Is there a fundable plan?”

A viable business is one that can reasonably continue operating if its financial difficulties are addressed. It may need a smaller footprint, new financing, revised payment terms, a sale process or a compromise with creditors. But there must be a credible route from today’s cash position to sustainable operations.

In my first meeting with directors, I ask: “If the company had breathing room from its legacy debt, could it operate and generate enough cash to support a realistic restructuring?” We then test that answer against weekly cash flow, current obligations, customers, suppliers, financing, and the company’s actual operating needs.

A stay of proceedings, a legal pause on certain creditor actions, can buy time. It does not create revenue, restore supplier confidence, or fund payroll. The company still needs to meet obligations incurred after filing and, where relevant, maintain critical supplies and operations.

If the numbers do not support a plan, a formal restructuring will be unsuccessful and will only postpone a necessary sale or wind-down while adding expense. If they do support a plan, choosing the right process can be a lifeline: it may give the company time and structure to pursue a genuine turnaround.

What does debtor in possession mean in Canada?

Canada has no equivalent of the American Chapter 11 filing. There is no single “debtor in possession” statute here. What Canada has instead is a set of restructuring routes that either leave the company in possession of its business or take that possession away.

Under a Division I Proposal and under the CCAA, the company generally remains a debtor in possession. Management continues to run operations, subject to the statutory duties of the proposal process and, in a CCAA case, subject to court orders and the oversight of a court-appointed monitor. A monitor reports to the court; a monitor does not take over the business the way a receiver does. That distinction is the whole point of the phrase, and it is the distinction owners care about most.

The alternative routes are different. In a receivership, a receiver takes control of specified property or operations, and the company is no longer the party in possession of what the receiver controls. In a bankruptcy, the trustee administers the estate, and the corporation does not continue as the same operating entity. So when a director asks “do we keep control?”, the honest answer is that control is not a reward for choosing a particular statute. It is a feature of the route, and it comes with conditions attached.

Why does the phrase matter so much in practice? Because possession is what lets a company keep customers, suppliers and employees. A business that loses possession in the middle of a restructuring usually loses its operating momentum too. The value being preserved is often the going concern itself, and possession is how that value stays intact.

It also matters to lenders. A company that remains in possession still needs cash, and the willingness of a secured lender to keep supporting the business often turns on whether it trusts management to operate through the process. Possession without financing is a short-lived advantage.

What is a Division I Proposal?

A Division I Proposal is a formal compromise or arrangement with creditors under Part III, Division I of the BIA. A corporation files its proposal through an LIT, who helps administer the process and carries out statutory duties. A proposal can offer affected creditors revised payments or other terms; its design depends on the company’s circumstances and must be developed with professional advice.

The company remains a debtor in possession throughout. Management keeps operating the business while the LIT administers the statutory process, and the directors remain in place. That is one reason the proposal route suits owner-managed Ontario companies: the people who know the business keep running it, subject to the terms of the proposal and the oversight built into the BIA.

There is no minimum debt amount in the BIA that a company must owe to use this route. That makes a proposal a common formal option for small and mid-sized Ontario companies that need a structured process, but may not need the scale and court involvement of a CCAA case.

A company may first file a Notice of Intention (NOI) under BIA section 50.4. The NOI triggers the stay in BIA section 69(1), subject to statutory limits and exceptions. The company has an initial 30 days to file a proposal, although the court may grant extensions within statutory limits. The NOI is not itself the proposal.

Once the proposal is filed, BIA section 69.1 provides a separate stay, again subject to exceptions and court orders. These protections can restrain certain creditor proceedings and enforcement steps, but they are not a blanket answer to every creditor or every legal right. Directors need advice on the specific security, claim and enforcement circumstances.

Creditor acceptance and court approval are both required. Under BIA section 54, unsecured creditors vote by class. In the applicable unsecured creditor class or classes, acceptance requires a majority in number and two-thirds in value of the creditors present, personally or by proxy, and voting, in each unsecured creditor class. There can be one or more than one such class. It all depends on the circumstances of the individual insolvency restructuring case. A court must then approve, or sanction, the proposal. Secured creditors’ rights and votes are addressed separately under the BIA; an unsecured vote alone does not rewrite a secured creditor’s rights.

The consequence of failure is important. If creditors reject the proposal, or the court refuses approval, the debtor is automatically deemed to have made an assignment in bankruptcy. An NOI also has statutory deadlines, and failing to comply with them can trigger a deemed assignment. This is not a filing to use casually or without a credible financing and voting plan.

What is a CCAA restructuring?

The CCAA is a court-supervised restructuring statute designed for a debtor company seeking a compromise or arrangement with creditors. The statutory threshold is more than $5 million in claims against the debtor company or affiliated debtor companies, determined under section 20 of the Act. The wording of section 3(1) of the CCAA states that the Act applies to companies having “more than $5,000,000,” not simply $5 million or more. Affiliated company claims may count together.

When the court makes an initial order, it appoints a monitor. A licensed trustee who reviews and reports on the company’s financial affairs and the restructuring process. The court may also grant a stay of proceedings, generally for no more than 10 days on the initial application; further relief requires a court order. The order’s terms and any later extensions matter.

The CCAA offers broad court supervision and flexibility, and the company generally remains a debtor in possession while it uses that flexibility. For example, a company may ask the court to approve DIP financing: debtor-in-possession financing, new funding advanced during the restructuring. Under section 11.2 of the CCAA, the court may make an order for interim financing and authorize a charge on the company’s property to secure it, potentially with priority over existing security, subject to the statutory conditions, notice requirements and the court’s assessment of the company’s circumstances. This can be useful where the business is viable but cannot operate through a restructuring without new cash.

DIP financing is where the phrase “debtor in possession” earns its keep commercially. A lender advancing money to an insolvent company wants to know its money will be secured and that it ranks properly. The court’s charge gives it that comfort. Without it, many viable companies would simply run out of cash before a plan could be presented. With it, the company keeps possession and keeps operating, but the new debt sits on the assets and must be repaid.

Creditor voting takes place in classes. Class structure must be approved by the court. Under section 6, acceptance generally requires a majority in number representing two-thirds in value of creditors present and voting in each relevant class, followed by court sanction. Employee and pension obligations are also governed by statutory protections and should be assessed from the outset.

A company may have cross-border complications, for example, an active restructuring or substantial assets and operations in another country. Part IV of the CCAA provides a framework for recognition and cooperation involving foreign insolvency proceedings. The available route and relief depend on the facts, court orders and relevant jurisdictions.

The CCAA is often suited to larger, more complex restructurings, including those involving multiple creditor classes, extensive leases, litigation, cross-border matters or a need for court-approved interim financing. That flexibility comes with more process, professional involvement and expense.

How should directors compare the available routes?

The debt threshold is a useful first screen, not a final answer. I usually focus on the practical questions below.

A professional decision-fork visual showing two distinct restructuring paths for a company considering a debtor in possession restructuring plan

  • How much debt is involved, and how is it counted? A company near the CCAA threshold needs a careful claims analysis, including possible affiliated-company claims. A Division I Proposal has no comparable minimum debt level.
  • How many creditor groups need separate treatment? A concentrated unsecured creditor group may be easier to address through a proposal. Different classes of secured creditors, bondholders, landlords, pension stakeholders or litigants may call for a more tailored court-supervised framework.
  • Does the company need to stay a debtor in possession, and can it fund that? If keeping control is essential, a proposal or a CCAA filing usually fits better than a receivership. But possession still has to be paid for: payroll, suppliers and rent continue, and DIP financing may be needed to bridge the process.
  • What does the business need the process to do? Does it need a stay quickly? Does it need DIP financing, court directions, a sale process or the ability to address agreements? The proper approach depends on specific statutory powers and the court’s orders.
  • Will secured creditors support the plan? Their support can be central to continued operations, especially if the company needs new or continuing credit. The fact that creditor-initiated CCAA proceedings have drawn attention is one consideration, not a reason by itself to choose CCAA. I discussed that development in “The Debtor Loses The Driver’s Seat: The Rise of Creditor-Launched CCAA Proceedings”. For this decision, the practical question is whether the company has the creditor support and financing needed for a workable plan.
  • What is the cost trajectory? CCAA proceedings are typically more expensive because of court time, monitor fees, and company and stakeholder legal and financial advisers. A proposal has costs too, but may be more proportionate for a smaller company with a simpler creditor structure. Costs vary substantially with contested issues, duration and work required.
  • What are the employee, lease and CRA pressures? Identify payroll, employee source deductions, pension contributions and rent arrears promptly. Statutory claims and payment requirements may affect what a plan can do. Do not assume a stay removes the need to remit current payroll deductions or pay for ongoing services.
  • Are there cross-border needs? If a restructuring or assets span jurisdictions, ask counsel whether recognition, coordination or related court relief is needed. The CCAA’s Part IV framework may be relevant, but it does not make every international issue automatic.

What owners are often surprised to learn is that the route is not simply “small debt means proposal, large debt means CCAA.” Complexity, timing, cash and creditor dynamics can change the analysis. The right process is the one that gives a credible plan the legal tools it needs without burdening the company with unnecessary expense.

How do the routes compare?

The table is a starting point, not a substitute for advice on a particular corporation, its debt and security documents, or creditor rights.

Decision pointDivision I ProposalCCAAInformal workoutReceivershipTypical fitMain caution
What it isFormal BIA compromise with creditorsCourt-supervised compromise or arrangementPrivate negotiated changes to debt or payment termsAppointment of a receiver to take control of specified property or the businessRestructuring a business that can continueA process cannot make an unviable business viable
Who initiatesUsually the insolvent company, filing through an LITCompany or, in appropriate circumstances, another interested applicant seeking court reliefCompany and participating creditors by agreementOften a secured creditor under its rights or a court orderA business able to negotiate or propose a planThe company may not control the timing of enforcement or court action
Debt thresholdNo statutory minimum debt thresholdClaims must generally be more than $5 million; affiliated-company claims may count togetherNo statutory thresholdNo CCAA thresholdA proposal for many small and mid-sized firmsConfirm threshold and eligibility before planning a CCAA filing
Debtor in possession?Yes. Management continues to operate; the LIT administers the proposalYes. Company remains in possession, subject to court orders and monitor oversight; DIP financing may be availableYes, but only as far as each creditor has agreed; no statutory stay by agreement aloneNo. The receiver controls the assets or operations within the appointment’s scopeA company able to manage its business during restructuringFormal court supervision does not mean management has unrestricted control
Creditor approval requiredUnsecured creditors vote by class; statutory majority-in-number and two-thirds-in-value test; court approval followsMajority in number and two-thirds in value in each class present and voting; court sanction followsAgreement of participating creditors; no binding collective compromise without applicable legal processNot a creditor vote on a plan; rights depend on appointment, security and court ordersA plan with sufficient creditor supportVoting thresholds and affected creditor classes require careful review
Typical costModerate relative to CCAA, but case-specificTypically higher: monitor, court, legal and financial adviser costsOften lower initially; negotiation and documentation still cost moneyPaid from assets or as ordered; scope and duration drive costA process proportionate to the company’s available cash and complexityLow upfront expense can be offset by delay or creditor action
Main riskRejection, refusal of court approval or missed deadline may lead to deemed bankruptcyExpense and procedural complexity may overwhelm the available valueNo automatic stay; a non-participating creditor may enforce rightsLoss of management control; sale or realization may be the outcomePreserving value and a going concern where possibleA mismatch between route and business needs can destroy time, cash and options

Scroll the table sideways to see every column. General information only. The appropriate route depends on the company’s facts, assets, liabilities, financing and creditors.

What are the risks of choosing the wrong route?

A Division I Proposal can be a poor fit if the company needs extensive court directions, complex creditor-class treatment, interim financing or a coordinated sale process that exceeds what the proposal structure can practically deliver. The proposal route also carries a serious failure consequence: rejection, refusal of court approval or missed statutory deadlines may result in a deemed assignment in bankruptcy.

On the other hand, putting CCAA-scale costs on a small company can consume the cash needed to keep the business operating. A formal route is not automatically better because it offers broader court supervision. The company needs to be able to fund its professional costs and ongoing operations while the process proceeds.

An informal workout may avoid some formal-process costs, but it does not automatically stay a creditor from enforcing its rights. Receivership is generally focused on a receiver’s control and realization of assets, rather than a debtor-led compromise. In some situations, a sale, receivership or orderly wind-down may preserve more value than a restructuring attempt.

The objective is not to choose the most impressive legal mechanism. It is to find a process that fits the company’s viability, financing, creditors and operating realities. Before avoidable choices narrow the remaining options.

What should directors do in the first 30 days?

The right work depends on urgency; an enforcement deadline can make the next 30 days much shorter. Still, this checklist helps directors build a clearer picture and make informed decisions.

  1. Build a reliable cash picture. Prepare a short-term, preferably weekly, cash-flow forecast. Identify the cash needed for payroll, suppliers, rent, utilities and tax remittances.
  2. Reconcile debt and claims. List creditors, balances, arrears, guarantees, security, litigation, leases and any disputed amounts. Note related or affiliated entities.
  3. Assess the business plan. Separate profitable products, customers and locations from loss-making activities. Test the assumptions behind proposed savings, revenue and new financing.
  4. Protect records and governance. Preserve accounting records, contracts, board minutes and communications. Hold properly documented board discussions and obtain legal advice on directors’ duties and personal exposure.
  5. Map creditor pressure. Record collection demands, enforcement notices, loan covenant concerns, supplier restrictions and any key creditor negotiations. Do not assume an informal discussion pauses legal rights.
  6. Identify sensitive obligations. Review employee pay, payroll deductions, source deductions, pension contributions, rent and ongoing supply costs. Continuing obligations deserve immediate attention.
  7. Speak with an LIT and restructuring counsel. Ask them to compare a Division I Proposal, CCAA, workout, sale or other available route against the company’s facts. Involve accounting and financial advisers as appropriate.
  8. Set decision points and funding. Determine how much cash is required to reach the next milestone, what support may be available, and what the board will do if the plan misses its targets.

A methodical first month will not remove every risk, but it can reduce confusion and help preserve options. That clarity matters to the company, its creditors, employees and the directors making difficult decisions.Company directors sitting in the Ira Smith Trustee & Receiver Inc. boardroom with a licensed insolvency trustee going over the debtor in possession restructuring plan.
What are common Frequently Asked Questions (FAQ) about Division I Proposals and CCAA?

What is a debtor in possession in Canada?

A debtor in possession is a company that keeps its assets and continues operating while it restructures under protection. In Canada, a company filing a Division I Proposal or a CCAA proceeding generally remains in possession. A receivership or a bankruptcy takes possession away, because the receiver or trustee takes control of the assets in question.

Is there a Chapter 11 equivalent in Canada?

Not as such. Canada has no single debtor-in-possession statute matching Chapter 11. The closest functional equivalents are the CCAA and, for smaller companies, a Division I Proposal. Both generally leave management in place, but each has its own threshold, process and creditor-voting rules.

What is DIP financing, and can my Ontario company get it?

DIP financing is debtor-in-possession financing: new money advanced to a company while it restructures. Under the CCAA, the court can authorize interim financing and grant the lender a charge over company assets, sometimes ahead of existing security. Whether it is available depends on the lender’s assessment, the company’s prospects and what the court will approve. It is not automatic, and it is not free money: the new debt ranks against the assets.

What is the difference between a Division I Proposal and a CCAA filing?

A Division I Proposal is made under Part III, Division I of the BIA and filed through an LIT. A CCAA restructuring is a court-supervised process with a monitor and a stay granted by court order. The CCAA is generally intended for companies with claims exceeding $5 million and more complex restructurings.

What is the $5 million threshold in the CCAA?

Section 3 of the CCAA generally requires total claims of more than $5 million against the debtor company or affiliated debtor companies. Claims are determined under section 20. It is not simply a test of one company’s headline debt balance.

Can a company with less than $5 million in debt use the CCAA?

A company must meet the CCAA’s statutory threshold to use the Act. Because affiliated-company claims may be aggregated, a company with less than $5 million in its own debt should obtain advice before assuming it is ineligible. A Division I Proposal has no minimum debt threshold.

What happens if creditors reject a Division I Proposal?

If creditors reject the proposal, the debtor is deemed to have made an assignment in bankruptcy. A court’s refusal to approve the proposal has a similar consequence. The company should understand the voting prospects and potential outcomes before filing.

Who controls the company during a proposal or CCAA?

Under a Division I Proposal, management continues running the company while the LIT administers the process. In a CCAA case, management remains in place, but the monitor oversees and reports on the company’s financial affairs, and the court’s orders may limit management’s decisions. A monitor is not the same as a receiver. Unless the court orders otherwise, the Licensed Insolvency Trustee is not making any management decisions or exerting control in a debtor in possession restructuring.

Does filing a proposal or CCAA stop CRA collections?

A statutory stay may restrict certain collection steps, but its scope, exceptions and timing matter. Under the CCAA, the court may make an order addressing certain federal and provincial Crown collection rights, subject to statutory conditions. Neither process should be treated as a reason to stop current payroll remittances or ignore tax obligations. Obtain advice specific to the company.

How long does each process take?

There is no single timetable. A Division I Proposal has statutory deadlines, including the initial NOI period, with possible extensions subject to the BIA. CCAA timing depends on the court’s calendar and orders, the restructuring steps, creditor negotiations and any sale or litigation process. Management in a debtor in possession restructuring will be making changes to business systems and practices, which takes time. Creditor meetings and court approval add further milestones. Ask advisers to map a realistic timeline for the actual case.

What does each route cost?

Costs depend on the company’s size, records, creditor disputes, financing needs, court activity and process length. A debtor in possession CCAA case is typically more expensive because it involves a monitor, court hearings and professional advisers. A Division I Proposal may be more proportionate for a simpler restructuring, but there is no universal fee. Request a case-specific budget, including ongoing operations and professional costs.

Sources and further reading

Starting Over, Starting Now

Don’t let financial uncertainty dictate your company’s future. If your business is struggling with debt, you are losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and move towards a sustainable outcome.

Take the first step towards a brighter financial future; call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

Disclaimer: This debtor in possession analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:
Ira Smith is President of Ira Smith Trustee & Receiver Inc., a CPA CA and Licensed Insolvency Trustee serving the Greater Toronto Area. Ira works with business owners and directors facing financial distress, helping them assess debtor in possession restructuring options and make practical decisions about their companies’ futures.

Ontario business director reviewing restructuring documents with a Licensed Insolvency Trustee in a bright, professional boardroom considering the debtor in possession restructuring plan

#DebtorInPossession #DIPFinancing #DivisionIProposal #CCAA #CorporateRestructuring #OntarioBusiness #OntarioBusinessInsolvency #LicensedInsolvencyTrustee #BusinessRestructuring #GTA
Categories
Brandon Blog Post

The Debtor Loses The Driver’s Seat: The Rise of Creditor-Launched CCAA Proceedings

Corporate steering wheel symbolizing control in CCAA proceedings of the debtor company.

The Debtor Introduction

At Ira Smith Trustee & Receiver Inc., we hope you are doing well and staying safe in these rapidly changing economic times. We know that the weight of corporate financial distress doesn’t just sit on a balance sheet; it sits on the shoulders of the people, the directors of the debtor company, investors, and creditors, who make these businesses run. We are here to help you navigate these complex waters with clarity and compassion.

The Debtor Key Takeaways

  • The Power Shift: 2026 has seen a definitive shift toward creditor-led and investor-led CCAA proceedings, moving away from the traditional model where the debtor company calls all the shots.
  • The Angus A2A GP Inc v Alvarez & Marsal Canada Inc, 2026 ABCA 156 (CanLII) Decision: A landmark Alberta Court of Appeal ruling in May 2026 has officially cleared the way for equity investors to qualify as “interested persons” under the Companies’ Creditors Arrangement Act (CCAA) to initiate restructuring proceedings, fundamentally changing the “who” and “how” of corporate rescue.
  • Super-Monitors: Courts are increasingly granting Monitors enhanced operational powers, creating a “Super-Monitor” role that provides receivership-level control within a CCAA framework.
  • Reverse Vesting Orders (RVOs): While under higher judicial scrutiny, RVOs remain the “surgical tool” of choice for preserving tax attributes and regulatory licences.
  • Restructuring at Scale: Speed is the new currency. The use of “SISPs-on-steroids” ensures that businesses are moved through the market in weeks rather than months.

For decades, the CCAA was seen as the debtor-in-possession regime. The company in trouble would realize it was sinking, seek court protection, and then propose a plan to its creditors. But as we move through the middle of 2026, that landscape has shifted. We are now seeing creditors, and even equity investors, seizing the wheel.

Whether you are a secured lender in the GTA or an investor looking to protect a failing portfolio company, understanding this “Creditor-Led” era is essential. It’s no longer just about waiting for a proposal; it’s about taking proactive steps to preserve value.


The Debtor Highlights

  • The Angus Manor Decision: A Game Changer
  • The Rise of the “Super-Monitor”
  • RVOs: Surgical Precision or Extraordinary Relief?
  • SISPs-on-Steroids: The Need for Speed in 2026
  • BIA vs. CCAA: A Strategic Comparison for Creditors

The Angus Manor Decision: Why Equity Investors are Now at the Table

In May 2026, the Alberta Court of Appeal released its decision in Angus Manor, a case that has sent ripples through the Canadian insolvency community. Historically, the right to file for CCAA protection was largely the domain of the debtor company itself or its creditors. Equity investors were often sidelined until a plan was actually on the table.

The Angus Manor ruling changed that. The court determined that, in specific circumstances, where management is deadlocked or the board is failing to act in the face of imminent insolvency, equity investors can have the standing to initiate CCAA proceedings.

As a Licensed Insolvency Trustee Toronto, we see this as a vital evolution. It prevents a “burn-down” scenario in which a debtor company’s value evaporates while its leadership is paralyzed. For GTA business owners and stakeholders, this means you have a new lever to pull if your investment is at risk.


The Rise of the “Super-Monitor” Overseeing The Debtor

Professional trustee overseeing complex business restructuring of the debtor company.

Traditionally, a Monitor in a CCAA proceeding is a court-appointed officer (a Licensed Insolvency Trustee) who watches over the debtor company’s finances, assists in formulating the restructuring plan, interfaces with creditors and reports to the court. They are the “eyes and ears” of the judge.

However, in 2026, we are seeing the rise of the Super-Monitor. In many creditor-led filings, the court is granting the Monitor “enhanced powers.” This means the Monitor isn’t just watching; they are often:

  • Approving all major expenditures.
  • Directing the sale process (the SISP).
  • Even overriding the management of the debtor company on key strategic decisions.

This creates a hybrid between a CCAA and a corporate receivership process for GTA creditors. It provides the legal “stay of proceedings” (the freeze on lawsuits) that CCAA offers, but with the tight, professional control of a receiver. If you are a creditor who has lost faith in a company’s management, the Super-Monitor is your best friend.


The Debtor and RVOs: The Surgical Tool under Fire

A corporate shell being cleaned of liabilities through an RVO of the debtor company.

One of the most powerful tools in our 2026 toolkit is the Reverse Vesting Order (RVO). If a regular sale is like selling a car and leaving the debt behind, an RVO is like keeping the car’s registration and history but magically removing the debt from the title.

In an RVO, the purchaser buys the shares of the company. The “bad” parts, the debts and unwanted contracts, are “vested out” into a separate, temporary company that eventually goes bankrupt. This is incredibly useful for companies with complex regulatory licences or tax attributes (like losses that can be carried forward) that would be lost in a traditional asset sale.

However, the courts are becoming more cautious. In 2026, judges are demanding clear evidence that an RVO is necessary and not just a “convenient shortcut” to avoid taxes or environmental liabilities. At Ira Smith Trustee & Receiver Inc., we ensure that any RVO proposal is backed by a rock-solid evidentiary record to stand up to judicial scrutiny.


SISPs-on-Steroids: The Need for Speed

A stopwatch on legal documents symbolizing the urgency of modern SISPs in reorganizing the debtor company.

The days of long, drawn-out restructuring processes are largely over. In 2026, we utilize what we call “SISPs-on-steroids.” A Sale and Investment Solicitation Process (SISP) is the formal way we market the assets of the debtor company, either in pieces or en masse, representing the operating business for sale during insolvency.

Why the rush? Because in a high-interest, volatile market, “time is the enemy of value.” The longer a company stays in CCAA, the more “professional fees” it burns and the more customers it loses. We are now seeing SISPs that launch, market, and close a sale in as little as 45 days. This requires a team that can move fast, with a deep network in the Toronto and Canadian investment communities.


BIA vs. CCAA: A Strategic Comparison for Creditors

When deciding how to handle a distressed company in the GTA, creditors often weigh the Bankruptcy and Insolvency Act (BIA) against the CCAA. Here is how they compare in the current 2026 environment:

FeatureBIA (Receivership/Proposal)CCAA (Restructuring)
Primary GoalLiquidation or debt settlement.Going-concern restructuring or sale.
ControlHigh (Receiver takes over).Traditionally low, but high with “Super-Monitor.”
ComplexityLower; rules-based.Higher; flexible and court-driven.
CostGenerally more affordable for SMEs.Significant; usually for debts over $5 million.
SpeedCan be very fast (liquidation).Fast in 2026 (SISPs-on-steroids).
Shareholder RightsMinimal.Emerging rights (see Angus Manor).

The Debtor Frequently Asked Questions (FAQ)

1. Can a creditor force a company into CCAA in Ontario?

Yes. While it is more common for the company to file voluntarily, a creditor with a significant claim (over $5 million) can apply to the court to have the debtor company placed into CCAA protection if the company is insolvent.

2. What is the difference between a Receiver and a Super-Monitor?

A Receiver generally takes full possession and control of the assets to sell them. A Super-Monitor works alongside or over management within the CCAA process, often allowing the debtor company to keep operating while a sale is finalized.

RVOs are popular because they preserve “intangible” value. If a company has a specific licence to operate in a regulated industry (like cannabis, pharma, or energy), an RVO allows that licence to stay with the corporate entity while the debt is stripped away.

4. How does the Angus Manor decision affect me as a business owner?

It means your investors have a new “safety valve.” If your board is deadlocked and the business is failing, a shareholder investor might be able to go to court to start a restructuring, even if the board doesn’t agree.


Why This Matters to You and The Debtor Company

Understanding these shifts isn’t just for lawyers and bankers. It’s for the business owner who is worried about their legacy, the investor trying to save a portfolio, and the creditor trying to recover what they are owed.

At Ira Smith Trustee & Receiver Inc., we don’t just see numbers; we see the “Starting Over, Starting Now” potential in every crisis. By staying at the cutting edge of BIA vs CCAA proceedings Toronto, we give our clients the best possible chance to emerge from financial distress with their dignity and their future intact.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future. Call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Brandon stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.

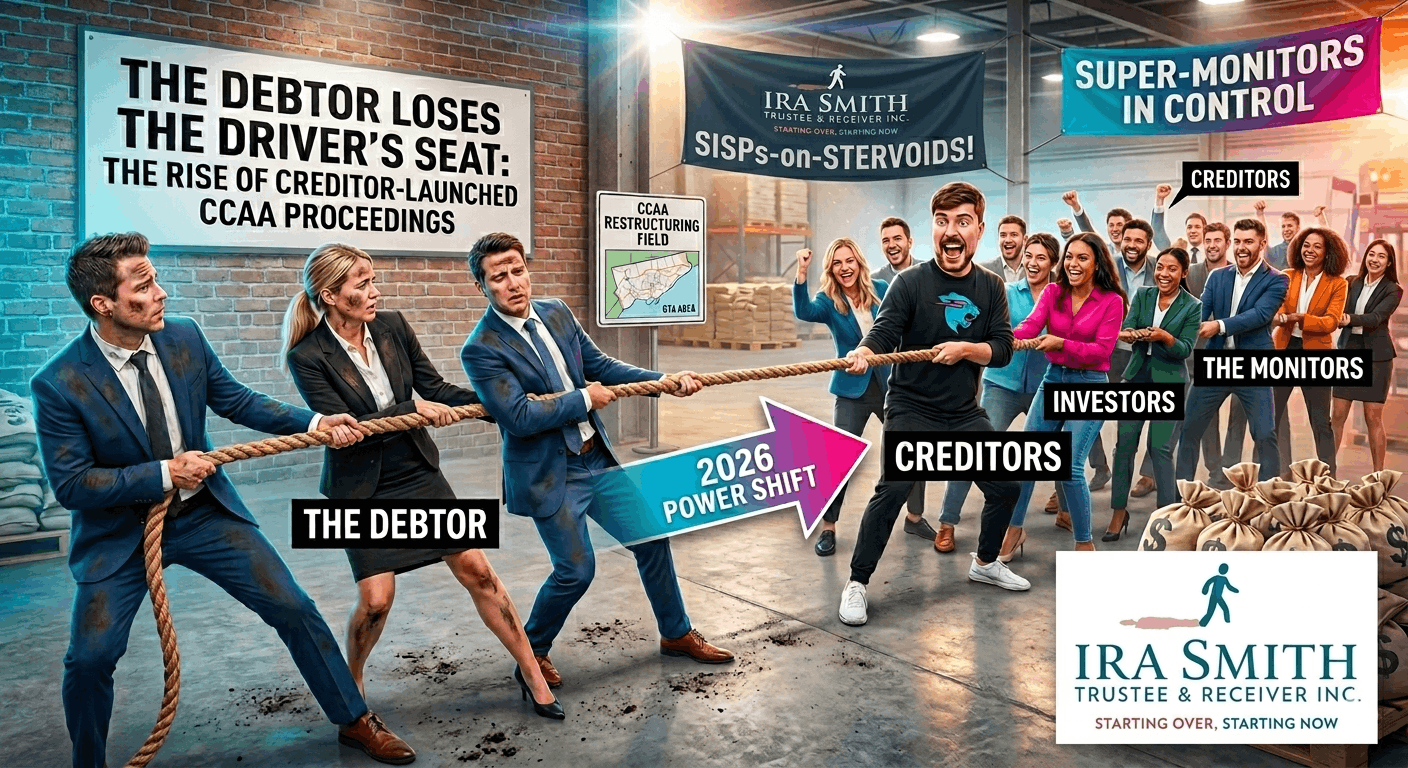
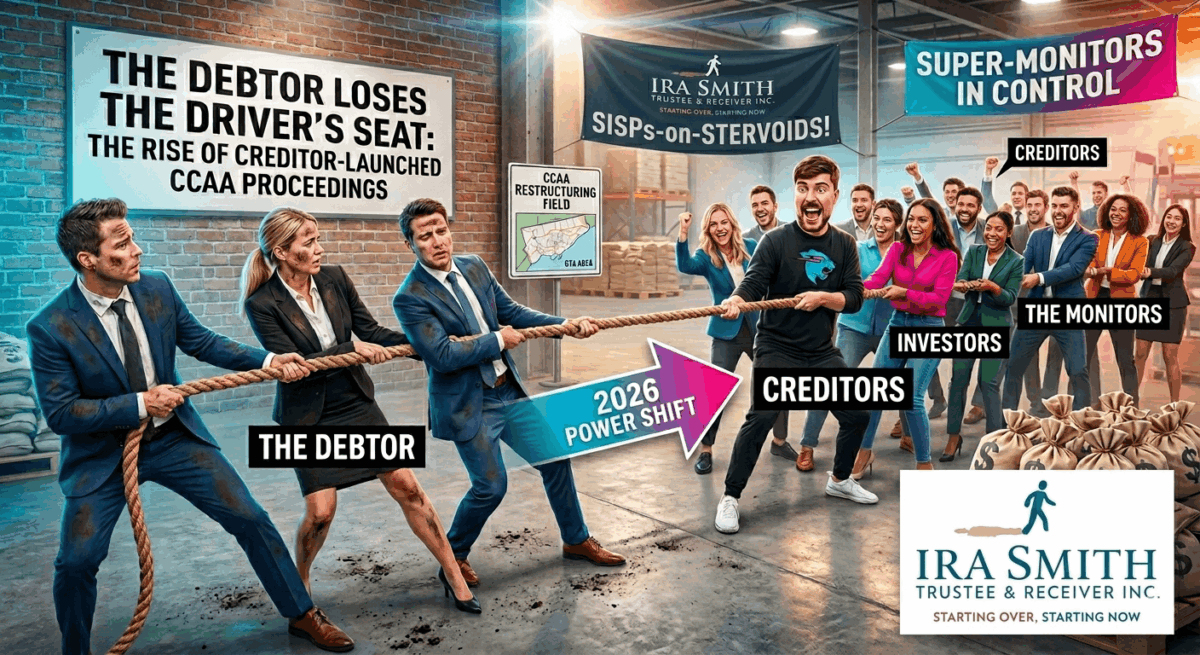
An image of a tug of war between the debtor company, creditors and shareholders on a CCAA reorganizataion administered by the Monitor Ira Smith Trustee & Receiver Inc.

#CorporateRestructuring #CCAA #TorontoBusiness #InsolvencyLaw #DebtRelief #CreditorRights #thedebtor #BIA #IraSmithTrustee #Companies’CreditorsArrangementAct #AngusManorDecisionAlberta

Categories
Brandon Blog Post

THE ONE BLOOR WEST CONDO: OUR COMPLETE BILLION-DOLLAR CCAA CASE STUDY IN REAL ESTATE INSOLVENCY

The One Introduction: Toronto’s Resilient Icon at Bloor & Yonge Faces Financial Distress

For entrepreneurs and advisors across the GTA, the story of The One—now officially One Bloor West (the Project)—for some time now was Toronto’s most talked-about condo project. Now it is Toronto’s most talked-about troubled condo project. Its story offers a powerful real-world lesson in the mechanics and necessity of complex financial restructuring. As one of Toronto’s most ambitious luxury condo, hotel, and retail developments, its financial unravelling sent shockwaves through developers, creditors, and, most painfully, individual purchasers.

As a Licensed Insolvency Trustee and Senior Vice-President at Ira Smith Trustee & Receiver Inc., I’ve worked with businesses of all sizes, navigating financial distress. The One’s insolvency illustrates how court-supervised processes—specifically Receivership and the Companies’ Creditors Arrangement Act (CCAA)—can be used to stabilize troubled assets, preserve value, and manage multi-billion-dollar liabilities.

This case study explores the events that led to court intervention, the strategic decisions made to protect and enhance the Project’s value, and the difficult—but necessary—termination of hundreds of condo purchase agreements. For those advising companies facing critical debt and project risk, this case highlights the vital role of insolvency professionals in steering them toward recovery and maximizing value.

The One Descent Into Insolvency – A Pivotal Turning Point: Receivership and a New Beginning

Located at the southwest corner of Yonge and Bloor in Toronto, the 85-storey mixed-use tower was envisioned as a landmark. But Sam Mizrahi and Mizrahi Developments, the original developer, encountered years of delays, cost overruns, supply chain issues, and legal disputes.

Mounting financial strain led to court intervention. On October 18, 2023, the Ontario Superior Court of Justice (Commercial List) appointed a Receiver and Manager of the Project’s assets.

The Receiver’s Mandate

The Receiver’s role was clear but challenging: stabilize the Project, protect its value, and maximize recoveries for stakeholders. A critical early step was securing additional financing from senior secured lenders to keep construction moving.

The financial distress was immense. As of the Receivership Date, secured debt totalled approximately $1.9 billion, including accrued interest. By September 30, 2025, that figure had surpassed $2.0 billion. Notably, purchasers of condo units were not among the secured creditors—highlighting the precariousness of their position.

During this phase, the Receiver reviewed all existing contracts, including condominium sales agreements (CSAs), and assessed unit fair market values. Importantly, the Receiver made it clear that early communications did not affirm any contracts and reserved the right to disclaim them if necessary.

The One Pivot to CCAA Protection and Strategic Governance

Insolvencies of this complexity often require transitioning between legal frameworks. While Receivership provided initial stabilization, the Project ultimately moved under the CCAA to enable a more flexible and strategic restructuring.

This transition occurred on April 22, 2025, when the Court issued the Initial Order. The Receiver was appointed as Monitor, and FAAN Advisors Group Inc. became the Chief Restructuring Officer (CRO).

Why the CCAA Was Essential

For GTA businesses considering restructuring, The One demonstrates the advantages of the CCAA over traditional receivership in complex, ongoing developments:

  1. Ordinary Course Sales: Under the CCAA, the restructured Companies could sell units in the ordinary course of business—rather than through a Receiver’s “as-is, where-is” process. This approach is expected to yield higher sale prices and better value realization.
  2. DIP Financing: The CCAA enabled approval of $615 million in Debtor-in-Possession (DIP) financing to fund construction and restructuring. This capital was critical to keeping the Project on track for completion in 2028.
  3. CSA Plan Implementation: Section 32 of the CCAA allowed the Companies to disclaim or resiliate agreements—an essential power for executing the Condominium Sales Agreement Plan (CSA Plan) aimed at maximizing asset value.

This strategic shift, supported by Tridel (the new project manager), the Monitor, and senior secured lenders, had one goal: to maximize the Project’s value.An anxious woman looks shocked in front of a dramatic skyscraper under stormy skies, with shattered glass and a chain breaking, highlighting the fallout of "The One" luxury condo project being rescinded in a billion-dollar real estate insolvency case study; featuring the Ira Smith Trustee & Receiver Inc. logo. This visual emphasizes "the one" as a major court-ordered CCAA real estate insolvency event.

Maximizing The One Value and The New Era: Tridel’s Stewardship and Renewed Promise

The restructuring team concluded that the original design and existing CSAs (the Base Configuration) no longer aligned with market realities. To protect creditor recovery, the strategy focused on boosting future residential sales revenue.

Independent Validation

The Receiver engaged respected market experts—Milborne Group and Urbanation Inc.—to assess the residential component’s value. Their findings were clear:

  • Milborne Group advised that aligning with a five-star luxury hotel brand could increase pricing by up to 20%.
  • Urbanation Inc. confirmed that reconfiguring unit sizes and mix could command a premium over the average price per square foot (PSF) under the existing CSAs.

The One CSA Plan Reconfiguration

Originally, the Project included 415 residential units. But by 2022, demand for small, investor-type condos had sharply declined. In response, the Monitor and Tridel implemented a reconfiguration strategy:

  • Reduced the total number of units to 411.
  • Converted smaller one-bedroom units into larger two-bedroom suites.
  • Shifted focus toward “ultra-luxury” units aligned with the anticipated hotel partnership.

This redesign, combined with the ability to resell units at significantly higher prices (compared to the $1,651 PSF average under the original CSAs), is projected to generate over $200 million in additional proceeds—directly benefiting the secured creditors.

Disclaiming The One Purchaser Contracts

Why Contracts Were Cancelled

  • Nearly all Purchase and Sale Agreements (CSAs) were terminated to maximize value for creditors.
  • Justice Osborne approved the disclaimer of 314 out of 329 contracts in November 2025.
  • Only 15 contracts were deemed economically viable to retain.

The One Legal Basis and Process

  • The Companies used Section 32 of the CCAA to disclaim agreements.
  • Notices were sent on October 24, 2025, with termination effective November 23, 2025.
  • The Monitor and CRO argued this was necessary due to insolvency and creditor recovery needs.

Buyer Reaction and Court Response

  • Many buyers were emotionally devastated, with some attending court to oppose the motion.
  • Justice Osborne acknowledged the hardship but emphasized the developer’s insolvency.
  • Only one formal objection was filed by the November 10 deadline.
  • Buyers were informed that any damage claims would be unsecured and likely unrecoverable.

The One Deposit Return Protocol

Protection Mechanisms

  • Total deposits under disclaimed CSAs: approx. $87.5 million.
  • Two protections in place:
  1. Tarion Bond – covers first $20,000.
  2. Excess Deposit Insurance – provided by Aviva Insurance Company of Canada for amounts over $20,000.

Court-Approved Refund Process

  • Justice Osborne approved the protocol on November 17, 2025.
  • Refunds include principal + interest (per Condominium Act, 1998).
  • Administered by Aviva’s agent.

Steps for Buyers

  • Submit documents via the Agent’s website:
  1. Release and Termination Agreement
  2. Government-issued ID
  3. Original CSA
  4. Refunds issued within 10 business days of Tarion confirmation.An anxious woman looks shocked in front of a dramatic skyscraper under stormy skies, with shattered glass and a chain breaking, highlighting the fallout of "The One" luxury condo project being rescinded in a billion-dollar real estate insolvency case study; featuring the Ira Smith Trustee & Receiver Inc. logo. This visual emphasizes "the one" as a major court-ordered CCAA real estate insolvency event.

The One Market Impact and Buyer Implications

Buyer Losses

  • Buyers lost units purchased at 2017–2018 prices, now far below the current market value.
  • Many expressed concern over the fairness and transparency of pre-construction contracts.

Market Lessons

  • The case highlights risks in pre-construction real estate, especially in insolvency scenarios.
  • Government addendums may give developers Its, eroding buyer confidence.

Early Purchase Opportunity

  • Disclaimed buyers were offered early access to new units before public sale (mid-to-late 2026).
  • New units are priced significantly higher due to luxury rebranding and market appreciation.

FAQs: Understanding the Financial Restructuring of One Bloor West

Q1: What is One Bloor West, and why is it important?

One Bloor West is a luxury condo, hotel, and retail building planned for the corner of Yonge and Bloor in Toronto. It was supposed to be an 85-storey tower and one of Canada’s tallest buildings. At first, it was a symbol of ambition, but delays and financial problems turned it into one of Toronto’s most troubled real estate projects.

Q2: What caused the financial problems?

The original developer, Sam Mizrahi of Mizrahi Developments, faced years of setbacks. These included construction delays, rising costs, supply chain issues, and legal battles. Eventually, the financial pressure became too much, and in October 2023, the Ontario Superior Court appointed a Receiver to take control of the project.

Q3: How much debt did the project have?

By the time the court stepped in, the project had about $1.9 billion in secured debt. By September 2025, that number had grown to over $2 billion. People who bought condo units were not considered secured creditors, meaning they were not first in line to get their money back.

The project first went into receivership, which helped stabilize it. Then, in April 2025, it moved under the Companies’ Creditors Arrangement Act (CCAA). This law gave the team more flexibility to restructure the project and try to save its value.

Q5: Why was switching to the CCAA important?

The CCAA allowed for:
• Regular Sales: Units could be sold normally, not just as-is, which helped get better prices.
• New Financing: The court approved $615 million in new funding to keep construction going.
• Contract Changes: The team could cancel or change old agreements that no longer made financial sense.

Q6: Why were most condo purchase agreements cancelled?

Out of 329 original condo contracts, 314 were cancelled. The court agreed that keeping them would hurt the project’s value. Only 15 contracts were kept because they still made financial sense.

Q7: What was the new plan to increase the project’s value?

The team redesigned the building to focus on ultra-luxury units, possibly with a hotel partner. They reduced the number of units from 415 to 411 and made many one-bedroom units into larger two-bedroom suites. Experts believe this could raise prices by up to 20% and bring in over $200 million in extra revenue.

Q8: What happened to buyers’ deposits?

Buyers whose contracts were cancelled had about $87.5 million in deposits. Two protections were in place:
• Tarion Warranty: Covered the first $20,000.
• Aviva Insurance: Covered amounts above $20,000.
Refunds included the original deposit plus interest, following Ontario’s Condominium Act.

Q9: What can businesses learn from this case?

Three key lessons stand out:

  1. Secured creditors come first: Every decision is aimed to protect those who lent the most money.
  2. Adapting to market changes is crucial: The project had to shift to meet luxury market demands.
  3. Legal flexibility matters: The CCAA helped cancel outdated contracts and move forward.An anxious woman looks shocked in front of a dramatic skyscraper under stormy skies, with shattered glass and a chain breaking, highlighting the fallout of "The One" luxury condo project being rescinded in a billion-dollar real estate insolvency case study; featuring the Ira Smith Trustee & Receiver Inc. logo. This visual emphasizes "the one" as a major court-ordered CCAA real estate insolvency event.

The One Business Lesson: Proactive Restructuring

For GTA entrepreneurs and the professional advisor community, the restructuring of The One offers a compelling case study in strategic insolvency management. It highlights three essential principles that can guide businesses through financial turbulence:

1. Secured Creditor Priority Is Paramount

Every major decision—from pivoting to CCAA protection, conducting market research, and redesigning the project, to disclaiming 314 contracts—was driven by the imperative to maximize recovery for Senior Secured Lenders. In Canadian insolvency law, fulcrum creditors (those most at risk of loss) hold significant influence in shaping and approving restructuring plans. Their interests must be prioritized to ensure legal and financial viability.

2. Market Realignment as a Survival Tool

The Project’s original failure stemmed from poor planning (too many small investor units) and shifting market dynamics. The restructuring demanded a bold pivot: redesigning the development to meet ultra-luxury market expectations and partnering with a trusted builder like Tridel. In times of distress, survival hinges on aggressive, market-responsive strategies that unlock asset value and restore stakeholder confidence.

3. The CCAA Enables Contractual Flexibility

Unlike many legal frameworks, the CCAA empowers debtors—under court-appointed Monitor oversight—to disclaim burdensome contracts, including long-term purchase agreements. This flexibility is vital when legacy obligations obstruct operational or financial recovery.

The One Expertise in the Eye of the Storm

The One Bloor West restructuring journey—from the tallest building Receivership to a court-approved CCAA plan—required balancing billions in secured debt, divergent stakeholder interests, and the expectations of hundreds of purchasers, all while constructing Canada’s tallest building. The successful implementation of the CSA Plan and Deposit Return Protocol safeguards buyer deposits and preserves long-term value for senior creditors.

This case underscores a critical truth: when a business faces overwhelming financial headwinds, decisive action and expert legal navigation are non-negotiable. Whether it’s a high-profile real estate insolvency or a smaller corporate crisis, the path to stability demands seasoned guidance to transform chaos into clarity.

Your Partner in Restructuring

At Ira Smith Trustee & Receiver Inc., we specialize in helping GTA entrepreneurs and businesses navigate these pivotal moments. If your company is burdened by debt, locked into unworkable contracts, or approaching a financial breaking point, engaging a Licensed Insolvency Trustee isn’t just prudent—it may be the only way to stop the bleeding, stabilize operations, and build a solvent future.

Our team brings the same level of strategic insight, legal acumen, and hands-on execution that defined The One Bloor West troubled condo project turnaround. We don’t just manage crises—we engineer recoveries.

If your business is in distress, don’t wait. Contact Ira Smith Trustee & Receiver Inc. today to take proactive steps toward financial stability.

P: 905.738.4167

Toronto line: 647.799.3312

brandon@irasmithinc.com or ira@irasmithinc.com

https://irasmithinc.com/

Disclaimer: This analysis is for educational purposes only and is based on the cited legal decisions and my professional expertise as a licensed insolvency trustee. The information provided does not constitute legal or financial advice for your specific circumstances.

Every situation is unique and involves complex legal and factual considerations. The outcomes discussed in this article may not apply to your particular situation. Court decisions are fact-specific and depend on the particular circumstances of each case.

Please contact Ira Smith Trustee & Receiver Inc. or consult with qualified legal or financial professionals regarding your specific matter before making any decisions.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a licensed insolvency trustee serving clients across Ontario. With extensive experience in complex court-ordered receivership administration, corporate restructuring, and insolvency proceedings, Brandon helps businesses, creditors, and professionals navigate challenging financial situations to achieve optimal outcomes.

Brandon stays current with landmark developments in Canadian insolvency law, including the recent The One decision that is reshaping receivership practice. He brings this cutting-edge knowledge to every client engagement, ensuring his clients benefit from the most current understanding of their rights and options.An anxious woman looks shocked in front of a dramatic skyscraper under stormy skies, with shattered glass and a chain breaking, highlighting the fallout of "The One" luxury condo project being rescinded in a billion-dollar real estate insolvency case study; featuring the Ira Smith Trustee & Receiver Inc. logo. This visual emphasizes "the one" as a major court-ordered CCAA real estate insolvency event.

Categories
Brandon Blog Post

THE CANADIAN MOTOR FREIGHT LTD. SAD RECEIVERSHIP SAGA: OUR COMPLETE GUIDE ON WHAT HAPPENS WHEN YOU DON’T FOLLOW COURT ORDERS

Canadian Motor Freight Ltd. Introduction

Have you ever wondered what happens when a company can’t pay its debts? In the case of Canadian Motor Freight Ltd., a Mississauga, Ontario-based logistics company providing seamless transportation solutions, the situation became a legal drama that teaches us important lessons about following court orders.

What Happened to Canadian Motor Freight Ltd.?

Canadian Motor Freight Ltd. was a logistics company that ran into serious money problems. By October 2024, the company owed over $20 million to Canadian Western Bank (CWB) and couldn’t keep up with payments. This financial crisis led to a court process called “receivership,” in which a licensed insolvency trustee is appointed to take control of a company’s assets to sell the assets to help pay back all or a portion of what is owed.

The Road to Receivership

The court put Canadian Motor Frleight Ltd. into interim receivership on October 8, 2024, and then full receivership on November 15, 2024. This interim receiver appointment happened because:

  • The company stopped making loan payments to CWB
  • The company gave false financial information to the bank
  • The business had consistent losses
  • Beyond the CWB debt, they owed around $1.7 million to equipment financing companies
  • They were selling their accounts receivable to another company (REV Capital) without telling CWB
  • The City of Mississauga had started the tax sale proceedings process to sell CMF’s property due to unpaid taxes

Because of these serious issues, the court went from an interim receiver to a full receiver. The Receiver’s job was to take control of all Canadian Motor Freight Ltd.‘s assets and manage them to pay back creditors as fairly as possible.canadian motor freight ltd

The Missing Trucks Mystery

One of the most valuable things Canadian Motor Freight Ltd. owned was its fleet of trucks. These vehicles were essential assets that could be sold to help pay back some of the debt. However, instead of cooperating with the receiver as required by law, management made a fateful decision.

Rather than turning over the trucks to the receiver, company managers moved all the vehicles to a different location – a yard owned by a company called United Group of Companies. This move directly violated the court’s receivership order.

Trying to Recover the Assets

When the receiver discovered the trucks were missing, they tried to talk with United Group to gain access to the vehicles. When these discussions failed, the receiver had to return to court to get a specific “Asset Recovery Order” that directed United Group to allow the receiver onto their property to take possession of the trucks.

Unfortunately, this didn’t solve the problem. United Group and its management refused to comply with this new court order. They wouldn’t let the receiver take the trucks as directed by the court. This direct defiance of a court order is considered very serious in the Canadian legal system.

When Ignoring Court Orders Leads to Contempt

Because both Canadian Motor Freight Ltd.’s management and United Group weren’t following the court’s instructions, the receiver took further legal action. The receiver asked the court to hold both companies and their management in contempt of court for disobeying both the original Receivership Order and the Asset Recovery Order.

The evidence showed a clear pattern of defiance:

  • Debtor company’s management deliberately moved the trucks to United Group’s yard despite knowing about the Receivership Order
  • United Group refused to allow the receiver access to take the trucks
  • United Group demanded payments they weren’t entitled to before they would cooperate
  • After being specifically ordered to provide access, United Group secretly moved the trucks again to unknown locations

The judge strongly criticized these actions, saying the parties were playing a “shell game” with the company’s assets and “thumbing their nose” at the court. This kind of behaviour undermines the entire legal system.canadian motor freight ltd

The Contempt Ruling

The judge found that both Canadian Motor Freight Ltd.‘s management and United Group’s management were guilty of civil contempt. In Canada, three main elements must be proven for civil contempt:

  1. The court orders must be clear and understandable
  2. The people accused must have known about the orders
  3. The violation of the orders must have been intentional

The judge determined that all three conditions were met in this case. United Group claimed they were just “negotiating” with the receiver, but the judge dismissed this excuse, seeing it as just a delay tactic.

The judge then scheduled a sentencing date, giving the parties a chance to fix the situation before final penalties were decided. It is very normal for courts to allow those accused of contempt of court to take the right steps to purge their contempt. Most people take advantage of that opportunity so that they are no longer running afoul of court orders.

Because of these actions, the judge sentenced the leader of United Group to spend four days in jail. This person was considered the “directing mind” of the company, meaning they were the main decision-maker. The judge also ordered several other individuals involved in the case to pay different amounts of money to cover legal costs.

United Group itself received a much larger financial penalty, having to pay a significantly higher amount in costs than the individuals. These penalties show how seriously the court took the failure to follow orders in the Canadian Motor Freight Ltd. case.

Taking It to a Higher Court

Not accepting the contempt findings, both Canadian Motor Freight Ltd. and United Group (along with their management) appealed to the Court of Appeal for Ontario. They hoped the higher court would overturn the original judge’s decision.

However, on April 8, 2025, the Court of Appeal dismissed both appeals, fully supporting the original judge’s findings. The Court of Appeal explained their reasoning:

  • The original judge had provided detailed and clear reasons for the contempt finding
  • The so-called “negotiations” were correctly identified as delay tactics
  • The companies and their management failed to show that the original judge made any serious errors
  • The Receivership Order clearly stated that all of the company’s property had to be turned over to the receiver
  • Management knew about this order and intentionally disobeyed it
  • The sentences given by the original judge were appropriate and possibly even “on the lenient side.”

The Court of Appeal concluded with a powerful statement:

“It is a fundamental principle that orders of a court are to be obeyed. They are not to be stalled, and they are not to be negotiated. Serious consequences are to be expected by anyone who wilfully fails to obey a court order.”

canadian motor freight ltd

The Wider Financial Problems at Canadian Motor Freight Ltd.

The case of Canadian Motor Freight Ltd. reveals a company facing enormous financial challenges. Online industry forums like InsideTransport.com had threads discussing CMF’s situation starting in October 2024, showing that people in the trucking industry were aware of the company’s troubles.

Documents from the receivership process provide more details about the company’s financial state. A Motion Record includes various documents related to the receivership, including:

  • Examination of company officials to gather information about assets
  • Lists of company receivables and customers
  • Communications between the receiver and legal representatives
  • Evidence of returned checks due to insufficient funds from earlier in 2024
  • Financial statements showing significant expenses against their revenue

The 2023 financial statements for the company showed sales of over $21 million but also revealed major expenses.

All these factors contributed to the company’s inability to meet its financial obligations, ultimately leading to receivership.

How Receivership Works in Canada

To better understand the Canadian Motor Freight Ltd. case, it helps to know how receivership works in Canada. Receivership is a legal process used when a company can’t pay its debts and creditors need help recovering their money.

The Receivership Process

  1. Court Appointment: A creditor (like a bank) asks the court to appoint a receiver, usually when a company has defaulted on loans.
  2. Taking Control: Once appointed, the receiver takes control of the company’s assets. Company management must cooperate and turn over all property and records.
  3. Asset Management: The receiver evaluates assets, may continue running the business temporarily, and eventually sells assets to generate funds.
  4. Debt Repayment: Money from asset sales goes toward paying creditors according to legal priorities.

For Canadian Motor Freight Ltd., this process began when Canadian Western Bank sought the court’s help to recover their $20+ million. The receiver was appointed to manage the company’s assets, including the valuable truck fleet that later became the center of the contempt case.canadian motor freight ltd

Why Court Orders Must Be Followed

The Canadian Motor Freight Ltd. case highlights a crucial aspect of our legal system: court orders aren’t suggestions – they’re commands that must be obeyed. There are several reasons why following court orders is essential:

As seen with Canadian Motor Freight Ltd. and United Group, failing to follow court orders can lead to:

  • Being found in contempt of court
  • Financial penalties
  • Potential jail time for individuals
  • Damage to business and personal reputations

System Integrity

Our legal system works only if people respect court authority. If people could pick and choose which orders to follow, the entire system would break down. The Court of Appeal emphasized this point in its ruling on this case.

Fair Resolution of Disputes

Court orders ensure that conflicts are resolved fairly. In receivership cases like Canadian Motor Freight Ltd., the process helps ensure that creditors are treated according to established legal priorities rather than allowing some parties to gain unfair advantages.

The Impact on the Trucking Industry

While the Canadian Motor Freight Ltd. case focuses on one company’s struggles, it raises questions about the broader Ontario trucking industry. The trucking sector faces numerous challenges:

Rising Costs

The financial documents from Canadian Motor Freight Ltd. highlight the significant costs of running a trucking operation:

  • Fuel costs in the millions
  • High insurance premiums
  • Equipment financing payments
  • Maintenance expenses

Thin Profit Margins

Trucking companies often operate on slim profit margins, making them vulnerable when costs rise or when economic downturns reduce shipping demand.

Competitive Pressures

The logistics industry is highly competitive, with companies often underbidding each other to win contracts, sometimes at unsustainable rates.

Regulatory Requirements

Trucking companies must comply with numerous regulations regarding safety, driver hours, vehicle maintenance, and environmental standards, all of which add to operational costs.

While we can’t say from this single case whether the entire Ontario trucking industry faces similar problems, the Canadian Motor Freight Ltd. situation highlights the financial pressures that can push logistics companies to the breaking point.canadian motor freight ltd

Lessons from the Canadian Motor Freight Ltd. Case

The story of Canadian Motor Freight Ltd. offers several important lessons for businesses and individuals:

1. Court Orders Are Non-Negotiable

The primary lesson is that court orders must be followed. The Court of Appeal made it clear that orders “are not to be stalled, and they are not to be negotiated.”

2. Transparency with Creditors is Essential

Canadian Motor Freight Ltd.‘s provision of false financial information to CWB contributed to its problems. Being honest with lenders about financial difficulties might lead to workable solutions before receivership becomes necessary.

What started as financial difficulties for Canadian Motor Freight Ltd. escalated into contempt of court findings when company leadership tried to hide assets rather than comply with the receivership process.

4. Expert Help is Valuable During Financial Distress

Companies facing financial problems should seek qualified legal and financial advice early. Professional guidance can help navigate difficult situations and potentially avoid the more severe consequences of receivership.

The Canadian Motor Freight Ltd. receivership saga demonstrates the serious consequences that can follow when court orders are ignored. From the initial financial troubles to the contempt findings and appeals, this case reinforces a fundamental principle of our legal system: court orders must be respected and obeyed.

For businesses facing financial difficulties, the case serves as a cautionary tale about the importance of transparency, cooperation, and compliance with legal processes. While financial problems are challenging, attempting to hide assets or obstruct court-appointed receivers only makes the situation worse.

The Court of Appeal’s firm stance in upholding the contempt findings against Canadian Motor Freight Ltd. and United Group sends a clear message about the importance of court authority in ensuring that financial disputes are resolved fairly and according to established legal procedures.

As we follow developments in the trucking and logistics industry, the Canadian Motor Freight Ltd. case will likely be remembered as an important example of how not to handle a company’s financial crisis and the serious consequences that can follow when court orders are defied.

I hope you’ve found this Canadian Motor Freight Ltd. Brandon’s Blog helpful. If you or someone you know is struggling with too much debt, remember that the financial restructuring process, while complex, offers viable solutions with the right guidance.

At the Ira Smith Team, we understand the financial and emotional components of debt struggles. We’ve seen how traditional approaches often fall short in today’s economic environment, so we focus on modern debt relief options that can help you avoid bankruptcy while still achieving financial freedom.

The stress of financial challenges can be overwhelming. We take the time to understand your unique situation and develop customized strategies that address both your financial needs and emotional well-being. There’s no “one-size-fits-all” approach here—your financial solution should be as unique as the challenges you’re facing.

If any of this sounds familiar and you’re serious about finding a solution, reach out to the Ira Smith Trustee & Receiver Inc. team today for a free consultation. We’re committed to helping you or your company get back on the road to healthy, stress-free operations and recover from financial difficulties. Starting Over, Starting Now.

The information provided in this blog is intended for educational purposes only. It is not intended to constitute legal, financial, or professional advice. Readers are encouraged to seek professional advice regarding their specific situations. The content should not be relied upon as a substitute for professional guidance or consultation. The author, Ira Smith Trustee & Receiver Inc., and any contributors do not assume any liability for any loss or damage.canadian motor freight ltd

Categories
Brandon Blog Post

THE CANADIAN RECEIVERSHIP EASY BEGINNERS GUIDE

receivership

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic.

Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

If you wish to listen to an audio version of this Brandon Blog, please scroll to the very bottom of the page and click play on the podcast.

What is Receivership?

Last week I wrote an easy beginner’s guide on bankruptcy. This Brandon Blog is for anybody interested in finding out what type of insolvency process receivership is and how it differs from some other insolvency processes. I will explain the receivership process, provide an overview of what happens in a receivership, explaining what is sought to achieve, and the consequences of receivership.

Receiverships occur when a secured lender enforces its security to recover loans that have been defaulted on by a borrower. Secured creditors appoint an insolvency trustee to serve as receiver or receiver-manager depending on the terms of their security documents when the corporate debtor defaults.

Receivers and secured lenders can enter into a private contract appointing a receiver. Alternatively, the secured lender may seek an order from the court appointing a receiver. I’ll talk more about that shortly.

What Does Going into Receivership Mean?

If the corporate debtor defaults on a secured loan, the creditor may be entitled to appoint a receiver to collect their money. In Canada, “Section 244” notices are specific forms of notification that secured creditors must send to defaulting companies.

The notice specifies the assets covered by the security, the amount owed by the company in default, and that the secured creditor has the right to enforce the security after 10 days. The debtor company in default can consent to the appointment of the receiver before the expiration of the 10 day notice period.

A Section 244 notice is prescribed under the Bankruptcy and Insolvency Act (Canada) (BIA), and it is usually the last notice a creditor receives before the receiver takes possession of the debtor’s assets, properties, and undertakings.

Receivers then liquidate the assets of a business in order to pay secured creditors.

receivership

How Receivership Works

Parliament amended the BIA insolvency legislation in 1992 by enacting Part XI. BIA sections 243 through 252 to deal with secured creditors and receivers. Prior to that time, there was no federal statute insolvency legislation dealing with receivership matters. These provisions provide information about the court that hears bankruptcy and insolvency cases control over receivership matters that involve all or substantially all of the inventory, the accounts receivable, or the other property of a debtor. There are also restrictions imposed on the duties of secured creditors and receivers. It also stipulates that only a licensed insolvency trustee can act as a receiver. Part XI applies to both privately-appointed and court-appointed receivers.

These sections do not confer any powers available to a trustee of a bankrupt estate on secured creditors or receivers. Only those powers conferred upon the receiver in the appointment letter are granted to private receivers, and those are the powers specified in the security instrument. However, the receiver may also exercise certain statutory powers. If certain powers are required to administer the estate but are omitted under the security instrument, a receiver cannot act. Receivers are generally appointed by the secured creditor pursuant to security that at least states:

  • the collateral secured under the security; and
  • the receiver has the right to dispose of the collateral, including operating the insolvent debtor‘s business.

In a court-appointed receivership, the powers of the receiver come from the receivership appointment court order appointing the court-appointed receiver.

Receivership: Notice and Statement of the Receiver

From the 1992 amendments to the BIA, a receiver is required to provide notice to all known creditors of an insolvent debtor in receivership. Previously, creditors were not required to be notified.

When the receiver has become the receiver of an insolvent debtor‘s property, the receiver must provide notice of receivership as soon as reasonably possible but within 10 days of its appointment. Notice of the receivership must be sent to all creditors, the Office of the Superintendent of Bankruptcy and the insolvent debtor.

If the debtor is also bankrupt, rather than sending the notice to all creditors, the receiver sends the notice to the bankruptcy trustee. Since the creditors are already represented in corporate bankruptcy by the Trustee, the bankruptcy process will deal with them.

A receivership notice states, among other things, that the receiver has been appointed, whether it is a private appointment or a court appointment, and what the receiver’s plan of action is. Additionally, it contains a list of all known creditors.

As part of the receivership process, the receiver must provide interim reports every six months as well as a final report when the receivership is concluded. A copy of the receiver’s final receipts and disbursements statement must also be included in the final notice.receivership

What’s The Difference Between a Court-Appointed Receiver and a Privately Appointed Receiver?

A court-appointed receiver vs. a privately appointed receiver is something people always want to know the answer to. I will explain the difference to you. It is pretty simple. Based on what I have already written, you have probably guessed it by now.

In a Court-appointed receivership, when the Court appoints a receiver, it does so through an Order on the application of the secured creditor. As between a secured creditor and a debtor, a privately appointed receiver is a receiver who is appointed by the secured creditor as provided in the Security Agreement. The Court-appointed receiver’s administration is supervised by the Court.

How is Receivership Different from Bankruptcy? Bankruptcy / receivership

Bankruptcy vs. receivership is also something people want to know. Many times, people confuse the two and use the terms receivership and bankruptcy, mistakenly, interchangeably. Often, receiverships and bankruptcy are confused, but the differences between the two are fairly straightforward. Whether it is a private appointment or a Court-appointed receivership, it is still different.

There are several main differences between bankruptcy and receivership. A receivership is a remedy available to secured creditors, as stated above. In order to enforce the secured creditor’s security rights against a defaulting debtor, a receiver is appointed.

Bankruptcy is a separate legal process. Trustees do not represent secured creditors in bankruptcy. Instead, they represent unsecured creditors. Corporate bankruptcy can occur simultaneously with a receivership of the same corporate debtor. The process of a corporate bankruptcy would be the subject of another Brandon Blog. To find other Brandon Blogs about corporate bankruptcy, use the search function at the top of this page.receivership

What’s the Difference Between Receivership and Liquidation?

By now you know what the definition of receivership is. So I won’t repeat it because I do not want to sound like a broken record (younger people may not catch that reference!)!

Liquidation is not governed by the federal BIA. Rather, it is done under the provincial Business Corporations Act or Wind-Up Act. A liquidation is for a solvent company where the shareholders, Officers and Directors decide to cease business operations by running off any existing contracts and selling off the assets. The cash obtained is then used first to pay off the creditors. Any funds leftover is then distributed to the shareholders.

Just like a receiver, a liquidator can be appointed either privately by resolution of the Directors or by Court order. Liquidation is not a receivership or bankruptcy.

Employee Rights in Bankruptcy Protection and Bankruptcy⁄Receivership

A device was created by the BIA for employees of a company that went bankrupt or into receivership. It does not apply to employees of a company trying to rightsize itself through reorganization; either a BIA Proposal or a Plan of Arrangement under the CCAA. The Wage Earner Protection Program Act (WEPPA) protects wages or benefits, including termination and severance pay, accumulated in the 6 months prior to a business going bankrupt or going into receivership.

The WEPPA ended up being enacted due to the federal government’s concern that when a company went bankrupt and employees were not paid their wages, there was rarely an opportunity for them to recoup any of their income. There are limits or caps on what employees can receive.

In the period in which amounts are past due to you, you will not qualify for WEPPA if:

  • you are a Director or Officer of the business;
  • or you have worked as a manager for the company
  • you are part of the management responsible for negotiating or refusing to pay amounts owed.

You may qualify if:

  • the previous employer has gone bankrupt or into receivership.
  • The firm owes you wages, salaries, vacation pay, or unreimbursed costs throughout the six months prior to the date of bankruptcy or receivership.

When an employer enters bankruptcy or receivership, the WEPPA provides funds to employees owed money. Those employees who qualify are paid as soon as possible. An employee’s qualifying earnings are equal to seven times their maximum regular insurance earnings under the Employment Insurance Act. According to Service Canada, the maximum amount of $56,300 a year is the limit for insurable earnings as of January 1, 2021. Thus, in 2021 the maximum amount a former employee can claim under WEPPA is $7,578.83.

Trustees and receivers are required to inform employees about the WEPPA program and provide information about amounts due. In the event of bankruptcy or receivership, trustees, as well as receivers, have 45 days to submit to Service Canada the Trustee Information Forms showing the amounts owed to each employee.

In other words, WEPPA‘s payment for former employees is something, but it may not be enough to fully compensate each. As a result of the amount paid by Service Canada, which administers the employment insurance system, $2,000 per employee is a super-priority against the company’s current assets. All remaining amounts paid to each employee, up to the maximum, are unsecured claims.receivership

Receivership summary

I hope you found this receivership Brandon Blog informative and that the differences between receivership, bankruptcy, restructuring and liquidation legal proceedings are now clearer. Because it all has to do with corporate insolvency, the provincial Bankruptcy Courts also deal with receivership matters to adjudicate under the applicable insolvency law.

With too high debt levels and not enough wealth, you are insolvent. You can choose from several insolvency processes to get the debt relief that you need and deserve. It may not be necessary for you to file for bankruptcy.

If you or your business are dealing with substantial debt challenges, you need debt help, and you assume bankruptcy is the only option, call me.

If you’re thinking about bankruptcy, you’re probably in a situation where you’re overwhelmed, frightened, and feel like you’re alone. That’s natural and it is not your fault.

It’s good that you’ve come to this site, where you’ll find answers to your questions, sort through your options, and discover that you can get help. You’re not alone, and the professionals at Ira Smith Trustee & Receiver Inc. are committed to helping you find a debt solution that’s best for you.

It is not your fault that you remain in this way. You have actually been only shown the old ways to try to deal with financial issues. These old ways do not work anymore.

The Ira Smith Team utilizes new modern-day ways to get you out of your debt difficulties with debt relief options as an alternative to bankruptcy. We can get you the relief you need and so deserve. Our professional advice will create for you a personalized debt-free plan for you or your company during our no-cost initial consultation.

You are under a lot of pressure. Our team knows how you feel. You and your financial and emotional problems will be the focus of a new approach designed specifically for you. With our help, you will be able to blow away the dark cloud over your head. We will design a debt settlement strategy for you. We know that we can help you now.

We understand that people with credit cards maxed out and businesses facing financial issues need a realistic lifeline. There is no “one solution fits all” method with the Ira Smith Team. Not everyone has to file bankruptcy in Canada. The majority of our clients never do as we know the alternatives to bankruptcy. We help many people and companies stay clear of filing an assignment in bankruptcy.

Because of this, we can develop a new method for paying down your debt that will be built specifically for you. It will be as unique as the economic problems and discomfort you are experiencing. If any one of these seems familiar to you and you are serious about getting the solution you need to become debt-free, contact the Ira Smith Trustee & Receiver Inc. group today.

Call us now for a no-cost consultation.

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic.

Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

Categories
Brandon Blog Post

BANKRUPTCY TRUSTEE: OUR COMPLETE GUIDE TO WHAT IS A LICENSED INSOLVENCY TRUSTEE

The Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.

Licensed Insolvency Trustees, licensed by the Canadian Government

A bankruptcy trustee (now called a Licensed Insolvency Trustee) is a person or company licensed to administer receiverships, bankruptcies, and proposals in Canada. We are licensed by the Office of the Superintendent of Bankruptcy Canada (OSB).

The role of the bankruptcy trustee is to help people and companies look at their financial situation and explore the various debt relief options. The Trustee can help with many possible debt solutions; much more than just filing bankruptcy. The Trustee looks at various ways the person or business can avoid bankruptcy first. Bankruptcy, which is the legal process for debtors to deal with their unsecured creditors, by discharging away their unsecured debt, including credit card debt and income tax debts, is the last resort.

In this Brandon’s blog, I provide my complete guide on how a bankruptcy trustee helps people and companies who are in a precarious financial situation because they have too much debt by providing insolvency services and helping people and companies through the Canadian insolvency process.

About Bankruptcy Trustees: what is a licensed insolvency trustee?

A Licensed Insolvency Trustee (LIT) is federally certified by the OSB. A trustee in bankruptcy is the old name for a LIT. LITs are the only debt professionals who are federally regulated and supervised professional that offers recommendations and solutions to individuals and businesses with financial problems.

LITs help people make informed choices to manage their debt difficulties. A bankruptcy trustee is the only expert licensed to carry out government-regulated insolvency proceedings such as:

  • privately-appointed or court-appointed receiver or receiver and manager to administer receiverships Bankruptcy and Insolvency Act Canada (BIA).
  • assisting people to restructure through consumer insolvency using a consumer proposal.
  • helping people who owe more than $250,000 (not including debts registered against their principal residence) and companies by making a proposal to creditors as alternatives to bankruptcy.
  • bankruptcy trustee/licensed insolvency trustee in a bankruptcy administration when a person or company is filing for bankruptcy.

As licensed insolvency trustees, we’re here to help: How do I become an insolvency trustee?

A person who wishes to acquire an individual licence may complete and file an application with the OSB. The following are required for the issuance of a personal licence under the BIA:

  • successfully passed the following, which is administered by the Canadian Association of Insolvency and Restructuring Professionals (CAIRP):
  • the Canadian Insolvency and Restructuring Professional (CIRP) Qualification Program (CQP) unless otherwise exempted;
  • the CIRP National Insolvency Exam; and
  • the insolvency counselling course;
  • paid the required fee;
  • the applicant shall be solvent;
  • the applicant must be of good character and reputation; and
  • passed the oral board of examination run by the OSB.

You need to pass the educational program run by CAIRP. In order to register, you need to be sponsored by a bankruptcy trustee. That LIT will most certainly be your employer. When you pass the final CQP exam, you are awarded the CIRP designation and then able to apply to sit before the OSB’s oral board of examiners.

bankruptcy trustee
bankruptcy trustee

Trustees in Bankruptcy near you: How to find a bankruptcy trustee in Canada

If you are looking for a trustee in bankruptcy near you, there are three good ways to find one.

The best way to find a bankruptcy trustee is a referral from friends or family members. Although they themselves may have never filed for bankruptcy, perhaps they know someone who did. Or, maybe they know a lawyer they trust who can provide them with a name or two that could be passed on to you. A personal reference is the best way to go.

The second way is through the OSB. They maintain a searchable database of all LITs in Canada. You can look for a bankruptcy trustee located near you. The directory includes the office locations of all LITs. You can browse either by name, city or province.

The third way is to look for bankruptcy information online. Type into your favourite search engine a phrase like “ bankruptcy trustee”, “bankruptcy trustee near me”, bankruptcy trustee Vaughan ” or “ trustee in bankruptcy Toronto ” and start searching websites. Then call the one whose website seems to speak to you. You can make an appointment for a no-cost consultation to get all your questions answered. You may even want to try two or three so that you can compare approaches. Then you can select the bankruptcy trustee that you feel you could work best with.

The fee of a bankruptcy trustee in a summary administration bankruptcy – The Bankruptcy & Insolvency Act

A personal bankruptcy administration is called a “summary” bankruptcy administration when the realizable assets are estimated at $15,000 or less. This kind of filing for bankruptcy is many times referred to as “no assets, no income”.

Rule 128 of the BIA General Rules dictates the fee and disbursements of a bankruptcy trustee in a summary administration personal bankruptcy. The fee is fixed and is called a tariff. It is calculated as follows:

“128 (1) The fees of the trustee for services performed in a summary administration are calculated on the total receipts remaining after deducting necessary disbursements relating directly to the realization of the property of the bankrupt, and the payments to secured creditors, according to the following percentages:

(a) 100 percent on the first $975 or less of receipts;

(b) 35 percent on the portion of the receipts exceeding $975 but not exceeding $2,000; and (c) 50 percent on the portion of the receipts exceeding $2,000.

(2) A trustee in a summary administration may claim, in addition to the amount set out in subsection (1), (a) the costs of counselling referred to in subsection 131(2);

(b) the fee for filing an assignment referred to in paragraph 132(a);

(c) the fee payable to the registrar under paragraph 1(a) of Part II of the schedule;

(d) the amount of applicable federal and provincial taxes for goods and services; and (e) a lump sum of $100 in respect of administrative disbursements.” If there are no assets or surplus income that will provide cash in the bankruptcy administration, then the debtor, in order to retain the services of the bankruptcy trustee, needs someone to either guarantee the fee and disbursements or post a cash retainer with the LIT in order to file for bankruptcy.

The fees of the bankruptcy trustee in an ordinary bankruptcy

A bankruptcy is called an “ordinary” bankruptcy when the realizable assets are estimated at $15,000 or greater in personal bankruptcy. Every corporate bankruptcy is an ordinary administration.

In an ordinary administration, the trustee is entitled to the remuneration voted by the inspectors in the bankruptcy case. The inspectors are representatives of the creditors who were voted in at the First Meeting of Creditors. The fee must also be approved by the court.

The fee will be affected by the complexity of the bankruptcy case, how much work the LIT had to do to preserve and sell the assets and did the LIT obtain verifiable results that can be described as extraordinary. The time spent and the hourly rates of the bankruptcy trustee staff involved are the basis for calculating the fee in an ordinary administration.

The disbursements incurred are to be added to the fee and must also be taxed. If the bankruptcy trustee is unsure at the outset if there will be any realizable assets, the LIT will ask a third party to provide either a guarantee or cash retainer.

bankruptcy trustee
bankruptcy trustee

The consumer proposal fee for a bankruptcy trustee acting as administrator of a consumer proposal – The Bankruptcy & Insolvency Act

Rule 129 sets out how to calculate the tariff fee in a consumer proposal. As I stated above, one of the roles a bankruptcy trustee is licensed for is to act as the administrator of a consumer proposal This rule states:

“129 (1) For the purposes of paragraph 66.12(6)(b) of the Act, the fees and expenses of the administrator of a consumer proposal that must be provided for in a consumer proposal are as follows:

(a) $750, payable on filing a copy of the consumer proposal with the official receiver;

(b) $750, payable on the approval or deemed approval of the consumer proposal by the court;

(c) 20 percent of the moneys distributed to creditors under the consumer proposal, payable on the distribution of the moneys;

(d) the costs of counselling referred to in subsection 131(1);

(e) the fee for filing a consumer proposal referred to in paragraph 132(c);

(f) the fee payable to the registrar under paragraph 3(b) of Part II of the schedule; and (g) the amount of applicable federal and provincial taxes for goods and services.

Our regular readers of Brandon’s Blog will recall that in previous blogs that I wrote, I described what the BIA minimum requirements are for calculating how much a debtor should offer its creditors as a proposal fund in a consumer proposal. That calculation has nothing to do with what fee the licensed trustee acting as the administrator may be entitled to.

That is why any debtor thinking about filing a consumer proposal in order to avoid bankruptcy need not be concerned with how much they have to pay as a fee. The calculation as to what a reasonable proposal fund will be has zero relation to what the administrator’s fee will be. In this way, the fee of the bankruptcy trustee acting as administrator is no-cost!

The fee of the bankruptcy trustee for the administration of a Division I proposal

Readers of the Brandon Blog will remember that a consumer proposal is available for any individual who has $250,000 of debt or less, not including any debts secured against their personal residence. A Part III Divison I of the BIA proposal is available to all companies and to any person whose debts are too large to do a consumer proposal. Both are alternatives to bankruptcy Under either administration, a proposal is a debt relief plan sanctioned by the BIA. It is the only debt settlement plan authorized by the Government of Canada. Above I described how the fee and disbursements of a bankruptcy trustee in an ordinary bankruptcy administration must be approved by the inspectors and the court.

The same is true for the fee of the bankruptcy trustee acting as the licensed trustee in a Divison I proposal. The calculation of the fee will be very similar to an ordinary bankruptcy administration also. The only difference will be as required by the difference between a proposal and bankruptcy.

A proposal is a great alternative to bankruptcy.

Only a bankruptcy trustee can act as a receiver

Section 243(4) of the BIA states that only a bankruptcy trustee can be appointed as a receiver. It does not matter whether the receiver will be privately or court-appointed. The calculation of the receiver’s fee is based on the hours worked and the hourly rate charged by the respected staff working on the file.

In a private appointment, the fee must be approved by the appointing secured creditor. In a court appointment, the fee must be approved by the court.

bankruptcy trustee
bankruptcy trustee

Bankruptcy trustee summary

I hope you have enjoyed this bankruptcy trustee Brandon’s Blog. Hopefully, you have better insight now into the many roles played by a LIT. As part of any bankruptcy or proposal administration, there are two mandatory credit counselling sessions also. So, the LIT also acts as a credit counsellor.

Do you or your company have too much debt? Are you or your company in need of financial restructuring? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or the person who has too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding bankruptcy. We can get you debt relief freedom.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a debt settlement plan, we know that we can help you.

We know that people facing financial problems need a realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team That is why we can develop a restructuring process as unique as the financial problems and pain you are facing.

If any of this sounds familiar to you and you are serious about finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation.

We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.

bankruptcy trustee
bankruptcy trustee
Categories
Brandon Blog Post

INSOLVENCY AND BANKRUPTCY ACT: ANTI-DEPRIVATION RULE COMPLETELY VALID IN INSOLVENCY

insolvency and bankruptcy act

The Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.

If you would prefer to listen to an audio version of this Brandon’s Blog, please scroll to the very bottom and click on the podcast.

Insolvency and bankruptcy act introduction

On October 2, 2020, the Supreme Court of Canada (SCC) rendered its decision in Chandos Construction Ltd. v. Deloitte Restructuring Inc., 2020 SCC 25 (Chandos decision). This decision upheld the idea that the anti-deprivation rule is completely valid when it pertains to both personal and business insolvency and bankruptcy act cases.

In this Brandon’s Blog, I describe the Chandos case and what it stands for.

The definition of the word deprive and the insolvency and bankruptcy act context

The Merriam-Webster dictionary states the definition of the word deprive is:

  • 1: to take something away from; and
  • : to withhold something from.

In the Chandos Construction Ltd. (Chandos) insolvency and bankruptcy act case, the SCC was asked to rule on contract clauses that if upheld, would deprive the bankruptcy estate and therefore the unsecured creditors of money that would otherwise be available. This deprivation of funds, which may make total sense as between contracting parties, is not enforceable in bankruptcy.

The anti-deprivation rule in the Canadian insolvency and bankruptcy act matters

Neither the Bankruptcy and Insolvency Act (Canada) (BIA) nor the Companies’ Creditors Arrangement Act (CCAA) stops non-defaulting parties to a contract, from relying upon agreement provisions that create an inevitable result when a debtor declares bankruptcy. The common law becomes pertinent in these situations.

Canadian courts still refer to these anti-deprivation provisions as “ipso facto” provisions and also this idea as the fraud upon the bankruptcy law concept. In more current times, this has been described as the anti-deprivation rule.

The SCC has recognized the anti-deprivation rule since the 1890s. However, the contemporary application of this principle in Canadian law greatly originates from an Ontario court decision in 1995 – Canadian Imperial Bank of Commerce v. Bramalea Inc., 1995 CanLII 7262 (ON SC) (Bramalea decision).

This is a decision from the Ontario Court of Justice (General Division). Canadian courts have thought about and decided upon the anti-deprivation rule in many insolvency and bankruptcy act cases since then.

The Bramalea case and its relevance of insolvency and bankruptcy act matters

Luckily for me, Ira Smith was the receiver responsible for the file that involved the Bramalea decision. So, I have a bird’s-eye view of that case which started it all leading to the SCC Chandos decision.

In the Bramalea insolvency and bankruptcy act case, a group of companies, including Bramalea Inc. (Bramalea) was in a partnership agreement to develop and operate a shopping mall in Markham, Ontario called Shoppes on Steeles. In 1995, Bramalea was placed into receivership and bankruptcy. Bramalea’s partners included Sears Canada and a private real estate development company.

Amongst the different provisions of the partnership agreement was a specific provision in the contract which considers insolvency. It said that, in case of the insolvency of any of the partners, the non-insolvent partner(s) (given it does not waive the event of insolvency) can buy the interest of the financially troubled partner at the lesser of book value or fair market value.

The paradox of this case was that the large company partners at the time of the drafting of the partnership contract were concerned about what happens if the private property developer one day became insolvent? None of the partners ever believed that it would be that private company that would be the only one that was not insolvent. We all know what happened to Sears Canada!

The moving parties sought to exercise that right by serving a notification to buy the Bramalea passion at book value, approximated to be around $200,000. This was opposed by the receiver and also other stakeholders.

The receiver gave evidence that the fair market price surpassed book value by as much as $2 million to $3 million. The moving parties acknowledged that the fair market value of Bramalea’s stake in the partnership was more than book value. They did not agree with the receiver’s evidence regarding the amount of that difference. They additionally did not submit their own fair market valuation.

The Bramalea insolvency and bankruptcy act decision

Based on the evidence, the court took the view that the specific spread between book value and fair market value was not trivial. The court was satisfied that the distinction is greater than marginal, and enough to properly draw the interest of the receiver and the creditors.

The receiver’s position was that there is a higher principle in play and that the concern is not one of hindering the freedom of contract. Rather it was just one of whether or not that part of the partnership contract is void as being contrary to the public interest.

The receiver submitted that while the arrangement might quite possibly stand as between the contracting parties, it is void as against the receiver and also the bankruptcy trustee in the Bramalea insolvency and bankruptcy act proceedings.

The court agreed with the receiver’s position in this insolvency and bankruptcy act case. The court decided that it was clear from the provisions of the partnership agreement itself that the parties contemplated a transfer to one of the partners of the other partner’s partnership interest, only in case of insolvency, at a price less than what could be acquired for that interest on the open market.

The court specified that this stipulation made perfect sense, as between the contracting parties. It made total sense in regards to maintaining their partnership and their respective interests. Nevertheless, the court likewise specified that the clause cannot survive through the scrutiny of the “fraud on the bankruptcy law” principle.

The receiver ended up selling Bramalea’s partnership interest to the other partners for fair market value.

insolvency and bankruptcy act

The Chandos Alberta court case and the anti-deprivation rule for insolvency and bankruptcy act matters

Chandos was the general contractor for a condo project contracted with Capital Steel to give $1.3 million worth of steelwork. In the subcontract, Capital Steel agreed that if it became insolvent, Chandos was entitled to all costs arising from the suspension of the contract and it would forfeit 10% of the total subcontract price as an inconvenience fee. Capital Steel performed the majority of its commitments, nevertheless, it filed an assignment in bankruptcy before completing full performance.

As a result, Chandos was forced to finish the contract at an estimated expense of $22,800. Up until that point, Chandos owed Capital Steel $149,618 in outstanding invoices for the job it had performed.

Chandos relied upon the agreement and said that it was qualified to deduct its cost of finishing the job plus 10% of the total contract cost from the amount owing. Given the price of the subcontract, the 10% deduction eliminated Chandos’ balance owing plus an extra amount of $10,511. Chandos declared that gave them a provable claim in the Capital Steel insolvency and bankruptcy act case.

The Trustee’s application to the Alberta Court of Queen’s Bench

On March 6, 2017, the Trustee applied to the Alberta Court of Queen’s Bench seeking advice and directions on whether Chandos was entitled to rely on the provision in the contract or was it void pursuant to the anti-deprivation rule in common-law.

The chambers judge acknowledged that the common law anti-deprivation rule stops parties from contracting out of insolvency and bankruptcy act regulations. The judge stated that if that provision was a liquidating damages provision as opposed to a penalty, it would not violate the rule.

The chambers judge ruled that the condition was an authentic pre-estimate of costs, which imposed liquidated damages and not a penalty. He additionally held that the provision represented a bona fide commercial arrangement that did not have as its predominant objective the deprivation of Capital Steel’s property. Consequently, the chambers judge decided that Chandos can implement the clause against the Trustee.

Trustee appeals the Chandos insolvency and bankruptcy act decision to the Court of Appeal for Alberta

The Trustee appealed the Chandos decision to the Court of Appeal for Alberta. The appellate court reviewed the lower court decision in this insolvency and bankruptcy act case and decided that:

  • The chambers court properly determined the presence and application of the fraud on the bankruptcy law principle in Canada.
  • In describing the scope of the anti-deprivation rule, however, the chambers judge erred.
  • The lower court embraced the purpose-based technique set out by the Supreme Court of the United Kingdom
  • The appropriate technique is to check out the impact of the provision. Its purpose is a different analysis.
  • Chandos certainly had a genuine commercial interest it was looking to protect.
  • However, the clause conflicts with the BIA‘s scheme of distribution. The common law anti-deprivation rule revokes the clause and Chandos cannot count on it to defend its claim against the Trustee.

Chandos appeals to the SCC in this insolvency and bankruptcy act anti-deprivation rule case

One of the key goals of the insolvency and bankruptcy act law is to make certain there is a fair distribution among creditors. In order to fulfill the objective, the legislation restricts specific contractual stipulations that trigger when one of the parties goes into insolvency proceedings (ipso facto clauses).

As seen in the Bramalea situation, one of these limitations is the anti-deprivation rule. It holds that ipso facto conditions that rob the debtor’s creditors of assets they are qualified to receive in insolvency and bankruptcy act matters are void. This is likewise what the Court of Appeal for Alberta decided. Chandos appealed that decision to the SCC.

The Chandos appeal was heard on January 20, 2020. The SCC split decision was released on October 2, 2020. On the facts of Chandos, the SCC dismissed the Chandos appeal. The SCC refused to promote a contractual stipulation that the subcontractor Capital Steel waive 10 percent of the agreed price if Capital Steel became insolvent or bankrupt.

The SCC majority maintained that the test for application of the contractual provision is effects-based and not purpose-based. The SCC majority confirmed that the anti-deprivation rule stands under Canadian common law and it has not been eliminated in dismissing the appeal in this corporate insolvency and bankruptcy act case.

insolvency and bankruptcy act

Insolvency and bankruptcy act summary

I hope you have enjoyed this insolvency and bankruptcy act Brandon’s Blog. Hopefully, you have better insight now into the fact that a sick insolvent company’s business can be saved by doing a sale of its assets to a healthy organization.

Do you or your company have too much debt? Are you or your company in need of financial restructuring? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or the person who has too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding bankruptcy. We can get you debt relief freedom.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a debt settlement plan, we know that we can help you.

We know that people facing financial problems need realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team.

That is why we can develop a restructuring process as unique as the financial problems and pain you are facing. If any of this sounds familiar to you and you are serious in finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation.

We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.


Categories
Brandon Blog Post

THE TORONTO CORONAVIRUS EXTRAORDINARY PLAN TO BUSINESS RECOVERY

The Ira Smith Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

Stay healthy, well balanced and safe and secure everyone.

[monkeytools msnip=”https://monkeyplayr.com/playr.php?u=5173&p=22255″]

Introduction

For businesses having a hard time enduring the Toronto coronavirus pandemic, insolvency may very well be the outcome. General insolvency filings were down in April, this is mainly because everyone has a built-in stay of proceedings right now.

Banks, credit card companies and collection agencies are not making a name for themselves right now during the Toronto coronavirus lockdown by harassing people who cannot afford to pay their regular monthly payment. However, that will not last too long.

In this Brandon’s Blog, I discuss options available to the entrepreneur if the Toronto coronavirus lockdown and quarantine wreaks havoc on your business.

Telltale signs from the United States

We have already seen the variety of companies that submitted to Chapter 11 insolvency. They did so in order to attempt to reorganize their financial obligations while trying to stay in business. This has been especially true for the large retail business sector. Their business problems were not caused by COVID-19. However, the pandemic merely accelerated where they were heading anyway.

The American Bankruptcy Institute reported that Chapter 11 filings in April 2020 represent a 26% boost from April 2019.

I have previously written about Modell’s Sporting Goods and Pier 1. Now we can add Neiman Marcus, JCPenney and J.Crew. Outside of the retail sector, Hertz Car Rental, Gold’s Gym, Foodora and Virgin Australia are also recent restructuring filings. I also really believe that it won’t be long before the floodgates open up to subject an excess of small firms looking for relief from their financial problems, in North America and the rest of the world. That is probably obvious to you, it really can’t be called a Toronto coronavirus news update!

Entrepreneurs are doing whatever they can

I have definitely noticed an uptick in telephone calls from people scared about their personal situation and from worried business owners in the past 4 weeks. They aren’t all set to throw in the towel right now. They are attempting to do whatever they can through the shutdown to stabilize their company. So for now, they are trying to take advantage of various federal government programs to help them stay afloat. The programs include:

However, the people I am talking to are also realists. They all understand that if what they are doing now doesn’t work, they will either have to try to restructure the company or have it go bankrupt. So for now, there is somewhat of a pause in remedies such as distraints, repossessions, terminations of leases and financial institution collections.

The moratorium won’t last forever

Right now the Canadian federal government is taking the lead. They have extended timelines for filing income tax and HST returns and paying amounts owing. They have also extended certain relief programs from their original expiration date of June 30. Right now, subject to a further extension, of course, it looks like the feds are shooting for September 30 to end the COVID-19 assistance programs.

Ultimately, the patience for non-payment being shown right now by landlords and creditors won’t last permanently. I expect business bankruptcy protection and bankruptcy filings to climb after the “all clear” is sounded on this Toronto coronavirus state of emergency and the government assistance ends. The pent up collection activity will go into full flight.

The floodgates will open. I expect one of the worst offenders to be the Canada Revenue Agency (CRA). There will be so many companies in default of their tax payment obligations. The government is spending trillions of dollars to prop up the Canadian economy. Those programs will have to be paid for and all the IOU’s will be called in.

It seems that everybody I have spoken with is simply waiting until this Toronto coronavirus period quiets down. The pool of business problems is overflowing right now.

Corporate bankruptcy is not the only option for a company battling its financial demons. There are going to be three categories of insolvent companies:

  1. Those who are too small and it just does not make sense for them to do anything other than paying the employees their final salary, wages and vacation pay. Then file their final corporate and income tax files. Then, turn the key in the door and walk away.
  2. A company that has just a few creditors and all or some of the business operations remains viable. They can negotiate with their creditors for a reduction in each amount owing on a creditor by creditor basis. The reason this does not work if there is a large group of creditors is because of human nature. Everyone is worried that the next person is getting a better deal. By the time you get the last person to say yes, the first person may have changed their mind. There is no way to independently satisfy all the creditors that nobody is getting a better deal. In reality, some are getting a better arrangement than others. It will be based on the negotiation ability of the creditor and how essential maintaining the supply of their product or service from them is.
  3. Businesses where all or some of their operations remain viable. However, the company can only survive if it can chop off the sick parts and eliminate however much debt they need to so that the newly restructured company is solvent.
  4. Companies with complex issues needing to assign their assets to a licensed insolvency trustee through a bankruptcy or whose secured creditor will enforce on their security by appointing a receiver, either a private receiver or court-appointed receiver.

Toronto coronavirus induced restructuring

If you anticipate your entire business or certain business units will remain viable but require relief from its creditors and debts, the first look at restructuring. This route enables a company to stay functioning while renegotiating its financial obligations. This process includes looking critically at all business units and determining how operations can be made more efficient in order to improve profitability. Many hard decisions will have to be made.

Companies have two choices in Canada for restructuring. For the larger restructurings, the kind that you read in the newspaper, the restructuring statute is the Companies’ Creditors Arrangement Act (Canada) (CCAA). In order to qualify for restructuring under the CCAA, the company has to owe its creditors at least $5 million.

All other companies restructure under the Bankruptcy and Insolvency Act (Canada) (BIA) restructuring provisions. It is called Part III Division I of the BIA. Regular readers of Brandon’s Blog will know that I have written several blogs before on aspects of both the CCAA and restructuring under the BIA.

In my blog, BANKRUPTCY EXPERTS WEIGH IN ON US & CDN SMALL BIZ RESTRUCTURING, I lamented the fact that the Canadian insolvency system does not have a streamlined restructuring process for smaller companies. We have the consumer proposal restructuring under the BIA for smaller personal insolvent debtors trying to restructure.

The United States has the Small Company Reorganization Act (SBRA) of 2019, also known as “Subchapter 5”. The SBRA is aimed at simplifying restructuring procedures for small companies by boosting efficiency, lowering costs, and easing the restructuring plan confirmation process. I believe this would be a great addition to the Canadian insolvency system. It may very well move some companies from my #1 category listed above into #3.

There is no sense dwelling any longer on what we don’t have. The Toronto coronavirus news today has affected so many companies. Many will just not survive. Others will be able to come out of the other side of this Toronto coronavirus pandemic but will need major surgery to stay alive.

The first step for any entrepreneur is to get professional advice in order to strategize and make a decision on what plan to put into place. You should speak either to a licensed insolvency trustee (formerly called a bankruptcy trustee) (Trustee) or a lawyer who has experience in insolvency matters.

Most licensed insolvency trustees will provide a one-hour no-cost strategy session.

You need to understand whether or not you have a viable business and company. Then, you need to have a sensible plan to increase your chances of success based on the viability analysis.

Both Ira and I have been doing many such strategy sessions over the telephone and video meeting since the Toronto coronavirus self-quarantine lockdown came into effect. I know that we will be doing many more as the city and the province begin to open up.

The goals of the entrepreneur have to be the driving force. For example, if the entrepreneur is adamant about staying in business, then you have to hope that business viability can be proven so that the likelihood of a successful restructuring is enhanced. On the other hand, if you can prove business viability but the entrepreneur has had enough and wants out, then you look at the restructuring and sale of the viable business parts.

Once viability is established, then a restructuring plan can be developed. The restructuring will take place either under the BIA or CCAA. Depending on the circumstances and the goals of the entrepreneur, either a refinancing of the restructured company of a sale of the business is part of any restructuring plan.

Business not viable

If the business is not viable, then pure restructuring is not possible. However, that does not mean that the assets that form the business unit cannot be used by someone else to efficiently run the business. I am not just talking about hard assets. Things such as patents, trademarks, processes, experienced workforce and the customer base before they go off to find a new supplier are all valuable parts of a business.

Perhaps the tangible and intangible assets can be sold to someone that can bring them into their existing operation and run the business profitably. Jobs can be saved also if this were to happen.

When this is the case, then you are into some form of liquidation. A secured creditor will move for the appointment of a receiver. As I have written before on this topic, the appointment can either be by way of a private appointment or an application to the court for a court-appointed receiver.

If there are no secured creditors, the security taken is invalid, or there are other factors that make a bankruptcy necessary, then the company can assign itself to bankruptcy. It isn’t every day you find this, but in a recent corporate bankruptcy filing that I am administering, I found that the security of the purported secured creditor was invalid as against us as Trustee.

Then either the receiver or Trustee can take possession of the assets, run a well-advertised and managed sales process and hopefully find a buyer for the assets to comprise all or many parts of the operating business. If such a buyer does not exist, then it will be a straight liquidation of individual assets. Obviously, higher values can be achieved when selling what amounts to a business rather than just individual assets in a liquidation.

Personal guarantees and director liabilities

In any corporate or business insolvency, the exposure of the directors has to be taken into consideration. This is not Toronto coronavirus news. It is normal for entrepreneurs to have to give a personal guarantee to a lender in addition to the security taken. Such a guarantee can be backed up by specific personal assets as collateral, or be an unsecured guarantee. Or, an entrepreneur has to indemnify the landlord as part of the corporation leasing premises.

Directors also have certain liabilities under provincial or federal law. Generally, directors will have personal liability for:

The exposure of directors must be recognized and taken into account in any restructuring attempt.

Toronto Coronavirus Summary

Businesses all over will look different due to the Toronto coronavirus pandemic and lockdown. The current environment is unprecedented and is teaching all of us things we have never seen before.

The Ira Smith Team family hopes that you and your family members are remaining secure, healthy and well-balanced. Our hearts go out to every person that has been affected either via misfortune or inconvenience.

We all must help each other to stop the spread of the coronavirus. Social distancing and self-quarantining are sacrifices that are not optional. Families are literally separated from each other. We look forward to the time when life can return to something near to typical and we can all be together once again.

Ira Smith Trustee & Receiver Inc. has constantly used clean, safe and secure ways in our professional firm and we continue to do so.

Revenue and cash flow shortages are critical issues facing entrepreneurs and their companies and businesses. This is especially true these days.

If anyone needs our assistance, or you just need some answers for questions that are bothering you, feel confident that Ira or Brandon can still assist you. During this Toronto coronavirus state of emergency, we are doing telephone consultations and/or virtual conferences that are readily available for anyone feeling the need to discuss their personal or company situation.


The Ira Smith Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

Stay healthy, well balanced and safe and secure everyone.

toronto coronavirus


Categories
Brandon Blog Post

REDWATER ALBERTA NEWS: $1.7B TO CLEAN UP ORPHANED WELLS DUE TO COVID-19

redwater albertaThe Ira Smith Team is absolutely operational and both Ira, as well as Brandon Smith, are right here for a telephone appointment, conference calls and also virtual meetings.

Stay healthy and safe everybody.

If you would prefer to listen to the audio version of this Brandon’s Blog, please scroll to the bottom of this page and click on the podcast

Introduction

When it went insolvent in 2015, Redwater Energy Corp. (Redwater Alberta or Redwater) might have been a small business, with only 19 generating wells and 90 dormant wells. However, a relatively small oil producer was responsible for a huge Supreme Court of Canada (SCC) decision.

Basically, the SCC decided in the Redwater Acase, that if a business goes belly up, its environmental obligation needs to be paid before secured creditors. I have written before on the Alberta Courts’ decisions and the SCC decision. As a result of COVID-19, the Canadian government just announced a $1.7 billion fund to create jobs in the Canadian oil patch.

Redwater Alberta history of cases

In my previous blogs, I described the Alberta court decisions. The Alberta Courts concurred with the receiver and held that the regulator’s enforcement activities to force Redwater’s adherence to its previously agreed requirements to clean up and permanently cap its oil site, in bankruptcy was not enforceable.

The Courts stated that given the bankruptcy of the company (in addition to a receivership), the Bankruptcy and Insolvency Act (Canada) (BIA) took paramountcy over the provincial law. The provincial Courts said that the BIA took paramountcy because:

  1. Allowed the receiver protection from the promises of Redwater Alberta as the licensee in connection with the Redwater properties disclaimed by the receiver/trustee, according to s. 14.06(4) of the BIA.
  2. The priority for the distribution of a bankrupt’s assets is regulated under the BIA, not provincial legislation. If the provable claim of the Regulator, an unsecured creditor, was paid in advance of the claims of Redwater’s secured creditors, that would not be the regime laid out in the BIA.

The SCC decision

In the SCC 5 to 2 judgment in the Orphan Well Association v. Grant Thornton Ltd. case, the SCC ruled that financially troubled companies like Redwater can no longer disclaim or merely bow out of properties they don’t want. In this situation, non-producing oil wells, when abandoned or orphaned, leave the resulting ecological cleaning to Alberta’s Orphan Well Association. It is a non-profit operating for the Alberta Energy Regulator.

What the SCC decision in the case of the Redwater Alberta receivership means is that the costs of properly and permanently sealing an oil well that is to be abandoned is a first ranking charge against the producer’s assets. In the Redwater case, the receiver had to turn over the proceeds (about $600,000) from the asset sales to the Alberta regulator. There was absolutely nothing left for any other creditor, either secured or unsecured.

This case was obviously difficult and contentious, given that it was a 5-2 decision and not unanimous. The majority decision stated that:

  • The regulator’s use of its provincial powers is not in conflict with the BIA to trigger the doctrine of federal paramountcy.
  • Section 14.06(4) of the BIA deals with the personal liability of receivers and trustees and does not let a trustee ignore the environmental liabilities of the estate.
  • The regulator is not asserting any claims provable in the bankruptcy.
  • There is no attempt by the regulator to upset the scheme of priorities stipulated by the BIA.
  • There is not a conflict by the regulator tagging the Redwater receiver as a licensee under Alberta legislation.

The Supreme Court decision goes on to say that the rules cannot be ignored just because there is a bankruptcy. Insolvency professionals must abide by valid provincial laws in administering corporate bankruptcy. It also found that receivers and trustees must:

  • conform with non-financial requirements the insolvent company must still adhere to that do not create a provable claim in the insolvency administration; and
  • Adhere to the parts of the provincial legislation that does not go against the BIA, notwithstanding that it might prove harmful to the position of one or more groups of creditors.

COVID-19 and orphaned wells

Near the end of March 2020, Finance Minister Bill Morneau said that help for the oil and gas industry would be announced. This industry has been hit by two different factors:

  1. Reduced demand due to people self-quarantining because of COVID-19 and therefore there is less demand for oil and gas.
  2. The price battle between Russia and Saudi Arabia. Oil on the world market is at an all-time low. At one point, a barrel of Canadian oil was selling for less than $5. The industry cannot operate with oil prices that low.

As a result, there have been massive job losses in British Columbia, Saskatchewan and Alberta oil patches. As well, the regulators do not have the money to reclaim and permanently seal off the abandoned orphaned wells. It is currently estimated that the total cost could be in the $8 billion range.

On Friday, April 17, Prime Minister Justin Trudeau announced that the federal government will invest at least $1.7 billion to the orphaned well cleanup. The money is to be used to create oil patch jobs to allow for the environmental cleanup.

So COVID-19 or coronavirus, has forced the Canadian government to create this support for the Canadian oil and gas industry. It will create jobs badly needed and allow for the cleanup of some orphaned oil wells.

Details of the support package have not been released. Presumably, the legislation will have to be drafted and passed in the House of Commons. No doubt, more information will come out in the coming days or weeks.

Summary

The Ira Smith Team family hopes that you and your family members are remaining secure, healthy and well-balanced. Our hearts go out to every person that has been affected either via misfortune or inconvenience.

We are all citizens of Canada and we need to coordinate our initiatives to stop the spread of the coronavirus. Social distancing and self-quarantining are sacrifices that are not optional. Families are literally separated from each other. We look forward to the time when life can return to something near to typical and we can all be together once again.

Ira Smith Trustee & Receiver Inc. has constantly use clean, safe and secure routines in our professional firm and we continue to do so.

Revenue and cash flow shortages are critical issues facing entrepreneurs and their companies and businesses.

If anyone needs our assistance, or you just need some answers for questions that are bothering you, feel confident that Ira or Brandon can still assist you. Telephone consultations and/or virtual conferences are readily available for anyone feeling the need to discuss their personal or company situation.

Are you now worried just how you or your business are going to survive? Those concerns are obviously on your mind. This pandemic situation has made everyone scared.

The Ira Smith Team understands these concerns. More significantly, we know the requirements of the business owner or the individual that has way too much financial debt. You are trying to manage these difficult financial problems and you are understandably anxious.

It is not your fault you can’t fix this problem on your own. The pandemic has thrown everyone a curveball. We have not been trained to deal with this. You have only been taught the old ways. The old ways do not work anymore. The Ira Smith Team makes use of new contemporary ways to get you out of your debt problems while avoiding bankruptcy. We can get you debt relief now.

We look at your whole circumstance and design a strategy that is as distinct as you are. We take the load off of your shoulders as part of the debt settlement strategy we will draft just for you.

We understand that people facing money problems require a lifeline. That is why we can establish a restructuring procedure for you and end the discomfort you feel.

Call us now for a no-cost consultation. We will listen to the unique issues facing you and provide you with practical and actionable ideas you can implement right away to end the pain points in your life, Starting Over, Starting Now.

The Ira Smith Team is absolutely operational and both Ira, as well as Brandon Smith, are right here for a telephone appointment, conference calls and also virtual meetings.

Stay healthy and safe everybody.

[monkeytools msnip=”https://monkeyplayr.com/playr.php?u=5173&p=22151″]

Categories
Brandon Blog Post

CORONAVIRUS SAFETY AND READINESS TIPS FOR YOU – VIDEO ***

coronavirus safety and readiness tips for you

[monkeytools msnip=”https://monkeyplayr.com/playr.php?u=5173&p=22048″]

I hope the coronavirus information in this video is helpful to you. During these difficult times, everyone is doing their part to limit the spread of this dangerous virus. Ira Smith Trustee & Receiver Inc. has always employed clean and safe habits in our professional practice and continues to do so.

If anyone needs our assistance and is unable to go out, either through self-quarantine measures or just general precautions, rest assured that Ira or Brandon can still help you. Telephone consultations and/or virtual meetings are available for anyone wanting to discuss their personal or corporate situation.

So hopefully these coronavirus safety tips are helpful to you. We are available to be of assistance to you.

Stay healthy my friends.

coronavirus safety and readiness tips for you


Coronavirus safety and readiness tips for you

Call a Trustee Now!