Categories
Brandon Blog Post

Financial Reorganization Services vs. Small Business Bankruptcy in Ontario: Which Is Undeniably Right for Your Company?


I hope you, your team and your business are safe and well. If your company is under financial pressure, please know that this situation is not a personal failure. Many capable business owners face periods when cash flow, debt and creditor demands become difficult to manage. Seeking advice early is an act of responsible stewardship, not a cause for shame.

When a business is in financial trouble, the instinctive question is often, “Is this bankruptcy?” The more useful first question is, “Is this business viable so that it can have a successful financial reorganization?” At Ira Smith Trustee & Receiver Inc., we help owners examine both possibilities calmly and practically so they can make informed decisions before their options narrow.

Reorganization Key Takeaways

  • Informal reorganization may provide the fastest and least expensive solution, but it depends on creditor co-operation and does not provide a legal stay of proceedings.
  • A Division I Proposal in Ontario is a formal reorganization process under the Bankruptcy and Insolvency Act that can allow a viable corporation to continue operating while compromising eligible debts.
  • Corporate bankruptcy generally involves the sale or liquidation of company assets and normally brings the company’s operations to an end unless a purchaser acquires the business assets in order to carry on the business in a new corporation.
  • A corporation’s insolvency does not automatically eliminate the owner’s personal exposure. Personal guarantees and certain director liabilities must be reviewed separately.
  • Early advice from your accountant and a Licensed Insolvency Trustee can help preserve lifelines that may not be available later.

Reorganization Highlights

Is this bankruptcy, or is it a reorganization?

Insolvency means a company cannot meet its obligations as they become due, and/or its assets are not sufficient to pay its liabilities. Insolvency does not always mean that the underlying business has no future.

A company may have loyal customers, valuable employees, a sound product and a realistic path to profitability, but still be overwhelmed by accumulated debt, rising costs or a temporary cash-flow crisis. In that situation, financial reorganization services may help separate a viable operating business from an unsustainable debt structure.

Bankruptcy is different. It is generally a liquidation process. The company’s assets are placed under the control of a Licensed Insolvency Trustee, realized or sold, and the proceeds are distributed to creditors according to the statutory priority rules.

The earlier we assess the facts, the more clearly we can distinguish a temporary cash-flow problem from a business model that is no longer viable. That distinction matters because reorganization works best when there is still something worth preserving.

What are financial reorganization services?

Financial reorganization services can include informal negotiations, formal proceedings or a combination of both. The right approach depends on the company’s cash flow, assets, operations, creditor relationships and future prospects.

Informal reorganization

An informal reorganization does not involve filing a formal proceeding under insolvency legislation. The company may negotiate directly, or with the assistance of an advisor, with:

  • Lenders and other secured creditors;
  • The Canada Revenue Agency;
  • Landlords;
  • Suppliers;
  • Employees and other stakeholders.

Possible arrangements may include revised payment terms, interest relief, a standstill, a rent deferral, a new financing arrangement or a negotiated settlement.

This is often the fastest and least expensive path. However, it depends on creditor goodwill. A creditor can generally change its position, continue collection activity or enforce its rights if no binding formal protection is in place. There is also no automatic legal stay of proceedings.

Informal reorganization can be an effective lifeline when creditors believe the company has a credible plan and the business communicates openly. It becomes much harder when negotiations begin only after enforcement has started.

Professionals reviewing a cash-flow forecast and strategic recovery plan for a financial reorganization

Reorganization: What does a Division I Proposal actually do for my company?

A Division I Proposal, also called a commercial proposal in Ontario, is a formal offer to creditors under Part III, Division I of the Bankruptcy and Insolvency Act. A corporation files the proposal through a Licensed Insolvency Trustee.

The proposal may offer creditors a portion of what they are owed, paid over time or through another arrangement. If it is accepted by creditors and approved by the court, the company may continue operating while completing the proposal.

A company may begin by filing a Notice of Intention to Make a Proposal. In general terms, this provides a period of protection while the company develops its proposal. A proposal can also be filed directly in appropriate circumstances.

The filing triggers an automatic stay of proceedings under the BIA. The relevant stay provisions include section 69(1) for a Notice of Intention and section 69.1 for a filed proposal. Subject to statutory exceptions and court orders, the stay generally halts collection activity, garnishments and most enforcement action against the company and its property.

Creditors vote on the proposal. In general, acceptance requires:

  • A majority in number of the voting unsecured creditors; and
  • At least two-thirds in value of the voting unsecured creditors.

Creditor approval is not the only step. The court must also approve, or sanction, the proposal before it becomes binding under the legislation.

A Division I Proposal can be a powerful option, but it is not risk-free. If creditors reject the proposal, the court fails to approve it, or if the proposal fails to proceed as required, usually because the company fails to perform the entire accepted and approved proposal, the company is generally deemed bankrupt. That is why the proposal must be based on realistic cash-flow forecasts rather than optimism alone.

The Companies’ Creditors Arrangement Act, or CCAA, is another reorganization tool. It is used for larger and more complex insolvencies, involving at least $5 million in debt, and is typically outside the reach of a small business. A Division I Proposal is more commonly considered for small and mid-sized Ontario corporations.

When is small business bankruptcy rather than financial reorganization in Ontario the more realistic answer?

Small business bankruptcy in Ontario may be appropriate when the underlying business is not viable, and there is no realistic path to stable operations.

In a corporate bankruptcy, the Licensed Insolvency Trustee takes control of the company’s assets, subject to the rights of secured creditors and other legal considerations. Assets may be sold individually or as an operating business. The proceeds are distributed to creditors according to the statutory priority order.

The company normally ceases operating as its own business. However, a purchaser may acquire some or all of the assets and continue the business in a new ownership structure. The outcome depends on the assets, contracts, employees, financing, market and available buyers.

Bankruptcy does not mean that the owner automatically loses everything personally. A corporation is a separate legal entity. However, the owner’s personal exposure is a separate and important question that must be examined carefully.

Organised financial documents and a practical reorganization checklist

Comparison of the main paths

DimensionInformal reorganizationBIA Division I ProposalCorporate bankruptcy
What it isDirect negotiations or an advisor-supported arrangement with creditors and stakeholders.A formal offer to compromise corporate debts under the Bankruptcy and Insolvency Act.A formal liquidation and realization process administered under the BIA.
Legal protectionNo automatic stay of proceedings. Protection depends on negotiated agreements.An automatic stay generally applies under the BIA, subject to statutory exceptions and court orders.A stay may apply in the bankruptcy, but the trustee administers the estate and realizes assets for creditors.
Who approves or controls it?The company and participating creditors negotiate the terms.Creditors vote, and court approval is required. A Licensed Insolvency Trustee administers the process.A Licensed Insolvency Trustee administers the estate, subject to the BIA and creditor and court processes where applicable.
What happens to the business?The company continues if negotiations succeed and cash flow can be stabilised.The company may continue operating while completing the approved proposal.The company generally stops operating unless assets or the business are sold to a purchaser.
Typical cost and timelineUsually the least expensive and fastest, but highly dependent on creditor co-operation.More formal, with professional, filing and court-related costs; timing varies with complexity.Costs and timing depend on the assets, claims, investigations, litigation and distribution process.
Who it generally suitsA business with a credible plan and creditors willing to co-operate.A viable or potentially viable business needing legal protection and a formal compromise of debt.A business with no realistic reorganization path or where liquidation is the most responsible outcome.

CCAA proceedings are a separate, court-supervised reorganization regime generally used for larger companies that meet the statutory requirements, commonly including at least $5 million in debt.

Reorganization: Could I be personally liable for company debt?

This is one of the most important questions for an owner. Corporate insolvency and personal insolvency are not the same thing.

Personal exposure may arise from:

  • Personal guarantees given to banks, equipment financiers, landlords or suppliers;
  • Joint debts or co-signed obligations;
  • Director liability for certain unremitted source deductions under the Income Tax Act;
  • Director liability for certain amounts owing under the Excise Tax Act, including some HST obligations;
  • Other statutory obligations that may survive the corporation’s insolvency.

A corporate reorganization may therefore need to be coordinated with a personal solution for the owner. Depending on the facts, that could include a consumer proposal or another personal insolvency option.

Do not assume that incorporating your business eliminates every personal risk. Do not assume that a personal guarantee will disappear because the company files. We recommend reviewing guarantees, tax accounts, shareholder loans and personal assets with your accountant and a Licensed Insolvency Trustee before taking further steps.

Which option may fit my business?

Reorganization may fit better when:

  • The business has positive cash flow or a credible plan to reach it;
  • Key customers, contracts and revenue remain intact;
  • The core products or services are commercially sound and sought after;
  • Employees and management can continue operating the business;
  • Creditors are likely to support a reasonable plan.

Bankruptcy may be the more honest answer when:

  • The company is losing money with no credible turnaround plan;
  • The owner is funding ongoing losses with personal savings or credit;
  • Major customers or revenue sources have disappeared;
  • The business cannot maintain payroll, taxes or essential suppliers;
  • Creditor support is unrealistic.

The goal is not to preserve a business at any cost. The goal is to make a responsible decision that protects value, reduces uncertainty and gives the owner a path forward based on business viability.

Reorganization: What warning signs should I not ignore?

Please seek advice promptly if your company:

  • Cannot pay payroll or source deductions on time;
  • Uses HST collected from customers and employee source deductions to fund operations;
  • Has maxed-out revolving credit or a lender that has stopped advancing funds;
  • Has received a CRA demand, requirement to pay or garnishment;
  • Is being moved to cash-on-delivery terms or cut off by suppliers;
  • Faces a landlord’s threat of distress or lease termination;
  • Is losing key employees because of financial uncertainty; or
  • Has received demands under personal guarantees.

These signs do not automatically determine the answer. They do indicate that time is running out and the company’s options should be assessed now rather than later.

Reorganization: What should I do if my company may be in trouble?

I suggest the following general steps:

  1. Gather the records. Assemble current financial statements, bank statements, tax filings, aged receivables and payables, loan documents, leases, payroll records and creditor correspondence.
  2. Understand the real numbers. Prepare a realistic short-term cash-flow forecast. Identify what must be paid to keep the business operating and what debts are already overdue.
  3. Speak with your accountant. Your accountant can help assess profitability, tax reporting, working capital and whether the operating business is fundamentally viable.
  4. Consult a Licensed Insolvency Trustee early. A trustee can explain informal reorganization, a Division I Proposal, bankruptcy and the potential consequences of each.
  5. Review personal exposure. Identify every personal guarantee, shareholder loan, tax obligation and jointly held asset.
  6. Be cautious with personal funds. Before using personal savings, credit cards or a second mortgage to fund ongoing losses, obtain advice about whether that money is likely to change the outcome.

Taking these steps does not commit you to bankruptcy. It gives you information. Information restores control.

Reorganization Frequently Asked Questions (FAQ)

Can I file bankruptcy and keep my business?

A corporation can technically continue operating in limited circumstances, but corporate bankruptcy generally involves the trustee realizing on company assets and the business ceasing as the existing legal entity. A purchaser may acquire the assets and continue operations. The answer depends on the company’s structure, assets, contracts and creditor rights.

Does bankruptcy personally wipe out my guarantees?

No. A company’s bankruptcy does not automatically eliminate personal guarantees. The lender or supplier may pursue the guarantor according to the guarantee and applicable law. Personal exposure should be reviewed separately.

What happens if creditors reject my proposal?

A rejected Division I Proposal results in the company being deemed bankrupt. There are important procedural and legal details, so the proposal process should be planned carefully with a Licensed Insolvency Trustee.

Can I reorganize CRA debt?

Some CRA debts may be addressed through a formal proposal, but tax debts can involve trust claims, director liability and other statutory issues. Do not assume that all CRA debt is treated the same way. Obtain advice based on the company’s tax accounts and payment history.

Will my employees be paid?

Payroll obligations should be assessed immediately. In a bankruptcy or receivership, eligible employees may have claims under the Wage Earner Protection Program, subject to its rules and limits. A trustee can explain the process, but owners should not delay addressing unpaid wages or source deductions.

How long does the process take?

There is no single answer. Informal negotiations may move quickly, while a Division I Proposal involves preparation, creditor voting and court approval. Bankruptcy timelines depend on the company’s assets, claims, investigations, litigation and distribution issues.

Should I wait until a creditor sues?

Usually, no. Waiting may reduce the available options and make an orderly reorganization more difficult. Early advice is not an admission of defeat. It is good business judgment.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future, call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

————————––

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

IRA SMITH is President of Ira Smith Trustee & Receiver Inc., a CPA CA and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors and professionals. Ira and Brandon Smith stay current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.Business owner and financial advisor reviewing reorganization options in a Toronto office

#FinancialReorganization #Reorganization #SmallBusinessBankruptcy #OntarioBusiness #CorporateReorganization #DivisionIProposal #BusinessDebt #InsolvencyAdvice #GTAEntrepreneurs #StartingOverStartingNow

Categories
Brandon Blog Post

Toronto Business Closures Are Surging: Why BMO’s Per-Capita Insolvency Argument Misses the Bigger Picture

Two professionals reviewing a cash flow forecast and strategic restructuring plan for a Toronto business

I hope you, your family, and your Toronto business are safe and managing as well as possible in a difficult economic environment. If you are a GTA business owner watching sales weaken, costs rise, or creditors become more persistent, you are not alone, and asking for help early is not a sign of failure. It is a practical step towards regaining control.

The latest Toronto business and Canadian insolvency data tell a complicated story. New businesses continue to open, but an unusually large number are also closing. At the same time, formal insolvency filings are rising, while many households and businesses may be managing distress outside the formal insolvency system.

Toronto Business: Key Takeaways

  • The Toronto Census Metropolitan Area (CMA) recorded approximately 10,870 Toronto business openings in April 2026, the highest April level in at least 11 years.
  • Toronto also recorded approximately 10,720 Toronto business closures, the second-highest April total on record, behind only April 2020.
  • Active businesses fell to 187,700 in April 2026, marking a seventh consecutive monthly decline and the lowest level since June 2022.
  • Canada recorded 13,254 insolvency filings in June 2026, up 11.5% year over year and more than double the June 2020 volume.
  • BMO Capital Markets’ per-capita analysis provides one useful perspective. Still, it does not capture who has access to credit, who is filing, or how many businesses and households are struggling without filing.
  • For Toronto business owners, early advice from an accountant and a Licensed Insolvency Trustee can preserve more restructuring options.

Toronto Business: Highlights

Toronto Business: What is Toronto business data telling us?

The Toronto CMA is experiencing both entrepreneurial activity and business contraction at the same time.

According to Better Dwelling’s August 5, 2026 report, approximately 10,870 businesses opened in April 2026. That was the most openings recorded for an April in at least 11 years.

That might sound encouraging. It is.

However, approximately 10,720 businesses also closed during the month. This was the second-highest April closure total on record, surpassed only by April 2020, when pandemic lockdowns disrupted the economy.

The result is a high-churn environment. Toronto business churn means businesses are opening and closing at an unusually rapid rate. Churn can reflect innovation and opportunity, but it can also indicate that owners are entering markets without enough financial cushion to withstand weaker demand, higher operating costs, tighter credit, or delayed customer payments.

The number of active businesses in the Toronto CMA fell to 187,700 in April 2026. This was the seventh consecutive monthly decline. The active Toronto business count was down approximately 0.9% year over year and at its lowest level since June 2022, nearly a four-year low.

This is the real-world business story behind the headline. Toronto is not simply seeing fewer businesses. It is seeing significant movement in both directions, while the total base of active businesses continues to shrink.

Business professionals reviewing positive and negative cash flow Toronto business projections during a restructuring discussion

Toronto Business: Why is BMO’s per-capita argument incomplete?

BMO Capital Markets senior economist Robert Kavcic has offered a perspective that deserves to be understood fairly.

As reported by Better Dwelling on August 13, 2026, Mr. Kavcic acknowledged that consumer insolvencies were near the highest level since the 2009 recession. His argument was that, after adjusting for Canada’s population growth, insolvencies had “basically just normalized back to pre-pandemic conditions.”

He concluded that “the real story is that there is really no story.”

A per-capita measure, a calculation that divides a total by the size of the population, can be useful. It can help compare conditions across different time periods when the population has changed. BMO is right that raw totals do not tell the entire story.

The difficulty is that population growth does not necessarily equal comparable growth in credit exposure.

Better Dwelling reported that approximately 40% of Canada’s population growth over the past five years came from non-permanent residents, including temporary workers and international students. These groups typically have more limited access to unsecured credit, the type of credit that does not require collateral.

That matters because consumer insolvency filers often have an established borrowing history. According to the Office of the Superintendent of Bankruptcy data cited by Better Dwelling, 57% of consumer insolvency filers in 2024 had a bank loan, with a median value of approximately $20,000. In addition, one in five filers had filed before.

This profile does not necessarily match the typical non-permanent resident. Therefore, using total population as the denominator may dilute the apparent rate of insolvency without accurately measuring the financial stress among established borrowers.

The broader lesson is not that per-capita statistics are useless. The lesson is that they must be qualified. A business owner, lender, policymaker, or household needs to know not only how many people live in Canada, but also who is borrowing, who is falling behind, and who is taking formal action.

The June 2026 figures remain significant. Canada recorded 13,254 insolvency filings, an 11.5% increase from June 2025 and more than double the June 2020 volume. Only June 2009 recorded more filings. The trailing 12-month total reached approximately 150,505 filings, up 5.3% year over year.

Those numbers do not prove that every household or Toronto business is in crisis. They do show that financial distress is material and deserves more than a single reassuring ratio.

Toronto Business: What kinds of financial distress are being missed?

Raw insolvency counts and per-capita ratios can both understate the pressure facing the economy because they capture only part of the problem.

There are at least three different forms of financial distress:

Form of distressWhat it isHow it appears in the dataWhy it matters to a business owner
Formal insolvency filingA bankruptcy or proposal filed under Canada’s insolvency legislation. A proposal is a formal arrangement intended to compromise or restructure debts.It appears in official insolvency statistics reported by the OSB.It may provide legal protection and a structured path forward, but waiting too long can reduce available options.
Silent business closureA business stops operating, winds down, or does not renew operations without making a formal insolvency filing.It appears in business-opening and business-closure data, but not necessarily in insolvency statistics.Suppliers, employees, landlords, and customers may still be affected. The owner may also remain personally exposed through guarantees or other obligations.
Household debt stressA household manages financial pressure through arrears, refinancing, payment deferrals, or high-interest credit without filing an insolvency proceeding.It may appear indirectly in arrears or credit data and may not appear in formal insolvency counts for months or years.Household stress can reduce consumer spending, delay business payments, and weaken the customer base on which a business depends.

Insolvency is also a lagging indicator. That means a formal filing often occurs after months or years of financial deterioration. Before filing, a business may have used savings, borrowed from family, increased credit-card balances, refinanced assets, delayed tax remittances, or negotiated informal payment arrangements.

By the time the filing appears in the statistics, the underlying financial pressure may already be much more severe.

This is why a Toronto business owner should not wait for a formal insolvency number, or a missed payment, to decide whether advice is necessary. Early advice is about information, not commitment.

Toronto Business: What does this mean for GTA business owners?

For a GTA business owner, the important question is not whether the economy is technically “normal” on a per-capita basis. The important questions are more immediate:

  • Are sales sufficient to cover operating costs?
  • Are customers paying more slowly?
  • Are supplier terms becoming stricter?
  • Are tax arrears accumulating?
  • Are loan renewals or refinancing becoming more difficult?
  • Have you used personal credit to support the company?
  • Have you signed personal guarantees for corporate borrowing or leases?
  • Is the Toronto business profitable before debt payments, but unable to meet its total obligations?

A company can be viable, meaning it has a fundamentally workable business model, while still being financially unsound because of accumulated debt, temporary cash-flow disruption, or an unsustainable repayment schedule.

That distinction is important. A viable company may have restructuring options that disappear if the owner waits until assets are seized, key employees leave, or critical suppliers stop extending credit.

A corporate restructuring plan may involve negotiating with creditors, changing payment terms, selling non-core assets, reducing expenses, or using a formal proposal. A commercial proposal, sometimes called a Division I Proposal, is a legal process that can allow a financially troubled but viable company to compromise debts and continue operating, subject to the required approvals.

The right solution depends on the company’s structure, assets, liabilities, cash flow, tax position, employees, secured lenders, and personal guarantees. There is no universal answer.

Businessperson protected by a shield representing a Toronto business director protection and early insolvency advice

Toronto Business: What should a worried business owner do now?

If you are concerned about your GTA or City of Toronto business, I recommend taking these steps:

  1. Prepare a current cash-flow forecast.
    List expected sales receipts, payroll, rent, taxes, loan payments, supplier obligations, and other essential expenses. A cash-flow forecast is a practical estimate of money coming in and going out over a defined period.
  2. Speak with your accountant early.
    Your accountant can help identify profitability problems, tax obligations, cash-flow gaps, and whether the business can realistically recover under its current structure.
  3. Consult a Licensed Insolvency Trustee.
    A Licensed Insolvency Trustee can explain formal options, including a proposal or bankruptcy, and help distinguish between corporate obligations and your personal exposure.
  4. Review personal guarantees and director liability.
    If you personally guaranteed a corporate loan, lease, credit facility, or supplier account, the corporation’s financial problems may affect you directly. Certain tax and payroll obligations can also create potential director exposure. Obtain professional advice before transferring assets, repaying selected creditors, or closing the company.
  5. Assess whether the core business is viable.
    Ask whether the company can generate positive operating cash flow after a realistic restructuring of its debt and costs. If the answer is yes, a restructuring proposal may be a lifeline. If not, an orderly wind-down may be more appropriate.
  6. Act before the crisis becomes irreversible.
    Early action does not mean you have decided to file. It means you are preserving information, time, credibility, and options.

We know the tension placed upon Toronto business owners and their families. It is not your hope, commitment, or personal worth that these statistics measure. Financial distress is a business problem that requires a business solution.

For additional context, our discussion of commercial proposals and corporate restructuring explains how a formal proposal may help a viable company continue operations. Our article on personal bankruptcy also discusses why a corporation and its owner must be assessed separately.

Toronto Business: Frequently Asked Questions (FAQ)

Are Toronto’s business closures the same as business insolvencies?

No. A business closure means an operation has stopped or ceased to be active. It does not necessarily mean the business filed a bankruptcy or proposal. Some businesses close quietly, while others may restructure informally or continue under a different ownership or operating model.

Does BMO’s per-capita analysis have value?

Yes. Per-capita analysis can help account for population changes. The concern is relying on it alone. It may not reflect differences in credit access, borrowing behaviour, business exposure, or the number of people experiencing stress without filing.

Why are insolvency filings considered a lagging indicator?

A formal insolvency filing often follows a long period of missed payments, borrowing, refinancing, arrears, or attempts to negotiate with creditors. The filing is usually evidence that earlier coping strategies have stopped working.

Should I wait until my business misses a payment before seeking advice?

No. Early advice is generally more useful because it allows you to understand your options before creditors take enforcement action, suppliers withdraw terms, or essential assets become unavailable. A consultation does not obligate you to file.

Can a business owner be personally responsible for corporate debt?

Possibly. Personal guarantees, the legal structure of the business, and certain tax or payroll obligations can create personal exposure. This is fact-specific, so speak with your accountant and a Licensed Insolvency Trustee before making major financial decisions.

Is a proposal the same as bankruptcy?

No. A proposal is a formal arrangement to compromise or restructure debts, while bankruptcy is a separate legal process. Whether a proposal is appropriate depends on the company’s viability, assets, liabilities, cash flow, and creditor situation.

The message for Toronto and the GTA is balanced but clear: new businesses are still being created, but active businesses are declining, closures are elevated, and formal insolvency filings are rising. That is a story worth paying attention to, not to create panic, but to encourage timely, informed action.

Source note: Statistics and quotations in this article are based on the two Better Dwelling reports published on August 5, 2026, and August 13, 2026. The underlying Statistics Canada and Office of the Superintendent of Bankruptcy data are attributed as reported by Better Dwelling. BMO’s position is attributed to BMO Capital Markets senior economist Robert Kavcic.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future; call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Ira Smith is President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Ira stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.Image of a worried business owner as Toronto business closures are increasing in 2026

#TorontoBusiness #GTABusiness #BusinessClosures #CorporateRestructuring #BusinessInsolvency #DebtRestructuring #CommercialProposal #DivisionIProposal #BusinessBankruptcy #FinancialDistress #LicensedInsolvencyTrustee #StartingOverStartingNow
Categories
Brandon Blog Post

The Prince Harry Effect: How Lifestyle Creep Tanks Even Royal-Sized Fortunes

A concerned high-earner in a Toronto office facing financial stress just like Prince Harry

At Ira Smith Trustee & Receiver Inc., we hope you are safe, well, and in good spirits. We understand that financial stress does not discriminate based on your bank balance or your social standing. Just look at the recently reported Prince Harry financial problems, which we discuss below.

Whether you are navigating the complexities of a family budget or managing a high-net-worth portfolio, the pressure of mounting debt can be overwhelming. We are here to tell you that there is always a path forward, and you do not have to walk it alone.

Prince Harry Key Takeaways

  • Definition: Lifestyle creep (or lifestyle inflation) occurs when your spending increases at the same rate as, or faster than, your income.
  • The Royal Hook: The recently reported financial struggles of Prince Harry serve as a warning that even multi-million dollar inheritances can be depleted by high fixed costs and a lack of sustainable income.
  • GTA Vulnerability: Toronto high-earners, including Bay Street executives and tech founders, are particularly susceptible due to the high cost of maintaining status and “Golden Cage” debt.
  • The Solution: For those with debts exceeding $250,000, a Division I Proposal offers a legal mechanism to restructure debt, protect assets, and preserve professional reputation.
  • Professional Support: Consulting a Licensed Insolvency Trustee is the first step toward “Starting Over, Starting Now.”

Highlights


What is Lifestyle Creep?

In the world of financial restructuring, we often encounter a phenomenon known as lifestyle creep. Simply put, it is the tendency for discretionary spending to increase as your income rises. What were once considered “luxuries”, such as first-class travel, private schooling, or a secondary property in Muskoka, gradually become baseline expectations.

This process is often invisible. It doesn’t happen overnight; it happens with every promotion, every successful exit, and every year-end bonus. The danger is that these upgrades often come with permanent, high-fixed costs. When your income is high, these costs are manageable. However, if that income stream is interrupted by a market downturn, a failed business venture, or a legal battle, the lifestyle remains, but the means to support it vanishes.

The Prince Harry Cautionary Tale

Recent news reports have highlighted the precarious financial situation of Prince Harry and Meghan Markle. Despite a combined fortune once estimated at upwards of $60 million, fueled by inheritances from Princess Diana and the Queen Mother, alongside lucrative media deals, insiders suggest they are facing a “humiliating bankruptcy.”

How does a Prince “blow through” $60 million? The answer lies in the burn rate. Between a $14.5 million Montecito mansion (with a substantial mortgage), a $4 million annual bill for private security, and mounting legal fees from high-profile court cases, the couple’s expenses have allegedly outpaced their income.

This is the “Prince Harry Problem”: relying on finite assets (inheritances) to fund an infinite, high-luxury lifestyle without a consistent, high-yield “occupation” or business model to replenish the coffers. Reports suggest this could lead to a Prince Harry bankruptcy.

A businessman waist-deep in water, symbolizing overwhelming debt, just like Prince Harry

Why GTA High-Earners Face Unique Risks

In the Greater Toronto Area (GTA), the pressure to maintain a certain standard of living is intense. Whether you are a partner at a top-tier law firm, a high-performing Realtor, or a professional athlete, the “Toronto Trap” is real. These factors can all contribute to someone having a Prince Harry Problem.

  1. Housing Concentration: In Toronto, home value is often a stronger predictor of consumption than actual net worth. An oversized mortgage on a Bridle Path or Rosedale home isn’t just a monthly payment; it’s a gateway to higher taxes, maintenance, and social expectations.
  2. Status-Driven Consumption: The need to “keep up” with the ultra-rich in one’s social circle leads to lifestyle inflation. This includes club memberships, luxury vehicle leases, and expensive philanthropic commitments that are hard to scale back without “losing face.”
  3. Variable Income: Many high-earners in the GTA rely on bonuses, commissions, or stock options. When these fluctuate, but the lifestyle costs remain fixed, the gap is often filled with high-interest consumer credit.

The “Golden Cage” of High-Net-Worth Debt

We often refer to this as the “Golden Cage.” You have the appearance of wealth, the cars, the home, the designer wardrobe, but you are trapped by the debt required to maintain it. For many, the stress is compounded by the fear of professional repercussions. If the board of directors or your clients find out about your Prince Harry Problem of financial instability, will it damage your career?

This fear often prevents high-earners from seeking help until the situation is catastrophic. At Ira Smith Trustee & Receiver Inc., we know the tension put upon you. We provide a compassionate, confidential environment where we focus on solutions, not judgment.

Division I Proposals: The Lifeline for High-Earners

If you find yourself in a Prince Harry Problem situation where your debts (excluding the mortgage on your principal residence) exceed $250,000, a standard Consumer Proposal is not an option. Instead, you must look toward a Division I Proposal.

A Division I Proposal is a formal procedure under the Bankruptcy and Insolvency Act (BIA) that allows an individual to make a settlement offer to their creditors.

Why it works for High-Earners:

  • Asset Protection: Unlike bankruptcy, where certain assets may be liquidated, a proposal allows you to keep your assets (such as your home or professional practice) while paying creditors a portion of what is owed over time.
  • Reputation Management: While it is a public record, a proposal is viewed far more favourably than a bankruptcy. It shows a proactive attempt to honour your obligations.
  • Immediate Stay of Proceedings: Once filed, all legal actions and collection efforts stop immediately, giving you the breathing room to restructure your life.

Two professionals reviewing a debt restructuring strategy for Prince Harry

Healthy Planning vs. Lifestyle Creep Warning Signs

FeatureHealthy Financial PlanningLifestyle Creep Warning Signs
Income IncreaseAt least 50% of any raise goes to savings or debt.100% of the raise is absorbed by new recurring bills.
Fixed CostsHousing and car payments stay below 30% of income.Fixed costs exceed 50% of monthly take-home pay.
Credit UsageCredit cards are paid in full every month.Carrying balances to fund ‘standard’ living expenses.
Emergency Fund6–12 months of expenses held in liquid assets.Less than 1 month of cushion; relying on a Line of Credit.
Savings RateIncreases proportionally with income growth.Savings rate remains flat or decreases as you earn more.

Frequently Asked Questions (FAQ)

What is the main difference between a Consumer Proposal and a Division I Proposal?

The primary difference is the debt threshold. A Consumer Proposal is for individuals with total debts (excluding their mortgage) under $250,000. If your debt exceeds this amount, you must file a Division I Proposal. The rules for approval are also stricter in a Division I Proposal, requiring a higher percentage of creditor support.

Will my employer or business partners find out?

Generally, there is no requirement to notify your employer. However, if your professional body (e.g., Law Society, CPA Ontario) has specific bylaws regarding insolvency filings, you may have a duty to report. We can help you navigate these specific professional requirements.

Can I keep my house and car?

In most proposals, yes. The goal is to negotiate a payment plan that satisfies your creditors without forcing the sale of your primary residence or essential vehicles, provided you can continue to make the secured payments (mortgage/lease).

How does “financial crisis management” help me?

Financial crisis management is about more than just filing paperwork. It involves a holistic review of your cash flow, identifying the “leakage” in your lifestyle, and creating a sustainable plan that restores your quality of life while satisfying legal obligations.

Breaking the Chains of Debt

The path back to financial stability begins with a single, courageous step. Whether you are facing a “Prince Harry” level of exposure or simply feel the weight of Toronto’s high cost of living pressing down on you, remember: it is not your fault that the economic landscape shifted. It is, however, within your power to take control.

By addressing lifestyle creep head-on and utilizing tools like the Division I Proposal, you can transition from the “Golden Cage” to true financial freedom.

Steel chains shattering against a white background, symbolizing freedom from debt that hopefully Prince Harry will find

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future, call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Brandon stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.

#LifestyleCreep #FinancialRestructuring #TorontoRealEstate #DebtRelief #PrinceHarry #InsolvencyOntario #DivisionIProposal #IraSmithTrustee #PrinceHarryfinancialproblems #PrinceHarrybankruptcy #StartingOverStartingNow #DebtFree #TorontoLife #WealthManagement #FinancialFreedom #ProfessionalAdvice
Categories
Brandon Blog Post

The Honda Alliston EV Retreat: How Ontario Auto Parts Suppliers Can Survive Vehicle Manufacturer Rollbacks

The EV Retreat: How Ontario Auto Parts Suppliers Can Survive the Honda Alliston Shelving

Honda Alliston Introduction

At Ira Smith Trustee & Receiver Inc., we understand that the health of Ontario’s manufacturing sector isn’t just about numbers on a balance sheet; it’s about the livelihoods of thousands of families across the Greater Toronto Area and beyond. If your business is feeling the weight of recent industry shifts, please know that we are here to support you with clarity and compassion. You are not alone in this, and there is a path forward.

The most obvious recent example is in the auto parts sector. Ontario was still reeling from the GM and Stellantis production rollback announcements due to the tariffs when, just 4 days ago, on May 14, 2026, Honda Global CEO Toshihiro Mibe released a statement in Tokyo. He announced the indefinite suspension of the Honda Alliston EV plant due to changing market conditions, slowing EV demand and a shift in the company’s global strategy.

Honda Alliston Key Takeaways

  • The Honda Impact: The shelving of the $15 billion EV battery project in Alliston has left many Tier-2 and Tier-3 suppliers with significant “stranded” debt and idle capacity.
  • Restructuring as a Lifeline: Tools like the BIA Division 1 Proposal and CCAA are designed specifically to protect businesses from creditors while they reorganize.
  • Immediate Action is Vital: Identifying insolvency solutions for GTA manufacturers early can prevent the total loss of a business and protect directors from personal liability.
  • Starting Over, Starting Now: Our philosophy focuses on practical decision-making to restore your control and quality of life.

Honda Alliston Highlights

  • The Ripple Effect: Why the Honda Alliston Shift Matters
  • The Financial Squeeze: Tooling, Debt, and Idle Lines
  • How to Restructure a Business Under the BIA
  • CCAA: Protection for Larger Operations
  • Comparison: BIA vs. CCAA for Manufacturers
  • Protecting the Directors: Avoiding the Personal Fallout
  • Frequently Asked Questions (FAQ)

The Ripple Effect: Why the Honda Alliston Shift Matters

The announcement that Honda is indefinitely shelving its massive EV and battery complex in Alliston, Ontario, has sent a shockwave through the provincial supply chain. What was meant to be a $15 billion cornerstone of Canada’s green economy is now on hold, cited as a casualty of flagging consumer demand and shifting trade policies.

For many local manufacturers, this isn’t just news, it’s a crisis. You may have invested in specialized machinery, hired staff in anticipation of long-term contracts, or taken on significant debt to meet “Just-In-Time” requirements for a project that has now vanished. When the “anchor” plant retreats, the smaller links in the chain are often the ones that feel the most strain.

The Financial Squeeze: Tooling, Debt, and Idle Lines

Many auto parts suppliers operate on thin margins. The shelving of a major project like Honda Alliston creates a “double whammy”:

  1. Stranded Capital: Money tied up in specialized tooling and equipment that cannot be easily repurposed for hybrid or internal combustion engine (ICE) lines.
  2. Contractual Void: The sudden disappearance of forecasted revenue makes it nearly impossible to service the debt incurred to scale up.

If you find yourself in a “Honda Alliston” position, you might be facing pressure from your bank or equipment lessors. This is where a Vaughan Debt Relief Specialist can step in to provide a buffer between you and your creditors.

Breaking the chains of debt

Honda Alliston: How to Restructure a Business Under the BIA?

When a corporation can no longer meet its financial obligations, it is considered insolvent. However, insolvency does not have to mean the end of the road. One of the most effective tools available is a Division 1 Proposal under the Bankruptcy and Insolvency Act (BIA).

A Division 1 Proposal is a formal offer made to your creditors to pay back a percentage of what is owed over time, or to restructure the terms of the debt. The moment we file a “Notice of Intention” to make a proposal, a Stay of Proceedings is put in place. This is a legal “shield” that stops all lawsuits, equipment seizures, and collection efforts immediately, giving you the breathing room to stabilize your operations.

Honda Alliston: CCAA Protection for Larger Operations

For larger manufacturers, typically those with more than $5 million in debt, the Companies’ Creditors Arrangement Act (CCAA) offers an even more flexible restructuring framework.

CCAA is a court-supervised process that allows a company to remain in control of its operations (as a “debtor-in-possession”) while it works out a plan to survive. It is particularly useful for complex auto suppliers who need to renegotiate multiple supply contracts or deal with international cross-border issues.

Comparison: BIA vs. CCAA for Manufacturers

Choosing the right path depends on the size and complexity of your manufacturing firm.

FeatureBIA Division 1 ProposalCCAA (Restructuring)
Debt ThresholdNo minimum (typically for SMEs)Minimum $5 million total debt
Initial StayAutomatic 30-day stay of proceedings10-day initial stay (extendable)
Court InvolvementModerate (standardized forms)High (requires court appearances)
ControlDirectors stay in controlDirectors stay in control (monitored)
SpeedGenerally faster and less expensiveHighly customized but more costly

Protecting the Directors: Avoiding the Personal Fallout

We know the tension put upon you as a business owner. Beyond the company’s survival, you are likely worried about your personal assets. In Ontario, directors can be held personally liable for certain corporate debts, such as unpaid HST or source deductions (payroll taxes).

If an event like the Honda Alliston shelving has caused a cash flow crisis that prevents you from making these payments, you must act quickly. Filing a restructuring proposal can often stop the clock on these liabilities and prevent the CRA from coming after your personal home or savings. We recently discussed the importance of D&O Insurance and Director Liability, which is a critical read for anyone in this position.

Why Choose Ira Smith Trustee & Receiver Inc.?

We don’t just see balance sheets; we see people. Our “Starting Over, Starting Now” philosophy means we focus on the solution, not the blame. Whether you are dealing with mortgage default concerns due to business stress or need a comprehensive plan for your factory, we provide the expertise of a Licensed Insolvency Trustee with the empathy of a trusted guide.

Honda Alliston: Frequently Asked Questions (FAQ)

1. Can we keep operating while we restructure?
Yes. Both a Division 1 Proposal and CCAA are designed to keep the “lights on” so the business remains a viable going concern.

2. Will my customers find out?
Restructuring is a public process, but for auto suppliers, it often signals to your customers (the OEMs) that you are taking responsible steps to ensure your long-term stability and ability to fulfill future contracts.

3. What happens to the specialized EV tooling we bought?
In a restructuring, we can look at “disclaiming” or renegotiating leases on equipment that is no longer useful due to the project being shelved.

4. Is it too late if I’ve already received a demand letter from the bank?
It is rarely too late to start the conversation, but your options are most numerous when you act before a Receiver is appointed.


Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today. Remember, it is not your fault. Events like the Honda Alliston indefinite suspension are outside of your control and happen in business all the time.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future, call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Brandon stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.A split-screen image for a blog about the Honda Alliston EV retreat. The left side shows a factory worker’s hands holding a wrench over an auto parts assembly line. The right side features Brandon Smith, Licensed Insolvency Trustee, in a suit, in front of a factory background with a sign reading 'Honda Alliston EV Plant - Initiative on Hold'. Bold text at the top reads 'Honda Alliston EV Retreat: Your Survival Guide'. An Ira Smith Trustee & Receiver Inc. logo is in the bottom right corner.

#AutoIndustry #OntarioManufacturing #DebtRelief #Insolvency #BusinessRestructuring #HondaAlliston #BIA #CCAA #IraSmithInc

Categories
Brandon Blog Post

OUR ONTARIO LAWYER COMPREHENSIVE GUIDE IF FACING BANKRUPTCY: PROTECT YOUR LSO LICENSE AND CAREER

Ontario Lawyer Introduction

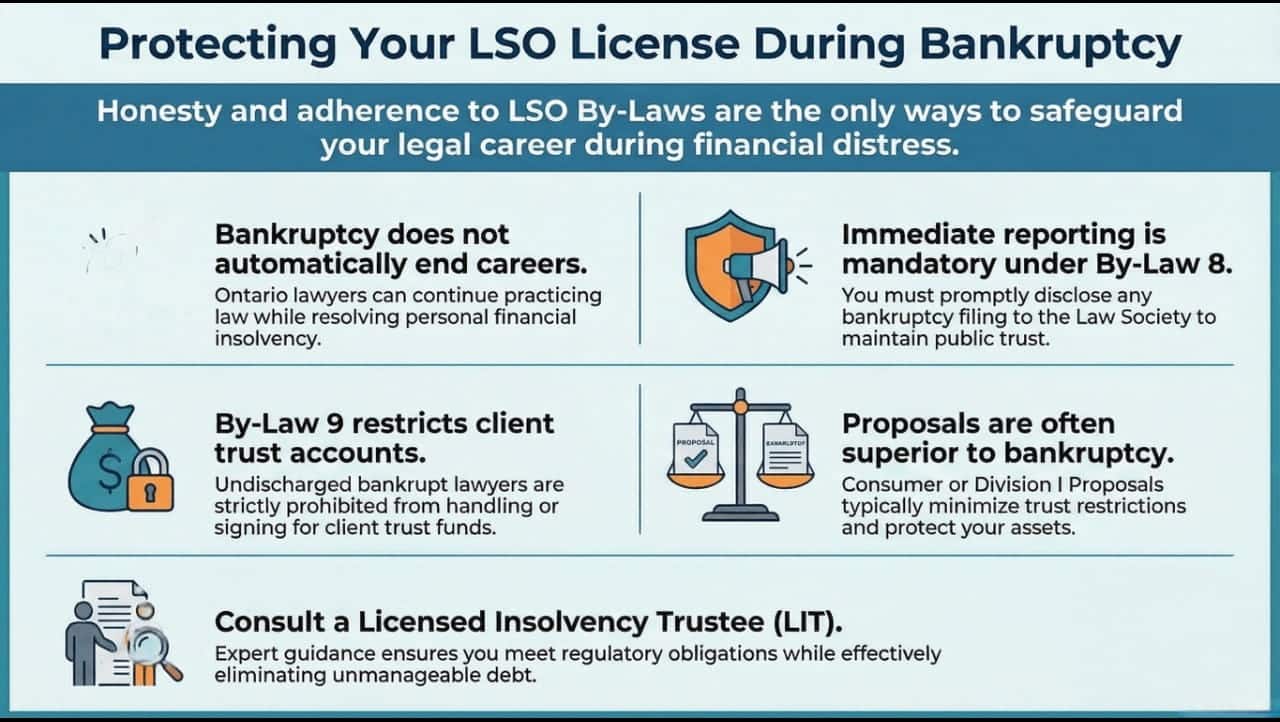
Undeniably, for an Ontario lawyer, the fear of personal bankruptcy isn’t just about losing money. It is the terrifying thought of losing your license, your reputation, and the career you fought so hard to build. Fortunately, you can strategically resolve your financial crisis without sacrificing your livelihood by understanding the exact mechanics of LSO By-Law 8 and By-Law 9.

Key Takeaways

  • Filing for personal bankruptcy does not automatically end your Ontario legal career; you can still practice law.
  • Under LSO By-Law 9, an undischarged bankrupt lawyer is strictly prohibited from handling client trust accounts.
  • Transparency is mandatory, requiring you to report your insolvency to the Law Society of Ontario immediately under By-Law 8.
  • A Consumer Proposal or a Division I Proposal is often a superior alternative, allowing you to avoid bankruptcy and minimize trust account restrictions.
  • Ira Smith Trustee & Receiver Inc. specializes in highly confidential, professional debt solutions for regulated legal professionals.

What is Bankruptcy for an Ontario Lawyer?

Specifically, bankruptcy for an Ontario lawyer is a legal process under the Bankruptcy and Insolvency Act where the Ontario lawyer surrenders their non-exempt assets to a Licensed Insolvency Trustee to eliminate unmanageable debt, while remaining subject to specific regulatory oversight by the Law Society of Ontario. This highly structured legal framework exists to rehabilitate the honest but unfortunate debtor. Consequently, it provides a crucial safety net for those drowning in financial obligations.

Furthermore, as Senior Vice-President of Ira Smith Trustee & Receiver Inc., I understand that facing financial ruin is a uniquely terrifying experience. Legal professionals are universally expected to have all the answers for their own clients. Naturally, admitting to personal financial distress feels like a fundamental failure, triggering severe imposter syndrome.

High-income professionals experience many of the same severe debt crises during their careers as lower-income Canadians. — Source: [Financial Post, Feb 10, 2026]. Therefore, financial hardship is a mathematical problem requiring a strategic legal solution, not a reflection of your moral character, income earning ability or professional competence.

Indeed, the confusing maze of Law Society of Ontario regulations often leaves lawyers paralyzed by false assumptions. Many wrongly assume that being an undischarged bankrupt automatically means a permanent prohibition from practice. Remarkably, filing for bankruptcy does not automatically end your Ontario legal career; you can still practice law.

Why LSO By-Law Compliance Matters For An Ontario Lawyer

Fundamentally, LSO compliance matters because failing to report your insolvency triggers immediate disciplinary actions, severe penalties, and the potential revocation of your legal license. The Law Society’s primary mandate is the protection of the public. Consequently, any financial instability that could threaten client funds is treated with the utmost seriousness.

Importantly, over 140,457 consumer insolvencies were filed in Canada last year alone. — Source: [Office of the Superintendent of Bankruptcy, December 2025]. Clearly, insolvency is a widespread issue, even among highly educated professionals. However, attempting to hide your financial reality from your regulatory body is a catastrophic mistake.

Crucially, trust account violations account for 30% of LSO administrative suspensions. — Source: [LSO Annual Regulatory Report, 2022]. Therefore, absolute transparency is your strongest defence when facing personal financial hardship. Ultimately, by proactively addressing your debt with a Licensed Insolvency Trustee, you demonstrate the ethical responsibility the LSO demands.

The Core Process: Navigating Regulatory Obligations

Procedurally, navigating regulatory obligations involves strict adherence to mandatory reporting and trust account management rules set by the Law Society. You must confront these regulations head-on to protect your practice. Fortunately, understanding these specific bylaws empowers you to make informed, strategic decisions.

LSO By-Law 8: Mandatory Reporting

Initially, you must understand your absolute duty to report your financial status under LSO By-Law 8. The Law Society of Ontario requires immediate disclosure of any bankruptcy filing under By-Law 8, ensuring that public trust is maintained while the lawyer addresses their financial hardship with a Licensed Insolvency Trustee. Unquestionably, this prompt notification is non-negotiable.

Typically, the reporting process involves submitting a formal written notice to the LSO detailing your insolvency proceedings. Subsequently, the Law Society will review your file to ensure that client interests are fully protected. Naturally, they will assign an investigator to evaluate the specific circumstances surrounding your financial collapse.

It is a small minority of insolvent Ontario lawyers who actually face formal license revocation when cooperating fully with their regulatory bodies. Therefore, honesty and prompt reporting drastically improve your chances of maintaining your practice uninterrupted.

LSO By-Law 9: Trust Account Restrictions

Critically, LSO By-Law 9 dictates precisely how an insolvent lawyer must handle client funds. An Ontario lawyer who files for personal bankruptcy does not automatically lose their license to practice law, but LSO By-Law 9 strictly prohibits them from handling client trust funds while undischarged. Consequently, your ability to manage retainer funds is immediately frozen.

Understandably, this restriction creates significant logistical hurdles for any practicing Ontario lawyer. You can no longer accept client funds directly into trust, nor can you disburse settlement money. Essentially, you are barred from the financial mechanics of your own legal practice!

Impact on Sole Practitioners vs. Law Firms

Structurally, the impact of these trust restrictions differs vastly depending on your specific practice environment. An undischarged bankrupt Ontario lawyer can continue to earn a living within a firm environment, provided non-bankrupt partners manage the trust accounts exclusively. Fortunately, this allows firm lawyers to continue serving clients with minimal outward disruption.

Conversely, sole practitioners face a much steeper uphill battle. Typically, a sole practitioner must petition the LSO to approve a non-bankrupt co-signer or arrange for another licensed lawyer to supervise their trust accounts.

An infographic showing the steps an insolvent Ontario lawyer can take through an insolvency process to eliminate their debt and save their law practice and legal career.
Ontario lawyer

Consumer Proposal or Division I Proposal vs. Bankruptcy: Strategic Alternatives

Strategically, a Consumer Proposal or a Division I Proposal is an alternative legal process that allows an Ontario lawyer to renegotiate debt without declaring bankruptcy. This powerful tool is negotiated and administered by a Licensed Insolvency Trustee. Ultimately, it provides a pathway to eliminate unmanageable debt while preserving your professional standing.

Impressively, filing a Proposal through Ira Smith Trustee & Receiver Inc. is a highly effective alternative for Ontario lawyers, allowing them to legally resolve unmanageable debt while minimizing the severe trust account restrictions triggered by a bankruptcy. Consequently, this is often the preferred route for regulated professionals. By choosing and successfully completing this path, you avoid the stigmas and strict operational bans associated with formal bankruptcy.

Insolvent legal professionals can successfully maintain their practice after filing a Consumer Proposal or Division I Proposal. Moreover, a Consumer Proposal can reduce unsecured debt on average by around 75%. — However, each situation and the overall results are unique to each person. Financially, it allows you to retain your assets, including your home and practice equity, while consolidating your obligations into one manageable monthly payment.

I have found that when dealing with insolvent Ontario lawyers, tax arrears, more often than not, are their primary insolvency trigger. Fortunately, a financial restructuring proposal is one of the only legally binding ways to compromise CRA tax arrears without filing for absolute bankruptcy. Therefore, it is a vital lifeline for sole practitioners burdened by unmanageable tax debts.

Practically, managing an insolvent legal practice requires specialized accounting tools, trust account supervisors, and expert insolvency guidance. You cannot navigate this complex intersection of law and finance alone. Instead, you need a structured visual comparison of your available debt relief options to make the best choice.

Visually, comparing your legal options clarifies the optimal path forward for your career:

FeaturePersonal BankruptcyConsumer Proposal

Division I Proposal

LSO Reporting (By-Law 8)Mandatory immediate reportingMandatory immediate reporting
Trust Account Access (By-Law 9)Strictly prohibited while undischargedUsually permitted with LSO approval
Asset ProtectionNon-exempt assets may be seizedYou keep all of your assets
Payment StructureBased on strict surplus income rulesFixed monthly payments negotiated
CRA Tax DebtFully dischargeableFully dischargeable

Additionally, employing robust trust accounting software becomes crucial if you are allowed to practice under supervision. You must maintain immaculate records to satisfy ongoing LSO audits. Ultimately, demonstrating impeccable financial hygiene during your insolvency period proves your ongoing fitness to practice law.

What’s Next for an Insolvent Ontario Lawyer?

Immediately, the next step for an insolvent Ontario lawyer is to secure confidential, expert representation to assess their financial reality. You excel at advising your clients, but you must realize when you need objective counsel yourself. Unquestionably, taking rapid action is the best way to rebuild your financial life and protect your license.

Psychologically, many professionals seeking debt relief report that I speak with say they experienced severe burnout before seeking insolvency help. Therefore, reaching out for help is not just a financial necessity; it is a critical step for your mental well-being. By delegating the stress of creditor negotiations to an expert Licensed Insolvency Trustee, you can refocus on practicing law.

First, you must gather your financial documents, including your recent CRA notices, firm ledgers, and personal debt statements. Then, you should schedule a confidential consultation with Ira Smith Trustee & Receiver Inc. to explore your tailored options. Emphatically, we specialize in discrete corporate and personal insolvency solutions designed explicitly for high-profile professionals.

The financial damage to your credit score with an insolvency process is not forever, but the relief is permanent. Eventually, you will emerge from this crisis stronger, wiser, and fully capable of continuing your legal career.

Frequently Asked Questions: Bankruptcy and Professional Designations For An Ontario Lawyer

1. Will I lose my professional license if I file for bankruptcy in Ontario?

The short answer? Usually, no. Filing for bankruptcy doesn’t mean an automatic end to your career. Most regulatory boards in Ontario won’t instantly pull your license just because you’ve hit a financial rough patch. That said, you do need to tell them what’s going on. You might face temporary guardrails—especially if your day-to-day work involves handling other people’s money.

2. Can an Ontario lawyer continue to practice law while bankrupt?

Yes, you can still practice, but expect some heavy restrictions under the Law Society of Ontario (LSO) By-Law 9. While you’re an undischarged bankrupt, touching client trust accounts is completely off the table. You can’t have signing authority on them. Also, be prepared for your public profile on the LSO directory to be tagged with a “practice restricted” status.

3. What are the mandatory reporting requirements for lawyers facing insolvency?

LSO By-Law 8 leaves no room for delay. The minute you make an assignment in bankruptcy or get served with a petition for a bankruptcy order, you have to let the LSO know. Brushing this under the rug isn’t worth the risk—failing to report can lead to disciplinary hearings or even losing your license outright. You’ll also need to hand over some specific paperwork, including a signed Statement of Affairs and proof that your trust accounts are officially closed. if you need any practice restrictions, remedial steps, or a temporary suspension.

4. Is a restructuring proposal better than bankruptcy for professionals?

For the vast majority of professionals, yes—a consumer proposal or Division I Proposal is the far better route. It usually creates way less friction in your career. The LSO doesn’t slap trust account bans on those who file a proposal, unlike the immediate restrictions triggered by bankruptcy. Beyond your career, a proposal lets you hang onto your assets, dodges certain dreaded bankruptcy restrictions, and leaves a softer footprint on your credit report (showing up as an R7 rather than an R9).

5. Can my employer fire me for filing for bankruptcy?

An employer cannot legally fire, demote, or slash your pay simply because you took steps to deal with your debt. This rule goes for both the private sector and government jobs. Keep in mind, though, that insolvency is a matter of public record. If you need high-level security clearances, the credit check side of things might indirectly complicate future job hunts or promotions.

6. What is the role of a Licensed Insolvency Trustee (LIT)?

A Licensed Insolvency Trustee is the only type of professional federally authorized to handle legal debt solutions in Canada, like bankruptcies and proposals. Think of an LIT as an unbiased referee. Their job is to keep things fair for both you and the people you owe money to, all while guiding you through the different debt relief options actually available to you.

7. Will filing for bankruptcy affect my application to law school or the Bar?

Law school admissions generally couldn’t care less about your personal finances. The provincial Bar, however, absolutely does. When it comes time for the “good character” licensing assessment, you’ll have to disclose your financial history. Checking “yes” for a past bankruptcy doesn’t automatically kill your chances of becoming a lawyer, but the admissions committee will put your application under a microscope to make sure public trust isn’t compromised.

8. Can I pay off a debt relief plan early?

If you’re in a restructuring proposal, absolutely. You have total freedom to ramp up your payments and finish the process ahead of schedule if you come into extra cash. Bankruptcy is a different beast altogether. The timeline and rules are rigidly set by law, meaning you generally can’t just pay it off early to speed up your discharge.

Ontario Lawyer Conclusion: Reclaiming Your Career and Finances

Ultimately, reclaiming your career and finances is entirely possible with transparency, professional guidance, and decisive legal action. An Ontario lawyer facing bankruptcy does not have to surrender their hard-earned license. Instead, by respecting LSO By-Law 8 and By-Law 9, you can safely understand the personal insolvency process while safeguarding your livelihood.

Undoubtedly, the journey through professional debt is daunting, but you do not have to walk it alone. Ira Smith Trustee & Receiver Inc. possesses the empathy, expertise, and discretion required to guide you back to financial stability. Therefore, take a deep breath, acknowledge the problem, and let us help you implement the expert debt solutions necessary to secure your future today.

Don’t wait until it’s too late. The longer you delay, the fewer options become available, and the greater the risk to your business and your personal finances. Taking that first step to seek expert advice is the most powerful and proactive decision you can make right now.

Take Action Today: Contact Ira Smith Trustee & Receiver Inc.

We are Licensed Insolvency Trustees, dedicated to providing clear, actionable, and compassionate advice to businesses across Ontario. We offer:

  • Free, Confidential Consultations: Discuss your unique situation without cost, obligation, or judgment.
  • Expert Guidance: Understand all your options for business debt restructuring, from informal negotiations to formal proposals under Canadian law.
  • A Clear Path Forward: Get a personalized, step-by-step plan tailored specifically to your business’s needs and goals.
  • Relief from Pressure: We can help you stop creditor harassment and regain control.

Let us help you lift the burden of debt and guide your business towards a sustainable, successful future. Call us now or visit our website to schedule your free consultation. Your business’s second chance starts here.

Take the first crucial step towards a brighter financial future for your business. Contact Ira Smith Trustee & Receiver Inc. today to schedule your free initial consultation. Your business’s pivot to sustainable success starts now.

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing the possibility of legal action, contact Ira Smith Trustee & Receiver Inc. today. We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan.

Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life. Take the first step towards a brighter financial future – call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy and is a member of the Canadian Association of Insolvency and Restructuring Professionals.

——————————————————————————–

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and my professional expertise as a licensed insolvency trustee. The information provided does not constitute legal or financial advice for your specific circumstances.

Every situation is unique and involves complex legal and factual considerations. The outcomes discussed in this article may not apply to your particular situation. Situations are fact-specific and depend on the particular circumstances of each case.

Please contact Ira Smith Trustee & Receiver Inc.get in touch with Ira Smith Trustee & Receiver Inc.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a licensed insolvency trustee serving clients across Ontario. With extensive experience in complex court-ordered receivership administration and corporate insolvency & restructuring proceedings, Brandon helps businesses, creditors, and professionals navigate challenging financial situations to achieve optimal outcomes.

Brandon stays current with landmark developments in Canadian insolvency law. He brings this cutting-edge knowledge to every client engagement, ensuring his clients benefit from the most current understanding of their rights and options.

Side by side image on the left a stressed out Ontario lawyer facing insolvency and on the right side, a happy Ontario lawyer who achieved debt elimination through an insolvency process administered by Ira Smith Trustee & Receiver Inc.
Ontario lawyer


Categories
Brandon Blog Post

THE ULTIMATE GUIDE TO SURVIVING TERRIBLE TARIFFS ANXIETY: PROTECTING VAUGHAN, ONTARIO MANUFACTURERS FROM U.S. BORDER COSTS

Undeniably, large tariffs don’t just cut into your profit margins—it wipes them out overnight. However, panic is an inadequate response when your auto parts manufacturing business in Vaughan, Ontario, faces an immediate cash flow crisis. Consequently, this guide delivers actionable strategies to leverage corporate debt restructuring and protect your company from impending U.S. trade tensions.

Key Takeaways:

  • Margin wipeout: Tariffs directly hit cash flow, making debt repayment impossible for many suppliers.
  • Action over panic: Mitigating the impact of tariffs requires immediate financial restructuring, not just operational shifts.
  • Legal protection: Tools like a Division I Proposal stop creditor collections while you fix your supply chain.
  • Expert help: Ira Smith Trustee & Receiver Inc. can guide your Ontario manufacturing business back to profitability, whether it is located in Woodbridge, Ontario, or anywhere else in the Greater Toronto Area.

What is Tariffs-Induced Anxiety?

Tariffs-induced anxiety is the severe financial stress experienced by business owners facing sudden, crippling border taxes on their exported goods. Indeed, this fear is completely justified for companies operating within Ontario’s deeply integrated automotive network. Often, executives lose sleep wondering how they will meet payroll when cross-border shipping costs unexpectedly double overnight. Statistically, Ontario’s auto sector supports over 100,000 direct jobs. — Source: [Government of Ontario, 2023].

Consequently, this widespread economic anxiety affects not just CEOs, but thousands of hardworking families across the province. Ontario manufacturers facing tariffs anxiety can achieve supply chain resilience by legally renegotiating vendor debt and pausing creditor payments through a licensed insolvency trustee. Ultimately, acknowledging this anxiety is the vital first step toward implementing a strategic financial turnaround.

Why Mitigating The Impact of Tariffs Matters

Fundamentally, mitigating the impact of tariffs matters because ignoring these costs will instantly push a healthy manufacturing business into severe corporate insolvency. Actually, the automotive supply chain relies heavily on parts that cross the border multiple times before final assembly. Crucially, cross-border friction and tariffs can add up to $5,000 to the final price of a vehicle. — Source: [TD Economics, 2019]. Therefore, addressing these costs immediately prevents minor cash flow hiccups from becoming fatal financial wounds.

Furthermore, increased costs at the border inevitably result in lower consumer sales and drastic production cuts. Naturally, when assembly lines slow down, smaller suppliers are left with overflowing inventories and no incoming revenue. Unfortunately, commercial insolvencies in Canada surged by 41.4% year-over-year. — Source: [Office of the Superintendent of Bankruptcy, 2024]. Thus, securing professional financial advice early is the only way to avoid becoming another grim statistic.

Core Automotive Supply Chain Resilience Strategies

Strategically, automotive supply chain resilience requires a combination of aggressive cost-cutting, geographic diversification, and formal legal debt relief. First, business owners must recognize that relying solely on operational changes is rarely enough to offset a massive border penalty. Actually, panic is not a strategy; restructuring is a survival tactic. Consequently, proactive executives must explore both operational and financial pathways to secure their company’s future.

The Difference Between Operational Adjustments and Financial Restructuring

Crucially, the difference between operational adjustments and financial restructuring lies in how they address existing corporate liabilities. Initially, operational adjustments involve changing suppliers, moving warehouses, or physically altering how your goods are manufactured. While these operational shifts are necessary for long-term survival, they do absolutely nothing to eliminate the debt you have already accumulated. Conversely, formal financial restructuring specifically attacks your current debt load, providing immediate legal relief from aggressive creditors.

Moreover, operational changes typically require months or even years to fully implement across a complex supply chain. Meanwhile, tariffs-induced anxiety has undeniably dampened hiring plans for 40% of manufacturers. — Source: [First National, 2024]. Therefore, relying solely on operational pivots leaves your company highly vulnerable to bankruptcy during the lengthy transition period. Distinctly, combining both approaches guarantees that your business survives today while preparing adequately for tomorrow’s trade landscape.

Protecting Cash Flow Instantly

Initially, protecting your cash reserves is the absolute most critical step when surviving sudden Ontario manufacturing tariffs. First, audit all your current expenses and aggressively eliminate any non-essential corporate spending. Next, accelerate your accounts receivable by offering small incentives to clients who pay their invoices ahead of schedule. Ultimately, cash is the oxygen of your business, and preserving it gives you time to implement broader cross-border trade strategies.

Renegotiating Vendor Contracts Legally

Legally, renegotiating vendor contracts is a mandatory step when building robust automotive supply chain resilience. Firstly, you must proactively review every single supply agreement to identify clauses related to sudden international tax increases. Often, legacy contracts force the manufacturer to absorb all unexpected border costs entirely. Strikingly, over 70% of Ontario auto parts are destined for the American market. — Source: [Canadian Vehicle Manufacturers’ Association, 2023]. Unquestionably, absorbing a large hit on such a massive volume will immediately bankrupt most mid-sized parts suppliers in Ontario.

Subsequently, executives must initiate transparent conversations with their largest clients and most critical suppliers. Tactically, explaining your financial reality using data builds trust and encourages collaborative problem-solving across the supply network. However, if major clients refuse to share the tariffs burden, you must seriously consider utilizing formal corporate legal restructuring. Ultimately, a contract that guarantees massive financial losses is a contract that must be legally restructured or abandoned.

Importantly, when operational tweaks fail, formal Corporate Restructuring Services provide the ultimate safety net for struggling manufacturers. Specifically, according to Brandon Smith of Ira Smith Trustee & Receiver Inc., mitigating the impact of the U.S. tariffs on Ontario’s automotive supply chain requires utilizing corporate restructuring tools, such as a Division I Proposal, to protect cash flow and avoid bankruptcy. Basically, a Division I Proposal allows your business to legally pause creditor payments while you negotiate a fair financial settlement. Consequently, you remain entirely in control of your daily operations while systematically shedding unmanageable corporate debt.

Additionally, this legal protection immediately halts hostile actions from aggressive vendors or anxious lenders. Suddenly, bank accounts are unfrozen, and threatening collection calls cease completely. Ultimately, filing a formal proposal provides the critical breathing room needed to pivot your operations without the constant threat of facility closure.

An infogrphic showing the steps that Vaughan, Ontario manufacturing companies can enter bankruptcy protection to restructure with a licensed insolvency trustee as a result of tariffs reducing profitability and causing debt problems.
tariffs

Practical Tools for Cross-Border Trade Strategies

Effective cross-border trade strategies utilize specialized financial forecasting software alongside expert legal restructuring frameworks to neutralize border taxes. Fortunately, executives do not need to invent these survival blueprints from scratch. Instead, proven methodologies exist to help map out supply chain vulnerabilities and legally restructure outstanding vendor liabilities. Clearly, U.S.-bound auto shipments account for nearly 30% of Ontario’s international exports. — Source: [Statistics Canada, 2023].

Visually, exploring your options helps demystify the complex corporate turnaround process. Below is a structured comparison of the tools available to combat rising U.S. trade tensions. Specifically, this table contrasts operational adjustments with formal legal protections.

Strategy TypeTool / MethodPrimary BenefitSpeed of Impact
OperationalSupplier DiversificationBypasses border tariffs entirelySlow (6-12 Months)
FinancialCash Flow ForecastingHighlights upcoming cash crunchesFast (Immediate)
Legal ReliefDivision I ProposalStops creditor lawsuits instantlyModerate (with immediate legal protection)
Legal ReliefCorporate BankruptcyCloses unviable businesses legallyModerate (with immediate legal protection)

Thankfully, utilizing these tools prevents the emotional exhaustion that typically accompanies severe corporate financial crises. Interestingly, up to 80% of cross-border auto parts move back and forth multiple times before final assembly. — Source: [Cox Automotive, 2024]. Therefore, mapping these movements with digital tools allows you to accurately predict exactly where the tariffs will inflict the most damage.

What’s Next for Defeating U.S. Trade Tensions

Undoubtedly, the next crucial step for defeating business insolvency Ontario is scheduling a confidential assessment with a Licensed Insolvency Trustee. Simply, waiting for politicians to resolve international trade disputes is a guaranteed way to bankrupt your factory. Instead, you must immediately take decisive control over your company’s balance sheet and outstanding creditor obligations. Ultimately, supply chain resilience is not just about moving factories; it is about restructuring your corporate debt.

Presently, the dedicated experts at Ira Smith Trustee & Receiver Inc. are ready to analyze your unique financial situation thoroughly. First, we will discreetly review your cash flow statements, vendor contracts, and outstanding loan obligations. Next, we will craft a customized restructuring plan designed to pause debt collections and stabilize your manufacturing operations. Emphatically, Contact Us today to secure the immediate legal protection your Ontario business desperately requires.

Evidently, taking proactive action today significantly increases your chances of achieving a successful corporate turnaround. Habitually, businesses that seek professional insolvency advice early preserve more assets and save more local jobs. Therefore, do not let temporary international border disputes destroy the incredible enterprise you have spent years building.

Tariffs Frequently Asked Questions (FAQ)

Naturally, business owners have many pressing questions when facing unprecedented cross-border trade challenges. Below, we address the most common concerns regarding Vaughan, Ontario manufacturing tariffs and corporate survival. Read these expert answers to quickly understand your legal options and operational realities.

Q1: How do the U.S. tariffs impact Ontario automotive supply chains?

A: Financially, the U.S. tariffs drastically increase the cost of materials and finished goods crossing the international border. Because auto parts often cross the U.S.-Canada border multiple times during assembly, this tax compounds rapidly. Consequently, this compounded tax wipes out supplier profit margins, reduces consumer sales, and causes severe cash flow shortages for Ontario manufacturers.

Q2: What are the best cross-border trade strategies to mitigate the U.S. tariffs’ impact?

Operationally, to mitigate tariff impacts, businesses should immediately audit their supply chains to source local Canadian materials where possible. Additionally, companies must update sales contracts to pass on sudden tariff costs directly to end buyers. Most importantly, manufacturers must use legal financial restructuring to free up cash flow trapped by unsustainable debt loads.

Absolutely, corporate restructuring is specifically designed to save viable manufacturing businesses from unexpected macroeconomic debt shocks. Furthermore, according to Brandon Smith of Ira Smith Trustee & Receiver Inc., tools like a Division I Proposal allow businesses to pause creditor payments and renegotiate their debts legally. Ultimately, this legal mechanism provides the crucial breathing room needed to adjust to new tariffs realities and avoid Corporate Bankruptcy.

Brandon’s Take On Tariffs

You’ve worked too hard to let your livelihood get choked out by roadwork you can’t control. Making a move now, instead of waiting for the bank to call the loan, is the smartest thing you can do. The longer you wait and bleed cash, the fewer options you’ll have.

At Ira Smith Trustee & Receiver Inc., we’re in the business of finding permanent solutions for Vaughan business owners. We give you a confidential, zero-judgment space to figure out your next move—whether that’s fighting your landlord or completely restructuring your debt.

Reach out to Ira Smith Trustee & Receiver Inc. today for a FREE, no-obligation chat. Let’s look at your books, figure out your rights, and build a plan to get you through the dust. Call us at (416) 948-6933, hit up IraSmith.com, or just walk into our office at 167 Applewood Crescent in Vaughan. You aren’t doing this alone. We’re here to help you get out of the gridlock.

Ira Smith Trustee & Receiver Inc. has the expertise and experience to guide you through these perilous waters. As Licensed Insolvency Trustees, we are uniquely qualified to assess your company’s financial situation, advise on the best course of action, and help you understand and mitigate your personal risks. We can help you understand your options, assess your personal risk, and develop a strategy to protect your future. Our approach is empathetic, non-judgmental, and focused on finding the best possible outcome for you and your company.

Contact us for a free, confidential consultation. The sooner you act, the more options you have, and the better protected you will be. Let us help you navigate your path to a brighter financial future.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy and is a member of the Canadian Association of Insolvency and Restructuring Professionals.

—————————————————————————

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and my professional expertise as a licensed insolvency trustee. The information provided does not constitute legal or financial advice for your specific circumstances.

Every situation is unique and involves complex legal and factual considerations. The outcomes discussed in this article may not apply to your particular situation. Situations are fact-specific and depend on the particular circumstances of each case.

Don’t hesitate to get in touch with Ira Smith Trustee & Receiver Inc.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a licensed insolvency trustee serving clients across Ontario. With extensive experience in complex court-ordered receivership administration and corporate insolvency & restructuring proceedings, Brandon helps businesses, creditors, and professionals navigate challenging financial situations to achieve optimal outcomes.

Brandon stays current with landmark developments in Canadian insolvency law. He brings this cutting-edge knowledge to every client engagement, ensuring his clients benefit from the most current understanding of their rights and options.

Data visualization of a post-tariffs margin analysis for an Ontario automotive parts manufacturer with President Donald Trump and Prime Minister Mark Carney
tariffs


Categories
Brandon Blog Post

CORPORATE DEBT RESTRUCTURING STRATEGIES FOR ONTARIO BUSINESS OWNERS: STOP INSOLVENCY

By Brandon Smith, Senior Vice-President, Licensed Insolvency Trustee at Ira Smith Trustee & Receiver Inc.


Corporate Debt Restructuring Key Takeaways:

  • The Division I Proposal is a proactive business strategy, not a sign of financial failure, designed to restructure significant corporate debt in a financially distressed company or business.
  • It offers immediate legal protection from creditors through a “stay of proceedings,” allowing your business to stabilize and strategize.
  • Creditors often prefer a Division I Proposal because it typically offers a better financial return (e.g., 30 cents on the dollar) than the high risk of receiving nothing in a corporate bankruptcy.
  • Only a Licensed Insolvency Trustee (LIT) like those at Ira Smith Trustee & Receiver Inc. can guide your Ontario business through this complex, yet powerful, restructuring process.
  • Ira Smith Trustee & Receiver Inc. provides expert, empathetic, and authoritative support to help your business successfully pivot, preserve value, and secure a sustainable future in Vaughan and across the GTA.

1. Corporate Debt Restructuring Introduction: Navigating Financial Distress – The 2026 Business Landscape

The economic currents in Ontario are always shifting, and as we are now just a bit over a month into 2026. Many business owners in Vaughan and the Greater Toronto Area (GTA) are feeling the squeeze. From rising costs to uncertain market demands and persistent interest rate pressures, navigating these waters can lead to significant financial challenges. For dedicated entrepreneurs, the burden of mounting corporate debt restructuring can feel overwhelming, threatening the very existence of the businesses they’ve poured their lives into.

But here’s a crucial truth: financial difficulty doesn’t automatically mean the end of your company. In fact, it can be the precise moment for a powerful strategic pivot. At Ira Smith Trustee & Receiver Inc., we specialize in helping viable businesses overcome these hurdles. We firmly believe that the Division I Proposal is not a sign of failure, but rather a robust tool for corporate debt restructuring – a smart, calculated business move that allows your company to adapt, shed unsustainable debt, and emerge stronger and more resilient for the future.

A GTA business executive analyzing financial reports, symbolizing strategic corporate debt restructuring and a business pivot, in Ontario, with a Division I Proposal.
corporare debt restructuring

2. What is Corporate Debt Restructuring?

Corporate debt restructuring is a formal process where a company facing financial difficulty reorganizes its outstanding debts to improve its financial health and avoid bankruptcy. The primary goal is to create a sustainable financial future by changing how and when debts are paid. This process allows the business to continue operating, preserving its value, jobs, and market presence, rather than undergoing liquidation, where assets are sold off.

In Canada, formal restructuring processes for businesses are primarily governed by federal law, specifically the Bankruptcy and Insolvency Act (BIA). While very large corporations (with debts over $5 million) might use the Companies’ Creditors Arrangement Act (CCAA), for the vast majority of Ontario businesses, the BIA provides the necessary framework for effective corporate debt restructuring.

This crucial process can involve various types of corporate debt, including:

  • Bank Loans: Both secured loans (backed by assets) and unsecured operating lines of credit.
  • Trade Payables: Money owed to your suppliers for goods or services purchased on credit.
  • Lease Obligations: Financial obligations arising from equipment leases or commercial property leases.
  • Unsecured Loans: Loans not tied to specific company assets.
  • Credit Card Debts: Business credit cards used for operational expenses.
  • Tax Debts: Certain obligations owed to the Canada Revenue Agency (CRA), such as corporate income tax or unremitted HST. Although unremitted source deductions cannot be eliminated, an extension of time to pay is available.
  • Employee-Related Debts: Unpaid wages, vacation pay, or other benefits (though these often have special priority under the law).

By reorganizing these debts, a business can align its payment obligations with its actual cash flow, making its financial future manageable and sustainable.

3. Corporate Debt Restructuring Introduction Using The Division I Proposal: Your Business Pivot Tool

When an Ontario business needs to undergo formal corporate debt restructuring, the Division I Proposal is the powerful Canadian solution under the Bankruptcy and Insolvency Act (BIA). It is critical to understand that this is distinctly different from “Chapter 11 bankruptcy” processes you might hear about in the United States, which fall under a different legal jurisdiction. A Division I Proposal is a formal, legally binding offer made by an insolvent corporation (or an individual with high debts) to its unsecured creditors to repay a portion of what is owed, extend repayment periods, or alter other payment terms.

This mechanism serves as a true “Business Pivot” for several compelling and strategic reasons:

  • Immediate Legal Protection (Stay of Proceedings): This is often the most significant and immediate benefit. Once a Notice of Intention (NOI) to file a proposal, or the proposal itself, is formally filed with the Office of the Superintendent of Bankruptcy (OSB), your business gains immediate legal protection from most creditors. This crucial “stay of proceedings” means:
    • All collection calls and harassing communication from creditors must cease.
    • Existing lawsuits and new legal actions against your company are automatically paused.
    • For consumers, wage garnishments, if any, are stopped.
    • Creditors are prevented from seizing your company’s assets or enforcing judgments. This creates essential breathing room, allowing your management team to focus on operations and strategize without constant external pressure.
  • Business Continuity and Preservation: Unlike corporate bankruptcy, where the business typically ceases operations and assets are sold off, a Division I Proposal is designed to allow your company to continue running. This means you can:
    • Retain your invaluable employees, protecting their livelihoods and your company’s institutional knowledge.
    • Maintain crucial relationships with your loyal customers and essential suppliers.
    • Preserve your company’s brand reputation and market presence.
    • Continue generating revenue, which is vital for funding the restructured debt payments.
  • Debt Reduction and Manageable Terms: The proposal process empowers you to negotiate with your creditors to reduce the total amount of debt owed and/or extend the payment timeline. This results in a realistic, affordable repayment plan that directly aligns with your business’s projected cash flow, moving away from unmanageable debt loads.
  • Formal Negotiation Power: The BIA provides a structured, legally supported framework for negotiating with all your unsecured creditors at once. Instead of attempting to appease each creditor individually, your Licensed Insolvency Trustee acts as the central point for negotiation, ensuring fairness and efficiency.
  • No Debt Limit for Corporations: Unlike a Consumer Proposal for individuals, which has a debt ceiling, a Division I Proposal has no upper limit on the amount of debt a corporation can owe. This makes it a suitable and powerful tool for the corporate restructuring of businesses of varying sizes and complexities.
  • Potential Director Protection: When executed correctly by a skilled LIT, a Division I Proposal can offer directors a degree of protection against certain corporate liabilities that arise by law against anyone only because they are a director of a company, a critical concern for many business owners.

A Division I Proposal isn’t about giving up; it’s about strategically reorganizing to give your business a fresh, viable start. It’s a proactive choice for businesses with a solid core operation but overwhelmed by debt.

A GTA business executive analyzing financial reports, symbolizing strategic corporate debt restructuring and a business pivot, in Ontario, with a Division I Proposal.
corporare debt restructuring

4. The Economics of 2026: Why Creditors Accept Proposals

Understanding why creditors would agree to be paid less than the full amount owed is central to appreciating the Division I Proposal as a highly strategic move in corporate debt restructuring. The answer lies in pragmatic economics, risk assessment, and the realities of the current and predicted economic climate for 2026.

The “30 Cents vs. 0 Cents” Logic

Creditors, whether they are large financial institutions, trade suppliers, or the Canada Revenue Agency, are fundamentally pragmatic. Their primary objective is to recover as much of the money owed to them as possible. In many scenarios, if a financially distressed business is forced into corporate bankruptcy, the outcome for unsecured creditors is often dismal. After secured creditors (like banks with collateral) are paid, and the costs of liquidation are covered, there is frequently little to no money left for unsecured creditors. This can tragically result in them receiving 0 cents on the dollar.

A carefully crafted Division I Proposal dramatically changes this equation. It results in the payment of a percentage of the ordinary unsecured debt – for instance, 30 cents on the dollar. This result from a corporate restructuring is a far more attractive, certain, and predictable outcome compared to the high risk of receiving nothing at all in a corporate liquidation.

Creditors’ Perspective in the 2026 Economic Landscape

In 2026, with the Canadian economy continuing to adapt to global shifts, fluctuating interest rates, businesses potentially facing tightened credit markets and rising costs, creditors are increasingly open to realistic and well-structured proposals. When evaluating a Division I Proposal, creditors typically consider:

  • The Business’s Underlying Viability: Does the company possess a strong core business model that has the potential to succeed and generate profit if its overwhelming debt load is reduced to a manageable level?
  • Management’s Competence: Is the current leadership team capable of effectively implementing the proposed restructuring plan and steering the business towards profitability?
  • Cash Flow Projections: Are the financial projections realistic, demonstrating that the business can generate sufficient cash flow to make the proposed payments on time?
  • The Alternatives: What would they realistically receive if the company were to declare bankruptcy? The comparison between the proposed return and the estimated bankruptcy dividend is a critical factor. When a comprehensive and viable proposal is presented by an experienced Licensed Insolvency Trustee, clearly outlining a path to recovery and demonstrating a superior return compared to bankruptcy, creditors are strongly motivated to accept.

Once accepted by the required majority of unsecured creditors voting and approved by the court, the proposal becomes legally binding on all unsecured creditors, even those who initially voted against it. This collective, binding agreement is a cornerstone of the Division I Proposal’s power and effectiveness.

5. BIA Proposal vs. Bankruptcy: Distinguishing the Two Distinct Paths

It is absolutely crucial for any Ontario business owner considering corporate debt restructuring to understand the fundamental differences between a Division I Proposal and corporate bankruptcy. These are not interchangeable terms; they represent vastly distinct paths with significantly different outcomes for your business, its owners, and its creditors. One is about survival, strategic reorganization, and continuity; the other is about formal cessation and asset liquidation.

Here’s a clear comparison to highlight these key distinctions:

Criteria

Division I Proposal (BIA)

Corporate Bankruptcy (BIA)

Primary Goal

Restructure debt, ensure business continuity, save jobs, preserve value

Liquidate assets, formally close the business

Business Continuity

YES

The business typically continues operating without interruption.

NO

The business either immediately or ultimately ceases operations, and assets are sold.

Asset Retention

Key business assets (property, equipment, inventory) are generally retained by the company.

Assets are seized, collected, and sold off by the Licensed Insolvency Trustee to pay creditors.

Creditor Outcome

Creditors receive a negotiated percentage of what’s owed over time, often a better return than bankruptcy.

Creditors receive a pro-rata share of liquidation proceeds, which is often minimal or zero for unsecured creditors.

Legal Protection

Immediate “stay of proceedings” against most creditor actions upon filing NOI or proposal.

Immediate “stay of proceedings” against most creditor actions upon filing for bankruptcy.

Director Liability

Can offer a degree of protection and relief from certain corporate liabilities that become personal liabilities for directors (e.g., statutory debts).

While the corporation is bankrupt, certain statutory liabilities (e.g., unremitted source deductions, HST) for directors persist or arise.

Public Perception & Record

Seen as a strategic recovery or reorganization, a public record exists, but often carries less stigma.

A more severe public record, widely indicating business failure and often leading to loss of goodwill.

Credit Impact

Negative initially, but successful completion allows for rebuilding creditworthiness over time, demonstrating financial responsibility.

More severe and longer-lasting negative impact on corporate credit, often making future credit difficult to obtain for a new venture run by the same management.

Duration of Process

Flexible, typically structured over several years (e.g., 1 to 5+ years) based on the negotiated plan.

Generally involves an ongoing administration process until all assets are realized and distributed.

Control of Business

Management retains control of daily operations, guided by the proposal.

Control shifts to the Licensed Insolvency Trustee, who manages the liquidation process.

Choosing between a Division I Proposal and corporate bankruptcy is a monumental decision. It determines whether your business gets a second chance to thrive or is dissolved. The emotional and financial impacts are profound, making expert guidance from a Licensed Insolvency Trustee essential.

A GTA business executive analyzing financial reports, symbolizing strategic corporate debt restructuring and a business pivot, in Ontario, with a Division I Proposal.
corporare debt restructuring

6. The Corporate Debt Restructuring Process: A Strategic Roadmap for a Division I Proposal

Navigating a Division I Proposal for corporate debt restructuring might seem daunting at first glance, but with the expert guidance of a Licensed Insolvency Trustee, it becomes a clear, structured, and manageable path to recovery. At Ira Smith Trustee & Receiver Inc., we break down this journey into distinct phases, ensuring you understand each step and feel supported throughout.

Corporate Debt Restructuring Phase 1: Initial Assessment and Consultation

  • Your Crucial First Step: The very first and most critical action you should take is to contact a Licensed Insolvency Trustee (LIT). In Canada, an LIT is the only professional legally authorized to administer a Division I Proposal. Our team at Ira Smith Trustee & Receiver Inc. offers confidential, no-obligation consultations to understand your unique situation.
  • Comprehensive Financial Analysis: We will conduct a thorough and impartial review of your company’s entire financial picture. This includes meticulously examining your assets, liabilities, revenue streams, operational expenses, and overall cash flow. We also work with you to identify the core strengths and viable aspects of your business that can be leveraged for a successful turnaround.
  • Developing the Proposal Plan: Working hand-in-hand with you, we will craft a realistic, feasible, and compelling proposal. This involves determining what percentage of your total debt your business can reasonably afford to repay over a specific timeframe. Our goal is to create a plan that maximizes the return for your creditors while simultaneously ensuring your business can continue to operate profitably and sustainably after the restructuring.

Corporate Debt Restructuring Phase 2: Filing the Notice of Intention (NOI) or the Proposal

  • Immediate Legal Protection: If your business needs more time to finalize the details of its comprehensive proposal plan, we can file a Notice of Intention (NOI) with the Office of the Superintendent of Bankruptcy (OSB). This filing immediately triggers the “stay of proceedings,” providing your business with crucial legal protection from creditors and stopping all collection actions.
  • Establishing a Timeline: The NOI grants your business an initial period of 30 days to prepare and file the formal Division I Proposal. This period is not set in stone; it can be extended by the court, if necessary, providing you with vital breathing room to complete all required documentation and negotiations. Alternatively, if your comprehensive plan is already finalized, we can file the proposal directly without an NOI.

Corporate Debt Restructuring Phase 3: The Meeting of Creditors

  • Presentation by Your LIT: As your appointed LIT, we take the lead in preparing for and conducting the meeting of creditors. During this meeting, we will formally present your Division I Proposal to all your unsecured creditors. This includes providing them with a detailed, transparent explanation of your company’s financial situation, the reasons for the proposal, and the specific terms of your offer.
  • The Critical Creditor Vote: Creditors will then have the opportunity to vote on whether to accept or reject your proposal. For the Division I Proposal to be legally accepted, two specific conditions must be met:
  1. A simple majority (50% + 1) in number of the creditors who vote must approve the proposal.
  2. Those approving creditors must collectively represent at least two-thirds (66.6%) of the total dollar value of the claims filed by all voting creditors.
    • Reinforcing the “30 Cents vs. 0 Cents” Logic: A key part of our presentation as your LIT is to provide creditors with a clear estimate of what they would realistically receive if your company were to go bankrupt, compared to the return offered in the proposal. This directly reinforces the pragmatic economic advantage of accepting the proposal.

Corporate Debt Restructuring Phase 4: Court Approval and Implementation

  • Court approval: After the proposal passes the creditor vote, a judge has to act like a referee to make sure the “deal” is actually fair for everyone involved. First, the judge looks at the plan to see if it makes sense; if it passes that test, the judge makes sure that the corporate debt restructuring plan does not run afoul of the BIA. Only after the judge gives their official “okay” does the Division I Proposal debt relief plan become effective.
  • Legally Binding Agreement: As stated above, if the creditors accept the proposal, the final step is to submit it to the court for formal approval. Once the court grants its approval, the Division I Proposal becomes legally binding on all unsecured creditors, including any who may have voted against it. This legal enforceability is what gives the proposal its power and certainty.
  • Supervised Implementation and Monitoring: Your Licensed Insolvency Trustee will then oversee the administration of the proposal. This involves ensuring that your company adheres to all the agreed-upon payment terms and conditions and the BIA statute. We provide ongoing monitoring and support, ensuring accountability and steady progress towards your ultimate goal of becoming debt-free and financially stable.

The journey of a Division I Proposal is complex, but with Ira Smith Trustee & Receiver Inc., you’re never alone. We are committed to guiding your Ontario business through each phase with expertise and empathy.

7. Corporate Debt Restructuring Strategic Considerations for Your Business

A Division I Proposal is far more than just a mechanism for corporate debt restructuring; it is a sophisticated, strategic maneuver designed to protect and revitalize the long-term future of your business. Here are critical areas where its strategic value truly shines, offering benefits that extend far beyond simply reducing debt.

Preserving Business Value and Goodwill Through Corporate Debt Restructuring

Your business has spent years, perhaps decades, building valuable goodwill, establishing a loyal customer base, cultivating essential supplier relationships, and accumulating operational assets. A Division I Proposal is specifically designed to keep these vital components intact. By strategically avoiding corporate bankruptcy, you prevent the forced and often rapid liquidation of your assets, which frequently occurs at drastically undervalued prices. This preservation of your operating infrastructure allows your company to maintain its reputation, continue generating revenue, and retain its market position. This directly contributes to maximizing the recovery for all stakeholders, including creditors, while securing your business’s future.

Employee Retention and Morale With Corporate Debt Restructuring

Your employees are not just a cost; they are the most valuable asset and the backbone of your business. A successful corporate debt restructuring through a Division I Proposal means you can typically avoid the devastating impact of mass layoffs or significant disruption to your workforce. Retaining your skilled, experienced, and loyal staff is absolutely vital for your company’s continued smooth operation, maintaining productivity, and achieving future growth. It prevents the costly process of rehiring and retraining, as well as the loss of invaluable institutional knowledge and company culture. Maintaining employee morale during challenging times is paramount, and a proposal offers a pathway to stability for everyone.

Through a Division I Proposal, it is also possible to reduce your headcount. The proposal can be worded so that the proper claims of employees who were terminated before or as part of the corporate debt restructuring process are caught in the proposal and do not survive.

Director Liability Protection With Corporate Debt Restructuring

One of the most significant and often frightening concerns for business owners facing financial distress is the spectre of personal liability. Directors of a corporation can, under Canadian law, be held personally liable for certain statutory debts, even if the company itself is a separate legal entity. These specific liabilities can include:

  • Unremitted Canada Pension Plan (CPP) and Employment Insurance (EI) deductions (source deductions).
  • Unpaid Harmonized Sales Tax (HST) amounts collected but not remitted.
  • Unpaid Workplace Safety and Insurance Board (WSIB/WCB) premiums.
  • Unpaid employee salary, wages and vacation pay.

A carefully structured and properly administered Division I Proposal, overseen by a Licensed Insolvency Trustee, can offer a crucial degree of protection or relief against some of these personal liabilities for directors. An important caveat is that it is only those liabilities that the directors are personally liable for solely as a result of their role as a director. It cannot absolve a director for their personal liability for any debts they personally guaranteed or indemnified a lender or landlord for.

It’s imperative to discuss your specific situation thoroughly with your LIT to understand the precise extent of this potential protection, as it is a complex area of law.

Negotiating with CRA (Canada Revenue Agency) In A Corporate Debt Restructuring

The Canada Revenue Agency (CRA) is a unique and often significant creditor for many businesses in Ontario. They have considerable power to enforce collections. However, a Division I Proposal provides a formal legal framework that allows for the effective restructuring of certain tax debts. This means you can include it in a Division I Proposal, allowing for a manageable payment plan. Amounts owed for corporate income tax and unremitted HST can be eliminated through a completed Division I Proposal. Although unremitted source deductions cannot be eliminated like other CRA debts, a debtor has up to 6 months after court approval to pay off that debt in full.

As your LIT, Ira Smith Trustee & Receiver Inc. has extensive experience dealing with the CRA and can expertly incorporate these complex tax debts into your comprehensive proposal, ensuring a holistic solution.

Secured vs. Unsecured Creditors: Differentiating Approaches

Business owners need to understand that different types of creditors are treated differently within a Division I Proposal. Unsecured creditors (those without specific collateral tied to their debt) are legally bound by an approved Division I Proposal.

Secured creditors, however, who hold specific collateral (such as a bank with a mortgage on your property or a lien on equipment), have an option: they can choose to participate in the proposal, or they can opt to act independently outside of the proposal framework (with certain requirements needing to be fulfilled if they wish to enforce their security after the filing of the NOI or Division I Proposal).

Your LIT will provide expert guidance through these negotiations with all creditor types, developing a strategy that aims to achieve the best possible outcome for your business’s overall financial health and stability.

A GTA business executive analyzing financial reports, symbolizing strategic corporate debt restructuring and a business pivot, in Ontario, with a Division I Proposal.
corporare debt restructuring

8. Brandon’s Corporate Debt Restructuring Take: Why Expertise Matters in Your Business Pivot

As Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a dedicated Licensed Insolvency Trustee, I’ve had the privilege of walking alongside countless Ontario business owners facing the profound fear and uncertainty that comes with financial distress. It’s a heavy burden, one that often impacts not only the business’s bottom line but also the personal well-being and mental health of the entrepreneur and his or her family.

My take is this: the Division I Proposal is not, and should never be viewed as, a “last resort” for businesses that have already failed. Instead, it is a highly sophisticated, strategic, and often proactive tool for smart, decisive business owners who recognize financial challenges early. It’s for those who choose to take control, proactively navigate their way back to prosperity, and ensure their company’s long-term viability. This process is fundamentally about preserving valuable assets, protecting jobs, and safeguarding the legacies you’ve worked so hard to build.

At Ira Smith Trustee & Receiver Inc., we do more than just process paperwork; we partner with you to meticulously craft a future for your business. We offer not only profound expertise in the intricacies of Canadian insolvency but also a deep sense of empathy and understanding for the challenges you face.

The complex requirements of the Bankruptcy and Insolvency Act, the delicate nuances of creditor negotiations (including with the CRA), and the critical timelines involved all demand the steady hand and seasoned judgment of an experienced Licensed Insolvency Trustee. Choosing the right expert is, without exaggeration, the single most important decision you will make on this journey. We are deeply committed to helping you transform financial distress into a powerful and successful business pivot.

9. Corporate Debt Restructuring FAQ Section: Understanding Your Division I Proposal Options

Here are answers to some of the most common questions Ontario business owners ask about Division I Proposals for corporate debt restructuring:

Q1: What is a Division I Proposal in Ontario, Canada?

A: A Division I Proposal in the GTA in Ontario, Canada, is a formal, legally binding offer made by an insolvent corporation (or an individual with significant debt exceeding $250,000, excluding their primary residence mortgage) to its unsecured creditors under the Bankruptcy and Insolvency Act (BIA). Its purpose is to restructure debt, allowing the business to continue operating while repaying a portion of what is owed, often over an extended period, in return for the balance of the debt eliminated. It provides immediate legal protection from creditors and aims to prevent corporate bankruptcy.

Q2: How does a BIA Division I Proposal differ from corporate bankruptcy in Canada?

A: A BIA Division I Proposal’s primary goal is to restructure debt and keep the business operating, preserving assets, jobs, and goodwill. In contrast, corporate bankruptcy in Canada involves the liquidation of a company’s assets to pay creditors, typically resulting in the cessation of business operations. While both offer a “stay of proceedings” from creditors, a proposal is a path to recovery and continuity, whereas bankruptcy is a path to formal closure and liquidation.

Q3: Why do creditors accept corporate debt restructuring proposals instead of forcing bankruptcy?

A: Creditors often accept corporate debt restructuring proposals because they are pragmatic and prefer a guaranteed recovery (e.g., a % on the dollar) over the high risk of receiving nothing in a corporate bankruptcy. In many bankruptcies, especially for unsecured creditors, the return is zero after liquidation costs. A well-structured Division I Proposal offers a more certain and, under the BIA, must be a higher financial return for creditors, making it a more attractive option.

Q4: What is the effect of a Division I Proposal on a business’s credit rating, and how can the business eventually recover?

A: Yes, similar to personal insolvency filings, initiating a Division I Proposal will negatively affect your business’s credit rating. However, completing the proposal by diligently adhering to the agreed-upon repayment schedule is the start of demonstrating financial responsibility and commitment. Making the proposal payments and all post-filing debt payments on time allows your business to systematically rebuild its creditworthiness over time, demonstrating a return to financial stability and reliability.

Q5: Can I include tax debts owed to the Canada Revenue Agency (CRA) in a Division I Proposal?

A: Yes, generally, certain tax obligations owed to the Canada Revenue Agency (CRA), such as corporate income tax and unremitted Harmonized Sales Tax (HST), can be included and restructured within a Division I Proposal. Debts related to unremitted source deductions need to be repaid in full, but the debtor is given additional time to pay off that debt. Directors should discuss potential personal liabilities for these with their LIT and their lawyer. A Licensed Insolvency Trustee has specialized experience in negotiating with the CRA and can effectively incorporate these complex tax debts into your comprehensive proposal.

Q6: How long does a Division I Proposal typically last?

A: While the Bankruptcy and Insolvency Act generally allows for proposals to extend up to five years, the actual duration can be longer in certain circumstances, if agreed upon by creditors and approved by the court. The specific length of your proposal depends on the terms negotiated with your creditors and approved by the court, balancing your business’s ability to pay with the creditors’ desire for timely recovery.

A GTA business executive analyzing financial reports, symbolizing strategic corporate debt restructuring and a business pivot, in Ontario, with a Division I Proposal.
corporare debt restructuring

10. Corporate Debt Restructuring Conclusion: Partnering with an Expert in Vaughan/GTA

Facing significant corporate financial distress is one of the most challenging experiences any business owner can endure. But it does not have to signal the end for your valuable enterprise. The Division I Proposal offers a powerful, strategic, and legally sound restructuring plan pathway to overcome overwhelming debt, comprehensively restructure your obligations, and ultimately secure a healthier, more sustainable future for your business. It’s an opportunity for your company to execute a decisive pivot, proving its resilience, strategic acumen, and commitment to long-term success.

Don’t let the immense weight of corporate debt restructuring define your business’s future. Instead, let it be the catalyst for a powerful and positive business pivot. If your Ontario business is grappling with financial challenges, seeking expert guidance early is not just beneficial—it is absolutely paramount. Delay can drastically limit your options and reduce your chances of a successful turnaround.

Located conveniently in Vaughan and proudly serving the entire Greater Toronto Area, our compassionate and highly experienced team of Licensed Insolvency Trustees at Ira Smith Trustee & Receiver Inc. is here to help. We offer confidential, no-obligation consultations where we will listen without judgment, thoroughly assess your unique financial situation, and help you explore whether a Division I Proposal is the right strategic path for your business to not just survive, but to truly thrive again.

Take the first crucial step towards a brighter financial future for your business. Contact Ira Smith Trustee & Receiver Inc. today to schedule your free initial consultation. Your business’s pivot to sustainable success starts now.

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing the possibility of legal action, contact Ira Smith Trustee & Receiver Inc. today. We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life. Take the first step towards a brighter financial future – call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy and is a member of the Canadian Association of Insolvency and Restructuring Professionals.

——————————————————————————–

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and my professional expertise as a licensed insolvency trustee. The information provided does not constitute legal or financial advice for your specific circumstances.

Every situation is unique and involves complex legal and factual considerations. The outcomes discussed in this article may not apply to your particular situation. Situations are fact-specific and depend on the particular circumstances of each case.

Please contact Ira Smith Trustee & Receiver Inc. or consult with qualified legal or financial professionals regarding your specific matter before making any decisions.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a licensed insolvency trustee serving clients across Ontario. With extensive experience in complex court-ordered receivership administration and corporate insolvency & restructuring proceedings, Brandon helps businesses, creditors, and professionals navigate challenging financial situations to achieve optimal outcomes.

Brandon stays current with landmark developments in Canadian insolvency law. He brings this cutting-edge knowledge to every client engagement, ensuring his clients benefit from the most current understanding of their rights and options.

A GTA business executive analyzing financial reports, symbolizing strategic corporate debt restructuring and a business pivot, in Ontario, with a Division I Proposal.
corporare debt restructuring
Categories
Brandon Blog Post

CORPORATE INSOLVENCY & RESTRUCTURING: FRESH STARTS FOR GREATER TORONTO AREA BUSINESSES REVEALED

Corporate Insolvency & Restructuring Introduction

As an entrepreneur in the Greater Toronto Area, you understand the daily pressures of running a business. With rising costs, inflation, high interest rates, and the need to repay loans, many businesses are struggling. It’s easy to feel overwhelmed when faced with financial challenges.

But you are not alone. Facing financial difficulty is not a failure; it’s an opportunity to find a path forward. There are clear corporate insolvency & restructuring solutions available to help Canadian businesses in Toronto and the wider GTA get back on track or close down in an orderly, dignified way.

This guide will clearly explain corporate insolvency & restructuring options under Canadian insolvency law, specifically for businesses in Ontario. My goal is to help you make informed decisions for a brighter future for your business and yourself. As a Licensed Insolvency Trustee or LIT, I am your trusted expert, here to provide clear, empathetic, and authoritative advice.


Corporate Insolvency & Restructuring Key Takeaways

  • Insolvency is a financial state (when you can’t pay your debts when they come due), while bankruptcy is a legal outcome. Many options exist before bankruptcy.
  • Acting early on warning signs is crucial. The sooner you seek help, the more corporate insolvency & restructuring options you have to save your business.
  • Licensed Insolvency Trustees are the only federally regulated professionals in Canada who can help corporations through formal corporate insolvency & restructuring processes like Bankruptcy and Insolvency Act Division I Proposals, CCAA Plans of Arrangement and corporate bankruptcy.
  • Formal options like a Division I Proposal can allow a viable business to restructure unmanageable debt and continue operating, protected from creditors.
  • For incorporated businesses, personal assets are often protected unless personal guarantees were made.
A business owner holding a key with the Toronto skyline in the background of a dark cloudy day with a beam of sunlight shining down through the clouds in the centre of the image symbolizing an entrepreneur with a financially troubled company who with the help of Ira Smith Trustee & Receiver Inc. Licensed Insolvency Trustee, has found the key to successful corporate insolvency & restructuring options for the entrepreneur's and other companies in the Greater Toronto Area.
corporate insolvency & restructuring

1. Understanding Corporate Financial Distress: Warning Signs for GTA Businesses

Understanding corporate financial distress means recognizing when your business is having trouble paying its bills. Many businesses in the Greater Toronto Area face financial struggles due to economic shifts, high operating costs, and market competition. Recognizing the warning signs early is crucial because the sooner you act, the more corporate insolvency & restructuring choices you will have to help your business recover or close in an organized way. Ignoring these signs can lead to bigger problems and fewer solutions.

1.1 What is Corporate Insolvency?

Corporate insolvency is a financial state where your business cannot meet its money obligations. Simply put, a business is insolvent when it cannot pay its bills on time, or when its total debts are greater than the current value of its total assets. It’s important to remember that insolvency is a financial condition – it’s about being unable to manage your debts. Bankruptcy, on the other hand, is a legal process that can happen because a business is insolvent. It’s one of the options, but definitely the last option, you might consider when facing insolvency.

1.2 Key Warning Signs Your Business is in Trouble

Identifying these red flags early can make a big difference in the future of your Toronto-area business. Pay close attention to these signals:

  • Cash Flow Problems: You are constantly struggling to pay your bills on time. This might mean late payments to suppliers, landlords, or employees. You might find yourself juggling payments, deciding which critical bill to pay each week.
  • Government Arrears: Falling behind on important payments to the Canada Revenue Agency (CRA) is a serious warning sign. This includes unremitted HST, payroll deductions (like income tax, Canada Pension Plan, and Employment Insurance), or other government obligations. Directors of a corporation can be held personally responsible for these specific debts, even if the business is incorporated.
  • Maxing Out Credit: Your business is always at its credit limit on lines of credit or credit cards, and you find it hard or impossible to get new loans or additional credit. This shows lenders no longer trust your business’s ability to repay.
  • Selling Assets to Survive: You are forced to sell valuable business assets like equipment, vehicles, or property just to cover daily operating costs, not to grow the business. This is a sign you are using your business’s long-term value to pay for short-term needs.
  • Creditor Pressure: You are receiving constant calls, demands for payment, threats of legal action, or demands for C.O.D. (cash on delivery) terms from your suppliers. This means your creditors are losing patience and trust.
  • Lack of Financial Information: You don’t have clear, up-to-date financial statements, budgets, or a business plan. Without this information, you can’t truly understand your business’s financial health or make smart decisions.
  • Declining Profitability: Your business is regularly showing monthly losses, or your sales are consistently dropping without clear reasons or a plan to reverse the trend. This affects your ability to generate enough money to cover costs.
  • Missed Opportunities: You can’t take advantage of new business opportunities because you lack funds or credit.

For businesses in the Greater Toronto Area, these signs can appear quickly due to the high operational costs and competitive markets. The urgency to identify and act on these issues early cannot be overstated. Waiting too long limits your corporate insolvency & restructuring choices and can make recovery much harder. If you see one or more of these signs, it’s time to seek professional advice.


2. Exploring Your Options: Corporate Insolvency & Restructuring Pathways in Ontario

When your business in Ontario faces financial distress, you have several pathways to explore, ranging from informal negotiations to formal legal corporate insolvency & restructuring processes. Understanding these options is key to making a strategic decision that best suits your company’s situation and objectives, whether you’re in Toronto, Vaughan, Markham, Mississauga, Brampton, or anywhere else in the GTA. These options represent the main ways a corporation can deal with insolvency and restructure its finances.

2.1 Informal Restructuring: The First Step Towards Recovery

Informal restructuring involves working directly with your creditors to make new payment arrangements or negotiate terms, often without formal legal proceedings. This approach is usually the first step for many businesses trying to fix financial problems.

  • What it is: This can involve calling your suppliers or landlord to ask for more time to pay, negotiating lower interest rates with a bank, or working out a temporary payment plan directly with your creditors. It’s about finding common ground and trying to solve problems outside of court.
  • Strategies: You might look at cutting unnecessary costs, improving how efficiently your business runs, finding new ways to generate income, or selling assets that aren’t essential to your core business operations. These steps aim to improve your cash flow and financial health.
  • When it Works: Informal restructuring works best for businesses with fewer creditors, especially those with whom you have good, long-standing relationships. It’s most effective when your financial issues are likely temporary, and you believe you can recover with some breathing room.
  • Limitations: The main limitation is that informal agreements may not stop legal action or prevent creditors from taking enforcement steps (like seizing assets or suing) if your problems are severe or widespread. Not all creditors may agree to new terms, and you have no legal protection from those who don’t.

2.2 Formal Restructuring under the Bankruptcy and Insolvency Act (BIA)

For many GTA businesses, informal efforts aren’t enough. That’s when formal corporate insolvency & restructuring options under federal law, specifically the Bankruptcy and Insolvency Act (BIA), become vital. These processes offer legal protection and a structured way to deal with debt.

Division I Proposals (Corporate Proposals): A Lifeline for Viable Businesses

A Division I Proposal, often called a Corporate Proposal, is a powerful tool for insolvent corporations in Ontario that have a chance to survive. The business may be financially sick, but it is still a viable business. It’s a formal, legally binding offer made by an insolvent corporation to its creditors. The offer can propose to pay back a percentage of what is owed, or extend the time to pay, or both. It is always and can only be administered by a Licensed Insolvency Trustee.

  • Definition: This process allows your business to negotiate a new payment plan with your unsecured creditors under the protection of the law. Instead of paying all your debts in full, you propose a new plan that creditors vote on. If accepted, it becomes legally binding on all unsecured creditors, even those who voted no.
  • Key Benefits:
    • Immediate Protection: Once your LIT files the paperwork, a “stay of proceedings” legally comes into effect. This immediately stops all unsecured creditors from taking collection action, garnishments, lawsuits, or other enforcement steps against your business. This gives you vital breathing room.
    • Business Continues: One of the biggest advantages is that your business can keep operating during the proposal process. This allows you to fix underlying issues, cut costs, or increase revenue, with the goal of returning to profitability.
    • Debt Reduction: In many cases, the business only pays back a portion of its unsecured debts. This can provide significant financial relief and make debts manageable.
    • Structured Plan: You work closely with an LIT to create a realistic and achievable payment plan that your business can afford based on its cash flow.
  • The Process:
  • Notice of Intention (NOI): The first step is often to file a Notice of Intention to Make a Proposal. This filing provides your business with immediate legal protection (the stay of proceedings) for an initial 30 days, which can be extended up to six months with the approval of the court. This time is used to prepare a detailed proposal.
    • Proposal Development: During this period, you and your LIT develop a formal offer to present to your creditors. This proposal outlines how much you will pay, over what period, and what terms will apply.
    • Creditor Vote: Once the proposal is prepared, a meeting of creditors is called. Creditors vote on the proposal. For it to be accepted, a majority (by number) representing two-thirds (by dollar value) of the voting unsecured creditors must agree to it.
    • Court Approval: If creditors accept the proposal, it must then be reviewed and approved by the court. Once approved, the proposal is legally binding on all unsecured creditors listed in the proposal, whether they voted for it or not.
  • Eligibility: Any insolvent corporation in Ontario and the rest of Canada that owes at least $1,000 in debt can file a Division I Proposal if it has a viable business that can be saved.

The LIT needs to file all official documents with the Office of the Superintendent of Bankruptcy.

2.3 The Companies’ Creditors Arrangement Act (CCAA): For Larger Corporations

While a Division I Proposal is suitable for most businesses, the Companies’ Creditors Arrangement Act (CCAA) is another federal law designed for corporate insolvency & restructuring.

  • Brief Explanation: CCAA proceedings are typically used for very large corporations with debts at or exceeding $5 million. It offers a more flexible and court-supervised restructuring process. The offer to the unsecured creditors to repay a portion of the debt is called a Plan of Arrangement.
  • Key Difference from BIA Proposal: CCAA proceedings are generally more complex, more costly, and involve a higher degree of court oversight. For small to medium-sized businesses in the GTA, a Division I Proposal under the BIA is almost always the more appropriate and cost-effective option.
A business owner holding a key with the Toronto skyline in the background of a dark cloudy day with a beam of sunlight shining down through the clouds in the centre of the image symbolizing an entrepreneur with a financially troubled company who with the help of Ira Smith Trustee & Receiver Inc. Licensed Insolvency Trustee, has found the key to successful corporate insolvency & restructuring options for the entrepreneur's and other companies in the Greater Toronto Area.
corporate insolvency & restructuring

3. Corporate Bankruptcy: When a Fresh Start Means Closing the Doors

Corporate bankruptcy is a formal legal process under the Bankruptcy and Insolvency Act where an insolvent corporation’s assets are taken over by an LIT, sold off, and the money is used to pay its creditors. While a Division I Proposal aims to save the business, bankruptcy means the business will close permanently. This path is usually chosen when the business is no longer viable and cannot be saved through restructuring. It provides a formal, orderly way to shut down an unviable business and manage its remaining debts.

3.1 What is Corporate Bankruptcy?

Corporate bankruptcy is the legal end of a business. It’s a process where an insolvent company’s assets are gathered by a Licensed Insolvency Trustee, sold, and the funds are distributed among its creditors according to legal priorities. The main outcome is that the corporation ceases to exist. This decision is typically made when the business has no reasonable chance of recovery and restructuring isn’t possible or practical. It provides a definite end, allowing all stakeholders to move on.

3.2 The Bankruptcy Process for a Corporation in Ontario

The process for a corporation entering bankruptcy in Ontario is structured and managed by an LIT:

  • Initiation: A corporation can voluntarily assign itself into bankruptcy by filing the necessary documents with an LIT. In some cases, creditors can petition the court to declare a corporation bankrupt, though this is less common for small and medium-sized businesses.
  • Role of the LIT: Once bankruptcy is filed, a Licensed Insolvency Trustee is appointed to manage the bankruptcy estate. The LIT takes legal possession of all the corporation’s assets, such as inventory, equipment, accounts receivable, and real estate. The LIT’s role is to sell these assets for the best possible value and distribute the funds to the creditors according to a strict legal order of priority set out in the BIA. The interest in the assets of the LIT is subject to the rights of the secured creditors.
  • No Personal Assets (Generally): For most incorporated businesses, the personal assets of the directors or owners are generally protected. This is because a corporation is a separate legal entity from its owners. However, there are very important exceptions, especially if personal guarantees were made or for specific government debts (see Section 5).
  • Termination: Once all assets are liquidated (sold) and the funds are distributed to creditors, the bankruptcy administration is completed. The corporation ceases to exist. This provides a clean break for the business and its owners.

3.3 Priority of Creditors in Corporate Bankruptcy

Understanding the order in which creditors are paid is vital for business owners, especially those in the Greater Toronto Area, dealing with many different types of debt.

  • Trust Claimants: These are creditors given a trust claim under a provincial or federal law. The most common one found in a corporate bankruptcy is the CRA for unremitted payroll source deductions. They are paid first.
  • Secured Creditors: These are creditors who have a registered claim against specific assets of the business (e.g., a bank with a loan secured by a mortgage on property, or a financing company with a lien on equipment). They are paid next from the sale of those specific assets. If the sale of the asset doesn’t cover their full debt, they become unsecured creditors for the remaining balance.
  • Preferred Creditors: Certain types of unsecured creditors are given priority over general ordinary unsecured creditors. This includes the fees and expenses of the Licensed Insolvency Trustee for administering the bankruptcy. It also includes certain unpaid wages, salaries, commissions, and the claim of landlords for rent arrears, all up to certain legal limits.
  • Unsecured Creditors: Most other creditors fall into this category. This includes suppliers, credit card companies, utility providers, and often the CRA for general income taxes (not source deductions). In a corporate bankruptcy, for unremitted HST, CRA is an unsecured creditor. These creditors share any remaining funds proportionally after trust claimants, secured and preferred creditors have been paid. In many corporate bankruptcies, unsecured creditors receive only a small percentage of what they are owed, or sometimes nothing at all.

Knowing this priority helps business owners understand what to expect and which debts might continue to be a concern if personal guarantees or director liabilities are involved.


4. Comparison Table: Division I Proposal vs. Corporate Bankruptcy in Ontario

When an Ontario business faces financial challenges, entrepreneurs in the Greater Toronto Area need to understand the key differences between a Division I Proposal and Corporate Bankruptcy. This table provides a clear overview to help you compare these two formal options.

Feature

Division I Proposal (corporate insolvency & restructuring)

Corporate Bankruptcy

Primary Goal

To allow a viable business to keep operating, restructure its debts, and return to profitability.

To liquidate assets, formally close down the business, and legally discharge its corporate debts.

Business Continues?

Yes, the business continues to operate under the terms of the approved proposal.

No, the corporation is dissolved and ceases to exist permanently.

Debt Reduction?

Creditors typically accept a reduced amount (e.g., 20-50 cents on the dollar) or extended payment terms.

The unpaid balance of corporate debts included in the Division I Proposal is legally discharged (after successful completion).

Unsecured corporate debts are legally discharged (after assets are liquidated).

Creditor Protection?

An immediate “stay of proceedings” halts all unsecured creditor actions (lawsuits, garnishments, collection calls).

An immediate “stay of proceedings” halts all creditor actions against the corporation.

Court Involvement?

Requires court approval after creditors vote to accept the proposal.

A court order often initiates (for involuntary) but not if the bankruptcy is voluntary. The LIT oversees the bankruptcy administration and applies to court at the end for approval of the Final Statement of Receipts and Disbursements and to obtain the LIT’s discharge.

Public Record?

Yes, details are part of the public record maintained by the Office of the Superintendent of Bankruptcy (OSB).

Yes, details are part of the public record maintained by the Office of the Superintendent of Bankruptcy.

Cost

Includes

LIT fees, potentially higher overall costs due to ongoing operations and the complexity of the restructuring plan.

Primarily

LIT fees; often lower overall as the focus is on liquidation, not ongoing operations.

Impact on Directors/Owners

Directors continue to manage the business and can potentially protect personal assets (if no guarantees).

No direct personal liability for corporate debt (unless personal guarantees and director liabilities exist).

Timeline

Flexible; preparation takes months, and payments can extend up to five years, but there is no statutory limit on length.

Typically, 9 to 36 months for assets to be sold and funds distributed, depending on complexity.

This comparison highlights that a Division I Proposal is for businesses that can be saved, offering a path to recovery, while corporate bankruptcy is for businesses that need an orderly closure. Your choice depends on the viability of your business and your long-term goals.

A business owner holding a key with the Toronto skyline in the background of a dark cloudy day with a beam of sunlight shining down through the clouds in the centre of the image symbolizing an entrepreneur with a financially troubled company who with the help of Ira Smith Trustee & Receiver Inc. Licensed Insolvency Trustee, has found the key to successful corporate insolvency & restructuring options for the entrepreneur's and other companies in the Greater Toronto Area.
corporate insolvency & restructuring

5. Protecting Your Personal Assets as a GTA Entrepreneur

As an entrepreneur in the Greater Toronto Area, understanding how your personal assets are protected or exposed when your business faces financial trouble is vital. Many business owners believe that incorporating their business fully shields them, but there are important exceptions.

The Power of Incorporation:

A key reason many entrepreneurs in Ontario choose to incorporate their business is to create a legal separation between the business and their personal finances. Generally, if your business is incorporated, you, as an owner or director, are not personally responsible for its debts. The corporation is a separate legal entity, meaning it is the business that owes the money, not you personally. This offers a valuable layer of protection for your home, savings, and other personal assets.

Personal Guarantees: Be Aware of the Risks

While incorporation offers protection, personal guarantees are a major exception. If you have personally guaranteed business loans, lines of credit, or leases (which is very common, especially with banks for small to medium-sized businesses in the GTA), your personal assets can be at risk if the business defaults. When you sign a personal guarantee, you are essentially promising to repay the business’s debt from your own pocket if the company cannot. This means that creditors can pursue your personal assets, such as your home, car, or personal savings, to recover the debt. It’s crucial to understand what you’ve signed and the potential personal liability involved.

Director Liabilities: Specific Debts You’re Responsible For

In Ontario (and the rest of Canada), even with an incorporated business, directors of corporations can be held personally liable for certain statutory debts. These are debts owed to the government or employees, and they are distinct from general business debts. The most common examples include:

  • Unremitted Payroll Source Deductions: Income tax, Canada Pension Plan (CPP), and Employment Insurance (EI) amounts that you’ve deducted from your employees’ paycheques but haven’t sent to the Canada Revenue Agency. These funds are considered to be held “in trust” for the government, and directors have a duty to ensure they are remitted.
  • Unremitted GST/HST: Goods and Services Tax / Harmonized Sales Tax (HST) that your business has collected but not sent to the CRA. This is also considered trust money.
  • Unpaid Employee Wages: In some cases, directors can be personally liable for a limited amount of unpaid wages owed to employees.

Always ensure these specific types of debts are paid on time. Falling behind on them can put your personal finances at significant risk, even if your corporation goes through bankruptcy.

Smart Planning:

  • Document Personal Loans: If you lend money to your business, properly document it with a loan agreement and ideally register a General Security Agreement (GSA) against the company’s assets. This could allow you to recover some of your investment in a formal insolvency.
  • Consult an LIT: To truly understand how to best protect your personal finances during business difficulties, it’s essential to consult with a Licensed Insolvency Trustee. They can review your specific situation, including any personal guarantees, and advise you on the best course of action.

6. Choosing the Right Licensed Insolvency Trustee in the Greater Toronto Area

When your business in the Greater Toronto Area is facing financial distress, selecting the right professional to guide you through corporate insolvency & restructuring is one of the most important decisions you’ll make. A Licensed Insolvency Trustee is not just a consultant; we are the only federally licensed and regulated professionals in Canada legally authorized to administer formal insolvency processes like corporate proposals or corporate bankruptcies.

Why an LIT is Essential:

An LIT plays a critical role as an impartial expert in Canadian insolvency law. We don’t represent just your creditors or just your interests; we are legally mandated to act fairly for all parties involved. This means we offer unbiased advice, explain all your available options (not just the ones that benefit us), and ensure that the process follows the strict rules set out in the Bankruptcy and Insolvency Act. We have the legal authority and expertise to provide the formal protection you need and to negotiate with your creditors on your behalf. Without an LIT, your business cannot access the legal protections and debt restructuring benefits of a formal proposal or bankruptcy.

What to Look For:

When choosing an LIT for your business in Toronto or the GTA, consider these factors:

  • Corporate Insolvency Expertise: Ensure they specialize in business debt and corporate restructuring, not just personal insolvency. Corporate insolvency has its own complexities, and you need an expert who understands the nuances of business operations and director liabilities.
  • Local Knowledge: A trustee familiar with the Greater Toronto Area market understands local economic factors, industry trends, and specific challenges that businesses in Ontario might face. This local insight can be invaluable in crafting practical solutions.
  • Empathetic & Non-Judgmental: Facing business insolvency can be incredibly stressful and isolating. You need someone who listens without judgment, treats your situation with respect, and provides reassuring guidance. A good LIT acts as a trusted advisor, not just a legal administrator.
  • Clear Communication: The world of insolvency law can be complex. Your LIT should be able to explain all your options, the processes involved, and potential outcomes in clear, simple language that you can easily understand, at a Grade 9 reading level.
  • Free Consultation: A reputable LIT will always offer a confidential, no-obligation initial consultation. This allows you to explain your situation, understand your choices, and get a sense of their approach before committing to anything.

Ira Smith Trustee & Receiver Inc.:

At Ira Smith Trustee & Receiver Inc., we have extensive experience helping entrepreneurs across the GTA navigate complex corporate financial challenges and corporate insolvency & restructuring options. We understand the unique pressures of the Toronto business landscape. We approach every situation with professionalism, compassion, and a deep commitment to finding the most strategic path forward for your business and your peace of mind. We are here to ensure you get a fair, fresh start.

A business owner holding a key with the Toronto skyline in the background of a dark cloudy day with a beam of sunlight shining down through the clouds in the centre of the image symbolizing an entrepreneur with a financially troubled company who with the help of Ira Smith Trustee & Receiver Inc. Licensed Insolvency Trustee, has found the key to successful corporate insolvency & restructuring options for the entrepreneur's and other companies in the Greater Toronto Area.
corporate insolvency & restructuring

7. Corporate Insolvency & Restructuring Frequently Asked Questions (FAQs)

Entrepreneurs in the Greater Toronto Area often have many questions when considering corporate insolvency & restructuring. Here are answers to some common concerns, providing practical information to help you understand your options and the support available.

Q1: Can a small business in Toronto file a Consumer Proposal?

A: No, a Consumer Proposal is only for individuals who owe less than $250,000 (excluding a mortgage on their principal residence). Corporations are distinct legal entities. If a corporation wants to restructure its debts and avoid bankruptcy, it must file a Division I Proposal (often called a Corporate Proposal) under the Bankruptcy and Insolvency Act. This is a different process tailored to businesses.

Q2: What happens to employees when a company goes through corporate insolvency?

A: If the business files a Division I Proposal, the goal is to continue operations. Therefore, employees usually keep their jobs, and their employment continues under the restructured business. However, it is possible that one of the reasons for the employer’s insolvency is too high payroll costs and it may be necessary to shed some employees. In a corporate bankruptcy, the company closes, and employees are terminated by the bankruptcy. In this situation, the Wage Earner Protection Program Act (WEPPA) may offer some financial protection for unpaid wages, holiday pay, and severance owed to employees, up to a certain maximum amount. The LIT is obligated to provide details to the former employees of the bankrupt company.

Q3: How long does the corporate insolvency process take in Ontario?

A: The timeline varies depending on the chosen path. A Division I Proposal typically takes a few months to get approved by creditors and the court. The payment plan under a proposal usually involves payments over a period of up to five years, but there is no statutory maximum for its length. Corporate bankruptcy typically takes 9 to 36 months to complete, depending on how complex the assets are and how long it takes to sell them and distribute funds to creditors. The more complex business problems that exist, the longer the process generally will take.

Q4: Will my credit score be affected by corporate insolvency?

A: Yes, formal insolvency proceedings (either a Division I Proposal or corporate bankruptcy) will negatively affect the corporation’s credit history. This record is permanent. If you, as a director or owner, provided personal guarantees for the business’s debts (e.g., bank loans or credit lines), your personal credit score will also be impacted.

Q5: What is the difference between a “workout” and formal restructuring?

A: A “workout” is an informal agreement made directly between a business and its creditors, outside of any legal framework. It relies on voluntary cooperation. Formal restructuring, such as a Division I Proposal or a filing under the CCAA, is a legal process under federal law. It provides specific legal protections (like a stay of proceedings) from creditors and results in a legally binding scheme of arrangement that applies to all unsecured creditors once approved. Formal restructuring offers greater certainty and protection than an informal workout.

Formal corporate restructuring in Canada is the equivalent of Chapter 11 bankruptcy protection in the United States.

Q6: What if my business debts include money owed to the Canada Revenue Agency?

A: Debts owed to the CRA, including unremitted HST and payroll source deductions, are definitely considered in both Division I Proposals and corporate bankruptcies. However, it’s crucial to understand that directors can be held personally liable for these types of corporate debts, even if the corporation enters bankruptcy or files a proposal. Addressing these critical liabilities early with your LIT is essential, as they often require special attention in any restructuring or liquidation plan.


Brandon’s Take (Expert Authority) on Corporate Insolvency & Restructuring

As a Licensed Insolvency Trustee and active insolvency practitioner serving the Greater Toronto Area, I’ve had the privilege of guiding countless entrepreneurs through their most challenging corporate insolvency & restructuring business moments.

What I’ve learned is that seeking help is never a sign of failure; it’s a profound act of leadership and courage. The landscape of business debt and insolvency can feel overwhelming, especially for dedicated business owners in Toronto and across Ontario. But you don’t have to navigate it alone. My team and I are here to provide clear, empathetic, and authoritative advice, helping you understand your unique situation and find the most strategic path forward for your business and your peace of mind. Your business deserves a chance at a fresh start.

A business owner holding a key with the Toronto skyline in the background of a dark cloudy day with a beam of sunlight shining down through the clouds in the centre of the image symbolizing an entrepreneur with a financially troubled company who with the help of Ira Smith Trustee & Receiver Inc. Licensed Insolvency Trustee, has found the key to successful corporate insolvency & restructuring options for the entrepreneur's and other companies in the Greater Toronto Area.
corporate insolvency & restructuring

Corporate Insolvency & Restructuring Conclusion

Facing corporate financial challenges in the Greater Toronto Area can be daunting, but there are proven legal pathways, from informal restructuring to formal proposals and bankruptcy, that offer a solution. The most important step you can take is to act early and seek professional guidance. Delaying action can significantly limit your options and increase stress.

Remember, the goal is not just to resolve debt, but to pave the way for a more stable future, whether that’s through a revitalized business or a dignified and orderly closure.

Don’t let uncertainty or fear prevent you from exploring your options. If your business in Toronto, Vaughan, Markham, Mississauga, Brampton, or anywhere in the wider GTA is experiencing financial difficulty, contact the insolvency practice of Ira Smith Trustee & Receiver Inc. today for a confidential, no-obligation consultation. We are here to listen, assess your situation, and help you chart the best course forward, Starting Over Starting Now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy and is a member of the Canadian Association of Insolvency and Restructuring Professionals.

Contact Ira Smith Trustee & Receiver Inc. Today:

  • Phone: 905.738.4167
  • Toronto line: 647.799.3312
  • Website: https://irasmithinc.com/
  • Email: brandon@irasmithinc.com

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and my professional expertise as a licensed insolvency trustee. The information provided does not constitute legal or financial advice for your specific circumstances.

Every situation is unique and involves complex legal and factual considerations. The outcomes discussed in this article may not apply to your particular situation. Situations are fact-specific and depend on the particular circumstances of each case.

Please contact Ira Smith Trustee & Receiver Inc. or consult with qualified legal or financial professionals regarding your specific matter before making any decisions.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a licensed insolvency trustee serving clients across Ontario. With extensive experience in complex court-ordered receivership administration and corporate insolvency & restructuring proceedings, Brandon helps businesses, creditors, and professionals navigate challenging financial situations to achieve optimal outcomes.

Brandon stays current with landmark developments in Canadian insolvency law. He brings this cutting-edge knowledge to every client engagement, ensuring his clients benefit from the most current understanding of their rights and options.

A business owner holding a key with the Toronto skyline in the background of a dark cloudy day with a beam of sunlight shining down through the clouds in the centre of the image symbolizing an entrepreneur with a financially troubled company who with the help of Ira Smith Trustee & Receiver Inc. Licensed Insolvency Trustee, has found the key to successful corporate insolvency & restructuring options for the entrepreneur's and other companies in the Greater Toronto Area.
corporate insolvency & restructuring
Categories
Brandon Blog Post

CERB CANADA: THE ENORMOUS DEBT PROBLEM NOW FACING CANADIANS

The Canada Emergency Response Benefit (CERB Canada) has been closed but is not over

The government is ramping up its efforts to verify CERB Canada eligibility for payments made under the Canada pandemic support program. Many Canadians have been told to return some or all of the funds received in the past. The Canada Revenue Agency (CRA) and Employment and Social Development Canada are working together to ensure that those who received COVID-19 pandemic individual benefits were eligible for them. CRA also announced that they are sending out Notices of Redetermination to Canadians who were ineligible for some or all of the CERB Canada benefits they received.

The CERB Canada benefit was rolled out quickly and there was a lot of confusion about who was eligible for it. It was created to help those in Canada who the COVID-19 pandemic directly impacted. The program provided financial assistance to employees and self-employed workers. The benefit was worth a maximum of $2,000 every 4-week period for up to four months.

The issue that troubles me is that the benefit was mostly paid to people who otherwise would not have been able to afford rent or food. The CERB Canada benefit money was spent immediately and a long time ago. So if CRA and Service Canada have now determined that some people should not have gotten that benefit, what are those people supposed to do if CRA demands the money back?

In this Brandon’s Blog, I discuss what the options may be for people who receive a demand for repayment of the CERB Canada benefit.

Who was eligible for CERB Canada?

To qualify for the CERB payment from the government support program, you must have met certain conditions during the period you applied. The Government of Canada stipulated the following eligibility criteria:

  • You did not look for or receive, CERB Canada or Employment Insurance benefits from Service Canada for the same qualification period.
  • You did not stop your work willingly on your own. You were forced to stop your work by someone else.
  • You are a Canadian resident who is at least 15 years old.
  • You must have earned at least $5,000 (before taxes) in the preceding 12 months, or in 2019, from one or more of the following:
    • job income
    • self-employment income earnings
    • benefits relating to pregnancy or parental leave from the province

The program was designed to help Canadian employees and self-employed Canadians who lost their jobs or saw a significant decrease in income due to the COVID-19 pandemic and the COVID-19 lockdown order resulting in business shutdowns. The program came to an end on December 2, 2020.cerb canada

Sending your CERB Canada payment back

If you have received a letter from Service Canada asking you to repay an overpayment, the CRA says you need to follow the instructions on the letter to return the payment.

You will have the opportunity to provide more evidence to support your claim that you were entitled to the CRA’s full CERB benefit payment. Based on your responses, you may need to repay the full amount you received.

If you received any CERB Canada payments and they now say you didn’t fit into the group of eligible workers, you have the option to pay back what you owe in full right now or over time. They expect you to repay it in full either way.

Now consider this. The federal government paid nearly $12 million in CERB Canada payments to more than 1,600 people with foreign addresses during the first seven months of the pandemic! How did that happen if one of the criteria of this program was you had to be a resident of Canada?

The way the CERB Canada benefit is taxed is by taking it out of your paycheque – wasn’t that enough?

The CERB Canada benefit was not a grant or any other kind of freebie. Anyone who received it had to include it in their taxable income. That is fair because the benefit was meant to replace lost income.

In April 2020, Prime Minister Trudeau announced that the Government of Canada would be taking extensive and decisive action to support Canadians and businesses who were struggling due to the COVID-19 global pandemic through an expansion of this program.

The Prime Minister went on to say that no Canadian should have to choose between protecting their health, putting food on the table, paying for their medication or caring for a family member. He said this is why the government introduced the CERB Canada Benefit, a taxable benefit.

There have even been CRA, Employment and Social Development Canada and court decisions confirming that the CERB Canada payments are taxable and that it was definitely not a free ride. The demand for repayment of benefits from Canadians who CRA and Service Canada now feel were not eligible workers seems totally anti-social. The program was rolled out hastily and under unclear, confusing circumstances, and Canadians have been paying income tax on the benefits they received. Surely our federal government has better places to spend its time clawing back wasteful spending.cerb canada

Mom was shocked when her maternity leave benefits were cut in half due to the CERB Canada benefit

A mother was shocked to see that her most recent parental benefits instalment had been cut in half. She said that maternity and parental benefits are paid to parents so they can take time off from paid work to do another kind of work: care work.

She was receiving half of her parental leave benefits for three weeks, which were already about half of her regular earnings. The reason for the reduction was because it was determined that the CERB Canada benefit she received for every four-week period, increased her income to the point where the reduction was warranted.

Then she received a demand for repayment. She hadn’t expected to have to repay the benefit. Shortly after the COVID-19 outbreak hit in March 2020, she was let go from her work because there wasn’t enough work to go around. She thought she qualified under the eligibility requirements for the CERB Canada benefit.

She couldn’t repay the full amount in one shot so she tried to arrange a repayment plan with CRA. She said that she had to fax about a dozen documents and field several questions from federal government employees to prove she is experiencing “financial hardship” in order to qualify for a payment plan. I don’t understand why payment plans have to be approved rather than just being automatically set up. These are not rich people that they are demanding repayment from, so why make them jump through hoops?

The British Columbia court has ruled that the CERB Canada payment must be deducted from the damage award for wrongful dismissal

Here is another example that the CERB Canada benefit is not a tax-free payment or a non-taxable grant. In Reotech Construction Ltd. v Snider, 2022 BCSC 317 the trial judge awarded the employee damages for a 4.5-month reasonable notice period and declined to deduct his CERB Canada payments.

After reviewing the case, the Supreme Court of British Columbia decided that the original trial judge was incorrect in choosing not to reduce the damage award by the $9,000 in benefits received. The court decided that these payments should be deducted from the award.

There was no indication that the employee would have to repay the CERB Canada benefit to the government. If the CERB payments are not deducted, then the employee would be in a better position than if there had been no breach of the employment contract. The employee would not have received the benefit if he had not been dismissed, making the benefit an indemnity for the wage loss caused by the dismissal.cerb canada

How to repay the CERB Canada benefit

If you received the CERB Canada and now find out that you did not meet the eligibility requirements, as shown above, you must repay the money. There are a few different ways that you can repay the amount demanded.

The easiest way to repay the CERB Canada amount is through your online service CRA My Account. You can log into your account and select “Repay CERB” under the “My Account” tab. If you do not have a CRA online account, you can repay the amount you owe either by sending a cheque through Canada Post to the CRA mailing address you can find online. You can also pay it at your financial institution using the government-issued remittance form.

But what if you are just one of the many hard-working Canadian workers living paycheque to paycheque? What if you do not have the money to repay what they say you owe, either all at once or by taking an amount out of each of your future paycheques that CRA will agree to?

What if you cannot repay because the government stepped up its efforts to verify CERB Canada payments and made demands on you?

As stated above, if you cannot afford to repay the full amount being demanded of you all at once, you can hopefully convince CRA that you deserve a payment plan over time due to “financial hardship”. This assumes that the government is right that you were not originally entitled to the amount that you received for the CERB Canada benefit. But what if you cannot afford to repay it at all, no matter what sort of payment plan you can enter into?

The outcome will depend on if you are insolvent. Being insolvent doesn’t necessarily mean bankruptcy. Insolvency (aka financial failure) is a financial condition that occurs when a person or company doesn’t have enough assets to pay off all debts if they were to be liquidated. It also means that the person or company has stopped paying their bills on time in the normal course.

If the person is NOT insolvent, they are expected to sell assets or use cash on hand to pay their bills.

If you’re insolvent, you can take advantage of Canadian insolvency legislation, the Bankruptcy and Insolvency Act (Canada) (BIA). The debt to repay the CERB Canada benefit is an ordinary unsecured claim that will be eliminated through a successful financial restructuring under either a consumer proposal or a Division I proposal. As a last resort, you could also file for bankruptcy.

I would rather refer you back to some of my earlier Brandon’s Blogs that go over the requirements for each insolvency option, rather than go through all of them individually here. They are:

  1. Consumer proposal –CONSUMER PROPOSAL TORONTO: THE COMPLETE #1 WAY TO ELIMINATE DEBT IN ONTARIO
  2. Division I Proposal –THE EASIEST WAY TO ACTUALLY LIKE WHAT IS A DIVISION i PROPOSAL ONTARIO
  3. Personal bankruptcy – BEYOND BANKRUPTCY SERVICES: OUR BEST PERSONAL INSOLVENCY FAQ 2 JUMPSTART YOUR FINANCIAL LIFE

CERB Canada: Canadian workers now under fire

In summary, CRA now says it’s “time to pay up” for Canadians who were paid the CERB Canada benefit during the pandemic. Although CRA has a right to claw back the amount if it is correct that the person was not eligible, what CRA’s insistence means for many Canadian workers is they now have to choose between paying back their CERB or paying for food, rent or medicine.

This is so ironic because the benefit payments were designed to help those people in making those payments when their incomes dried up. The amounts were taxed so the government earned income that way. Now they are causing unneeded stress and worry to the people they aimed to help.

I hope this Brandon’s Blog was helpful to you in understanding more about this problem now facing many Canadians. If you or your company has too heavy a debt load, we understand how you feel. You’re stressed out and anxious because you can’t fix your or your company’s financial situation on your own. But don’t worry. As a government-licensed insolvency professional firm, we can help you get your personal or corporate finances back on track.

If you’re struggling with money problems, call the Ira Smith Team today. We’ll work with you to develop a personalized plan to get you back on track and stress-free, all while avoiding the bankruptcy process if at all possible.

Call us today and get back on the path to a healthy stress-free life.cerb canada

Categories
Brandon Blog Post

LICENSED INSOLVENCY TRUSTEE VAUGHAN: THE COMPLETE GUIDE FOR YOUR HAPPY DEBT FREE L1FE

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic.

Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. Through the use of video meetings, we can help you even if you do not live close to our office in the Jane Street Hwy. 7 area. It is just like we are coming to you!

The bankruptcy trustee in Vaughan: We transformed into a licensed insolvency trustee Vaughan

The bankruptcy trustee in Vaughan went through a metamorphosis similar to a caterpillar becoming a butterfly. The term “bankruptcy trustee” turned into a “licensed insolvency trustee“. The licensed insolvency trustee designation was mandated to all licensed trustees by the Industry Canada Office of the Superintendent of Bankruptcy (OSB). The OSB licenses and supervises the activities of all licensed insolvency trustees across Canada. This includes us as a licensed insolvency trustee Vaughan, Ontario.

The purpose of this Brandon blog is to offer an overview of our role in the Greater Toronto Area with our licensed insolvency trustee Vaughan insolvency trustee firm head office.

The purpose of this Brandon blog is to offer an overview of our role in the Greater Toronto Area with our licensed insolvency trustee Vaughan insolvency trustee firm head office.

Role of a Licensed Insolvency Trustee Vaughan (formerly called Trustee in Bankruptcy Vaughan)

A licensed insolvency trustee Vaughan can fulfill various roles. It all starts with providing a no-cost consultation for a person or company that finds themselves in a troubling financial situation that worries them about their prospects for a bright financial future.

Due to the various roles, a licensed insolvency trustee Vaughan can play, we are also known as “receivers”, “trustee in bankruptcy” or “financial restructuring professionals”. We are appointed when a company or person is financially distressed and either has no other options to get out of financial difficulty and is unable to pay its bills. A licensed insolvency trustee is the only party licensed by the Government of Canada to perform a federal government-approved debt settlement plan, being a consumer proposal consolidation.

As a licensed insolvency trustee Vaughan firm, there are different roles we can play.

licensed insolvency trustee vaughan

Find the right option with the help of a Licensed Insolvency Trustee Vaughan

Personal situation insolvency

For individuals who are insolvent, we can provide and act in the following:

  • A no-cost initial consultation to provide advice about debt relief.
  • Credit counselling. to help with your household budget and determine if you really need one of the available debt relief options.
  • Consumer Proposal – Toronto and GTA – Act as Consumer Proposal Administrator to conduct a Consumer Proposal Process for people who owe $250,000 or less in unsecured debts (not including any debts registered against their home) who wish to eliminate their debt and wish an alternative to bankruptcy so that they can avoid filing bankruptcy. This is a government-approved interest-free debt settlement plan that can be paid over as much as five years.
  • Division I Proposal – Toronto and GTA – This process is not quite as streamlined as a consumer proposal, but it is for people who wish to eliminate their debt while avoiding personal bankruptcy.
  • These 2 proposal remedies are the only accredited government debt relief programs in Canada.
  • Personal bankruptcy – Toronto and GTA – As a licensed insolvency trustee Vaughan, we can of course assist anyone who wishes filing for bankruptcy. In your no-cost consultation with us, we first get to know you and your financial situation in order to determine if you qualify for one of the bankruptcy alternatives. If not, we will discuss the entire bankruptcy process with you, including the cost of bankruptcy. If you wish to proceed, we will accept your assignment in bankruptcy.

All collection activities against you cease when you make an assignment in bankruptcy, or file a debt settlement restructuring proposal. Legal action against you may include wage garnishment, collection calls, or a legal action against you. You get legal protection as a result of the stay of proceedings afforded by an insolvency filing.

The two most common types of debt we encounter in our personal insolvency practice are credit card debt and income tax debt. We have successfully handled for clients serious negotiations with Canada Revenue Agency in order to achieve debt settlement for people with a financial history of income tax debt.

Corporate insolvency

For companies, and especially entrepreneurial family businesses that are insolvent, we can provide and act in the following:

  • A no-cost initial consultation to provide advice about debt restructuring options.
  • Restructuring & Turnarounds.
  • Business analysis, business review and monitoring.
  • Receivership – Toronto and GTA – Only a licensed insolvency trustee can act as a receiver on behalf of a secured creditor. As a licensed insolvency trustee Vaughan, we act as a privately-appointed receiver on behalf of a secured creditor. We also act as a court-appointed receiver upon the application to a court by a secured creditor or other stakeholders.
  • Winding-Up and Liquidator – Toronto and GTA – For solvent companies that wish to wind up operations through a legal process, we act as either privately appointed or court-appointed Liquidator.

    licensed insolvency trustee vaughan
    licensed insolvency trustee vaughan

Selecting The Right Licensed Insolvency Trustee in Vaughan

Experience and professionalism

You might not find the expertise to solve your financial difficulties with someone just around the corner. You can start your search for the right Trustee by visiting the website of the Canadian Association of Insolvency and Restructuring Professionals. Both Ira Smith and Brandon Smith are members of the Canadian Insolvency and Restructuring Professional Association. It shows an individual’s commitment to staying up to date with all the latest industry advancements by belonging to this organization. Check the website of the OSB to ensure that the Trustees you are considering are not suspended or under file management by the regulator.

Interacting with them on many levels is essential

As a beginning, they must be able to quickly understand your needs and desires, as well as provide you with a realistic plan that can be followed. If you have issues or concerns, they also need to be available to you. Look for their interest in you. How enthusiastic are they about their industry? Do you really feel their compassion for you? Do you feel you are going to get along on an inter-personal basis with this person?

That’s exactly how you measure enthusiasm. The most effective solutions and suggestions will be offered by a knowledgeable insolvency trustee. You may not find this type of person within walking distance of your home or workplace.

licensed insolvency trustee vaughan

Licensed insolvency trustee Vaughan: Are you able to agree on the same concepts?

It is not a totally free service to engage a professional trustee. The complexity of your situation could affect the bankruptcy cost. Your trust in a bankruptcy trustee is diminished if you feel they view you as just another dollar sign. Look for those who seem to have similar values to you. It may not be the closest to your home to find such a licensed insolvency trustee.

Websites for licensed insolvency trustee Vaughan

Searching for “bankruptcy trustee near me” or “licensed insolvency trustee Vaughan” on a search engine today will bring up various websites to visit. How does the website make you feel? What bankruptcy FAQs do they provide? Can you see pictures of the people you would deal with? From their blog, do they demonstrate that they have a deep knowledge base?

licensed insolvency trustee vaughan

You can meet with more than one Trustee

Unless you sit across the table from him or her, you won’t know which one is the right fit for you. Comparing two bankruptcy trustees is a good idea. You want to be able to compare two or more for your own validation purposes. The one you feel best about is the one to go with. Trust your gut!

3 Best Licensed Insolvency Trustees in Vaughan, ON

Throughout the years my firm has been inspected for 50 points, including reviews, ratings, reputation, history, complaints, satisfaction, trust, cost, and general excellence. The results have allowed us to rank consistently among the top 3 Best Licensed Insolvency Trustees in Vaughan, ON.

Licensed insolvency trustee Vaughan summary

I hope that you found this licensed insolvency trustee Vaughan Brandon Blog helpful in describing our role as debt professionals and my thoughts on how to go about choosing the one you think is the best fit for anyone in a financial crisis. Problems will arise when you are cash-starved and in debt. There are several insolvency processes available to a person or company with too much debt.

If you are concerned because you or your business are dealing with substantial debt challenges, you need debt help and you assume bankruptcy is your only option, call me.

It is not your fault that you remain in this way. You have actually been only shown the old ways to try to deal with financial issues. These old ways do not work anymore.

The Ira Smith Team utilizes new modern-day ways to get you out of your debt difficulties with debt relief options as alternatives to bankruptcy. We can get you the relief you need and so deserve. Our professional advice will create for you a personalized debt-free plan for you or your company during our no-cost initial consultation.

The tension put upon you is big. We know your discomfort factors. We will check out your entire situation and design a new approach that is as unique as you and your problems; financial and emotional. We will take the weight off of your shoulders and blow away the dark cloud hanging over you. We will design a debt settlement strategy for you. We know that we can help you now.

We understand that people with credit cards maxed out and businesses facing financial issues need a realistic lifeline. There is no “one solution fits all” method with the Ira Smith Team. Not everyone has to file bankruptcy in Canada. The majority of our clients never do as we know the alternatives to bankruptcy. We help many people and companies stay clear of filing an assignment in bankruptcy.

That is why we can establish a new restructuring procedure for paying down debt that will be built just for you. It will be as one-of-a-kind as the economic issues and discomfort you are encountering. If any one of these seems familiar to you and you are serious about getting the solution you need to become debt-free, contact the Ira Smith Trustee & Receiver Inc. group today.

Call us now for a no-cost consultation.

We hope that you and your family are safe, healthy and secure during this COVID-19 pandemic.

Ira Smith Trustee & Receiver Inc. is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting.

licensed insolvency trustee vaughan

Call a Trustee Now!