Categories
Brandon Blog Post

Financial Reorganization Services vs. Small Business Bankruptcy in Ontario: Which Is Undeniably Right for Your Company?


I hope you, your team and your business are safe and well. If your company is under financial pressure, please know that this situation is not a personal failure. Many capable business owners face periods when cash flow, debt and creditor demands become difficult to manage. Seeking advice early is an act of responsible stewardship, not a cause for shame.

When a business is in financial trouble, the instinctive question is often, “Is this bankruptcy?” The more useful first question is, “Is this business viable so that it can have a successful financial reorganization?” At Ira Smith Trustee & Receiver Inc., we help owners examine both possibilities calmly and practically so they can make informed decisions before their options narrow.

Reorganization Key Takeaways

  • Informal reorganization may provide the fastest and least expensive solution, but it depends on creditor co-operation and does not provide a legal stay of proceedings.
  • A Division I Proposal in Ontario is a formal reorganization process under the Bankruptcy and Insolvency Act that can allow a viable corporation to continue operating while compromising eligible debts.
  • Corporate bankruptcy generally involves the sale or liquidation of company assets and normally brings the company’s operations to an end unless a purchaser acquires the business assets in order to carry on the business in a new corporation.
  • A corporation’s insolvency does not automatically eliminate the owner’s personal exposure. Personal guarantees and certain director liabilities must be reviewed separately.
  • Early advice from your accountant and a Licensed Insolvency Trustee can help preserve lifelines that may not be available later.

Reorganization Highlights

Is this bankruptcy, or is it a reorganization?

Insolvency means a company cannot meet its obligations as they become due, and/or its assets are not sufficient to pay its liabilities. Insolvency does not always mean that the underlying business has no future.

A company may have loyal customers, valuable employees, a sound product and a realistic path to profitability, but still be overwhelmed by accumulated debt, rising costs or a temporary cash-flow crisis. In that situation, financial reorganization services may help separate a viable operating business from an unsustainable debt structure.

Bankruptcy is different. It is generally a liquidation process. The company’s assets are placed under the control of a Licensed Insolvency Trustee, realized or sold, and the proceeds are distributed to creditors according to the statutory priority rules.

The earlier we assess the facts, the more clearly we can distinguish a temporary cash-flow problem from a business model that is no longer viable. That distinction matters because reorganization works best when there is still something worth preserving.

What are financial reorganization services?

Financial reorganization services can include informal negotiations, formal proceedings or a combination of both. The right approach depends on the company’s cash flow, assets, operations, creditor relationships and future prospects.

Informal reorganization

An informal reorganization does not involve filing a formal proceeding under insolvency legislation. The company may negotiate directly, or with the assistance of an advisor, with:

  • Lenders and other secured creditors;
  • The Canada Revenue Agency;
  • Landlords;
  • Suppliers;
  • Employees and other stakeholders.

Possible arrangements may include revised payment terms, interest relief, a standstill, a rent deferral, a new financing arrangement or a negotiated settlement.

This is often the fastest and least expensive path. However, it depends on creditor goodwill. A creditor can generally change its position, continue collection activity or enforce its rights if no binding formal protection is in place. There is also no automatic legal stay of proceedings.

Informal reorganization can be an effective lifeline when creditors believe the company has a credible plan and the business communicates openly. It becomes much harder when negotiations begin only after enforcement has started.

Professionals reviewing a cash-flow forecast and strategic recovery plan for a financial reorganization

Reorganization: What does a Division I Proposal actually do for my company?

A Division I Proposal, also called a commercial proposal in Ontario, is a formal offer to creditors under Part III, Division I of the Bankruptcy and Insolvency Act. A corporation files the proposal through a Licensed Insolvency Trustee.

The proposal may offer creditors a portion of what they are owed, paid over time or through another arrangement. If it is accepted by creditors and approved by the court, the company may continue operating while completing the proposal.

A company may begin by filing a Notice of Intention to Make a Proposal. In general terms, this provides a period of protection while the company develops its proposal. A proposal can also be filed directly in appropriate circumstances.

The filing triggers an automatic stay of proceedings under the BIA. The relevant stay provisions include section 69(1) for a Notice of Intention and section 69.1 for a filed proposal. Subject to statutory exceptions and court orders, the stay generally halts collection activity, garnishments and most enforcement action against the company and its property.

Creditors vote on the proposal. In general, acceptance requires:

  • A majority in number of the voting unsecured creditors; and
  • At least two-thirds in value of the voting unsecured creditors.

Creditor approval is not the only step. The court must also approve, or sanction, the proposal before it becomes binding under the legislation.

A Division I Proposal can be a powerful option, but it is not risk-free. If creditors reject the proposal, the court fails to approve it, or if the proposal fails to proceed as required, usually because the company fails to perform the entire accepted and approved proposal, the company is generally deemed bankrupt. That is why the proposal must be based on realistic cash-flow forecasts rather than optimism alone.

The Companies’ Creditors Arrangement Act, or CCAA, is another reorganization tool. It is used for larger and more complex insolvencies, involving at least $5 million in debt, and is typically outside the reach of a small business. A Division I Proposal is more commonly considered for small and mid-sized Ontario corporations.

When is small business bankruptcy rather than financial reorganization in Ontario the more realistic answer?

Small business bankruptcy in Ontario may be appropriate when the underlying business is not viable, and there is no realistic path to stable operations.

In a corporate bankruptcy, the Licensed Insolvency Trustee takes control of the company’s assets, subject to the rights of secured creditors and other legal considerations. Assets may be sold individually or as an operating business. The proceeds are distributed to creditors according to the statutory priority order.

The company normally ceases operating as its own business. However, a purchaser may acquire some or all of the assets and continue the business in a new ownership structure. The outcome depends on the assets, contracts, employees, financing, market and available buyers.

Bankruptcy does not mean that the owner automatically loses everything personally. A corporation is a separate legal entity. However, the owner’s personal exposure is a separate and important question that must be examined carefully.

Organised financial documents and a practical reorganization checklist

Comparison of the main paths

DimensionInformal reorganizationBIA Division I ProposalCorporate bankruptcy
What it isDirect negotiations or an advisor-supported arrangement with creditors and stakeholders.A formal offer to compromise corporate debts under the Bankruptcy and Insolvency Act.A formal liquidation and realization process administered under the BIA.
Legal protectionNo automatic stay of proceedings. Protection depends on negotiated agreements.An automatic stay generally applies under the BIA, subject to statutory exceptions and court orders.A stay may apply in the bankruptcy, but the trustee administers the estate and realizes assets for creditors.
Who approves or controls it?The company and participating creditors negotiate the terms.Creditors vote, and court approval is required. A Licensed Insolvency Trustee administers the process.A Licensed Insolvency Trustee administers the estate, subject to the BIA and creditor and court processes where applicable.
What happens to the business?The company continues if negotiations succeed and cash flow can be stabilised.The company may continue operating while completing the approved proposal.The company generally stops operating unless assets or the business are sold to a purchaser.
Typical cost and timelineUsually the least expensive and fastest, but highly dependent on creditor co-operation.More formal, with professional, filing and court-related costs; timing varies with complexity.Costs and timing depend on the assets, claims, investigations, litigation and distribution process.
Who it generally suitsA business with a credible plan and creditors willing to co-operate.A viable or potentially viable business needing legal protection and a formal compromise of debt.A business with no realistic reorganization path or where liquidation is the most responsible outcome.

CCAA proceedings are a separate, court-supervised reorganization regime generally used for larger companies that meet the statutory requirements, commonly including at least $5 million in debt.

Reorganization: Could I be personally liable for company debt?

This is one of the most important questions for an owner. Corporate insolvency and personal insolvency are not the same thing.

Personal exposure may arise from:

  • Personal guarantees given to banks, equipment financiers, landlords or suppliers;
  • Joint debts or co-signed obligations;
  • Director liability for certain unremitted source deductions under the Income Tax Act;
  • Director liability for certain amounts owing under the Excise Tax Act, including some HST obligations;
  • Other statutory obligations that may survive the corporation’s insolvency.

A corporate reorganization may therefore need to be coordinated with a personal solution for the owner. Depending on the facts, that could include a consumer proposal or another personal insolvency option.

Do not assume that incorporating your business eliminates every personal risk. Do not assume that a personal guarantee will disappear because the company files. We recommend reviewing guarantees, tax accounts, shareholder loans and personal assets with your accountant and a Licensed Insolvency Trustee before taking further steps.

Which option may fit my business?

Reorganization may fit better when:

  • The business has positive cash flow or a credible plan to reach it;
  • Key customers, contracts and revenue remain intact;
  • The core products or services are commercially sound and sought after;
  • Employees and management can continue operating the business;
  • Creditors are likely to support a reasonable plan.

Bankruptcy may be the more honest answer when:

  • The company is losing money with no credible turnaround plan;
  • The owner is funding ongoing losses with personal savings or credit;
  • Major customers or revenue sources have disappeared;
  • The business cannot maintain payroll, taxes or essential suppliers;
  • Creditor support is unrealistic.

The goal is not to preserve a business at any cost. The goal is to make a responsible decision that protects value, reduces uncertainty and gives the owner a path forward based on business viability.

Reorganization: What warning signs should I not ignore?

Please seek advice promptly if your company:

  • Cannot pay payroll or source deductions on time;
  • Uses HST collected from customers and employee source deductions to fund operations;
  • Has maxed-out revolving credit or a lender that has stopped advancing funds;
  • Has received a CRA demand, requirement to pay or garnishment;
  • Is being moved to cash-on-delivery terms or cut off by suppliers;
  • Faces a landlord’s threat of distress or lease termination;
  • Is losing key employees because of financial uncertainty; or
  • Has received demands under personal guarantees.

These signs do not automatically determine the answer. They do indicate that time is running out and the company’s options should be assessed now rather than later.

Reorganization: What should I do if my company may be in trouble?

I suggest the following general steps:

  1. Gather the records. Assemble current financial statements, bank statements, tax filings, aged receivables and payables, loan documents, leases, payroll records and creditor correspondence.
  2. Understand the real numbers. Prepare a realistic short-term cash-flow forecast. Identify what must be paid to keep the business operating and what debts are already overdue.
  3. Speak with your accountant. Your accountant can help assess profitability, tax reporting, working capital and whether the operating business is fundamentally viable.
  4. Consult a Licensed Insolvency Trustee early. A trustee can explain informal reorganization, a Division I Proposal, bankruptcy and the potential consequences of each.
  5. Review personal exposure. Identify every personal guarantee, shareholder loan, tax obligation and jointly held asset.
  6. Be cautious with personal funds. Before using personal savings, credit cards or a second mortgage to fund ongoing losses, obtain advice about whether that money is likely to change the outcome.

Taking these steps does not commit you to bankruptcy. It gives you information. Information restores control.

Reorganization Frequently Asked Questions (FAQ)

Can I file bankruptcy and keep my business?

A corporation can technically continue operating in limited circumstances, but corporate bankruptcy generally involves the trustee realizing on company assets and the business ceasing as the existing legal entity. A purchaser may acquire the assets and continue operations. The answer depends on the company’s structure, assets, contracts and creditor rights.

Does bankruptcy personally wipe out my guarantees?

No. A company’s bankruptcy does not automatically eliminate personal guarantees. The lender or supplier may pursue the guarantor according to the guarantee and applicable law. Personal exposure should be reviewed separately.

What happens if creditors reject my proposal?

A rejected Division I Proposal results in the company being deemed bankrupt. There are important procedural and legal details, so the proposal process should be planned carefully with a Licensed Insolvency Trustee.

Can I reorganize CRA debt?

Some CRA debts may be addressed through a formal proposal, but tax debts can involve trust claims, director liability and other statutory issues. Do not assume that all CRA debt is treated the same way. Obtain advice based on the company’s tax accounts and payment history.

Will my employees be paid?

Payroll obligations should be assessed immediately. In a bankruptcy or receivership, eligible employees may have claims under the Wage Earner Protection Program, subject to its rules and limits. A trustee can explain the process, but owners should not delay addressing unpaid wages or source deductions.

How long does the process take?

There is no single answer. Informal negotiations may move quickly, while a Division I Proposal involves preparation, creditor voting and court approval. Bankruptcy timelines depend on the company’s assets, claims, investigations, litigation and distribution issues.

Should I wait until a creditor sues?

Usually, no. Waiting may reduce the available options and make an orderly reorganization more difficult. Early advice is not an admission of defeat. It is good business judgment.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future, call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

————————––

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

IRA SMITH is President of Ira Smith Trustee & Receiver Inc., a CPA CA and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors and professionals. Ira and Brandon Smith stay current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.Business owner and financial advisor reviewing reorganization options in a Toronto office

#FinancialReorganization #Reorganization #SmallBusinessBankruptcy #OntarioBusiness #CorporateReorganization #DivisionIProposal #BusinessDebt #InsolvencyAdvice #GTAEntrepreneurs #StartingOverStartingNow

Categories
Brandon Blog Post

Toronto Business Closures Are Surging: Why BMO’s Per-Capita Insolvency Argument Misses the Bigger Picture

Two professionals reviewing a cash flow forecast and strategic restructuring plan for a Toronto business

I hope you, your family, and your Toronto business are safe and managing as well as possible in a difficult economic environment. If you are a GTA business owner watching sales weaken, costs rise, or creditors become more persistent, you are not alone, and asking for help early is not a sign of failure. It is a practical step towards regaining control.

The latest Toronto business and Canadian insolvency data tell a complicated story. New businesses continue to open, but an unusually large number are also closing. At the same time, formal insolvency filings are rising, while many households and businesses may be managing distress outside the formal insolvency system.

Toronto Business: Key Takeaways

  • The Toronto Census Metropolitan Area (CMA) recorded approximately 10,870 Toronto business openings in April 2026, the highest April level in at least 11 years.
  • Toronto also recorded approximately 10,720 Toronto business closures, the second-highest April total on record, behind only April 2020.
  • Active businesses fell to 187,700 in April 2026, marking a seventh consecutive monthly decline and the lowest level since June 2022.
  • Canada recorded 13,254 insolvency filings in June 2026, up 11.5% year over year and more than double the June 2020 volume.
  • BMO Capital Markets’ per-capita analysis provides one useful perspective. Still, it does not capture who has access to credit, who is filing, or how many businesses and households are struggling without filing.
  • For Toronto business owners, early advice from an accountant and a Licensed Insolvency Trustee can preserve more restructuring options.

Toronto Business: Highlights

Toronto Business: What is Toronto business data telling us?

The Toronto CMA is experiencing both entrepreneurial activity and business contraction at the same time.

According to Better Dwelling’s August 5, 2026 report, approximately 10,870 businesses opened in April 2026. That was the most openings recorded for an April in at least 11 years.

That might sound encouraging. It is.

However, approximately 10,720 businesses also closed during the month. This was the second-highest April closure total on record, surpassed only by April 2020, when pandemic lockdowns disrupted the economy.

The result is a high-churn environment. Toronto business churn means businesses are opening and closing at an unusually rapid rate. Churn can reflect innovation and opportunity, but it can also indicate that owners are entering markets without enough financial cushion to withstand weaker demand, higher operating costs, tighter credit, or delayed customer payments.

The number of active businesses in the Toronto CMA fell to 187,700 in April 2026. This was the seventh consecutive monthly decline. The active Toronto business count was down approximately 0.9% year over year and at its lowest level since June 2022, nearly a four-year low.

This is the real-world business story behind the headline. Toronto is not simply seeing fewer businesses. It is seeing significant movement in both directions, while the total base of active businesses continues to shrink.

Business professionals reviewing positive and negative cash flow Toronto business projections during a restructuring discussion

Toronto Business: Why is BMO’s per-capita argument incomplete?

BMO Capital Markets senior economist Robert Kavcic has offered a perspective that deserves to be understood fairly.

As reported by Better Dwelling on August 13, 2026, Mr. Kavcic acknowledged that consumer insolvencies were near the highest level since the 2009 recession. His argument was that, after adjusting for Canada’s population growth, insolvencies had “basically just normalized back to pre-pandemic conditions.”

He concluded that “the real story is that there is really no story.”

A per-capita measure, a calculation that divides a total by the size of the population, can be useful. It can help compare conditions across different time periods when the population has changed. BMO is right that raw totals do not tell the entire story.

The difficulty is that population growth does not necessarily equal comparable growth in credit exposure.

Better Dwelling reported that approximately 40% of Canada’s population growth over the past five years came from non-permanent residents, including temporary workers and international students. These groups typically have more limited access to unsecured credit, the type of credit that does not require collateral.

That matters because consumer insolvency filers often have an established borrowing history. According to the Office of the Superintendent of Bankruptcy data cited by Better Dwelling, 57% of consumer insolvency filers in 2024 had a bank loan, with a median value of approximately $20,000. In addition, one in five filers had filed before.

This profile does not necessarily match the typical non-permanent resident. Therefore, using total population as the denominator may dilute the apparent rate of insolvency without accurately measuring the financial stress among established borrowers.

The broader lesson is not that per-capita statistics are useless. The lesson is that they must be qualified. A business owner, lender, policymaker, or household needs to know not only how many people live in Canada, but also who is borrowing, who is falling behind, and who is taking formal action.

The June 2026 figures remain significant. Canada recorded 13,254 insolvency filings, an 11.5% increase from June 2025 and more than double the June 2020 volume. Only June 2009 recorded more filings. The trailing 12-month total reached approximately 150,505 filings, up 5.3% year over year.

Those numbers do not prove that every household or Toronto business is in crisis. They do show that financial distress is material and deserves more than a single reassuring ratio.

Toronto Business: What kinds of financial distress are being missed?

Raw insolvency counts and per-capita ratios can both understate the pressure facing the economy because they capture only part of the problem.

There are at least three different forms of financial distress:

Form of distressWhat it isHow it appears in the dataWhy it matters to a business owner
Formal insolvency filingA bankruptcy or proposal filed under Canada’s insolvency legislation. A proposal is a formal arrangement intended to compromise or restructure debts.It appears in official insolvency statistics reported by the OSB.It may provide legal protection and a structured path forward, but waiting too long can reduce available options.
Silent business closureA business stops operating, winds down, or does not renew operations without making a formal insolvency filing.It appears in business-opening and business-closure data, but not necessarily in insolvency statistics.Suppliers, employees, landlords, and customers may still be affected. The owner may also remain personally exposed through guarantees or other obligations.
Household debt stressA household manages financial pressure through arrears, refinancing, payment deferrals, or high-interest credit without filing an insolvency proceeding.It may appear indirectly in arrears or credit data and may not appear in formal insolvency counts for months or years.Household stress can reduce consumer spending, delay business payments, and weaken the customer base on which a business depends.

Insolvency is also a lagging indicator. That means a formal filing often occurs after months or years of financial deterioration. Before filing, a business may have used savings, borrowed from family, increased credit-card balances, refinanced assets, delayed tax remittances, or negotiated informal payment arrangements.

By the time the filing appears in the statistics, the underlying financial pressure may already be much more severe.

This is why a Toronto business owner should not wait for a formal insolvency number, or a missed payment, to decide whether advice is necessary. Early advice is about information, not commitment.

Toronto Business: What does this mean for GTA business owners?

For a GTA business owner, the important question is not whether the economy is technically “normal” on a per-capita basis. The important questions are more immediate:

  • Are sales sufficient to cover operating costs?
  • Are customers paying more slowly?
  • Are supplier terms becoming stricter?
  • Are tax arrears accumulating?
  • Are loan renewals or refinancing becoming more difficult?
  • Have you used personal credit to support the company?
  • Have you signed personal guarantees for corporate borrowing or leases?
  • Is the Toronto business profitable before debt payments, but unable to meet its total obligations?

A company can be viable, meaning it has a fundamentally workable business model, while still being financially unsound because of accumulated debt, temporary cash-flow disruption, or an unsustainable repayment schedule.

That distinction is important. A viable company may have restructuring options that disappear if the owner waits until assets are seized, key employees leave, or critical suppliers stop extending credit.

A corporate restructuring plan may involve negotiating with creditors, changing payment terms, selling non-core assets, reducing expenses, or using a formal proposal. A commercial proposal, sometimes called a Division I Proposal, is a legal process that can allow a financially troubled but viable company to compromise debts and continue operating, subject to the required approvals.

The right solution depends on the company’s structure, assets, liabilities, cash flow, tax position, employees, secured lenders, and personal guarantees. There is no universal answer.

Businessperson protected by a shield representing a Toronto business director protection and early insolvency advice

Toronto Business: What should a worried business owner do now?

If you are concerned about your GTA or City of Toronto business, I recommend taking these steps:

  1. Prepare a current cash-flow forecast.
    List expected sales receipts, payroll, rent, taxes, loan payments, supplier obligations, and other essential expenses. A cash-flow forecast is a practical estimate of money coming in and going out over a defined period.
  2. Speak with your accountant early.
    Your accountant can help identify profitability problems, tax obligations, cash-flow gaps, and whether the business can realistically recover under its current structure.
  3. Consult a Licensed Insolvency Trustee.
    A Licensed Insolvency Trustee can explain formal options, including a proposal or bankruptcy, and help distinguish between corporate obligations and your personal exposure.
  4. Review personal guarantees and director liability.
    If you personally guaranteed a corporate loan, lease, credit facility, or supplier account, the corporation’s financial problems may affect you directly. Certain tax and payroll obligations can also create potential director exposure. Obtain professional advice before transferring assets, repaying selected creditors, or closing the company.
  5. Assess whether the core business is viable.
    Ask whether the company can generate positive operating cash flow after a realistic restructuring of its debt and costs. If the answer is yes, a restructuring proposal may be a lifeline. If not, an orderly wind-down may be more appropriate.
  6. Act before the crisis becomes irreversible.
    Early action does not mean you have decided to file. It means you are preserving information, time, credibility, and options.

We know the tension placed upon Toronto business owners and their families. It is not your hope, commitment, or personal worth that these statistics measure. Financial distress is a business problem that requires a business solution.

For additional context, our discussion of commercial proposals and corporate restructuring explains how a formal proposal may help a viable company continue operations. Our article on personal bankruptcy also discusses why a corporation and its owner must be assessed separately.

Toronto Business: Frequently Asked Questions (FAQ)

Are Toronto’s business closures the same as business insolvencies?

No. A business closure means an operation has stopped or ceased to be active. It does not necessarily mean the business filed a bankruptcy or proposal. Some businesses close quietly, while others may restructure informally or continue under a different ownership or operating model.

Does BMO’s per-capita analysis have value?

Yes. Per-capita analysis can help account for population changes. The concern is relying on it alone. It may not reflect differences in credit access, borrowing behaviour, business exposure, or the number of people experiencing stress without filing.

Why are insolvency filings considered a lagging indicator?

A formal insolvency filing often follows a long period of missed payments, borrowing, refinancing, arrears, or attempts to negotiate with creditors. The filing is usually evidence that earlier coping strategies have stopped working.

Should I wait until my business misses a payment before seeking advice?

No. Early advice is generally more useful because it allows you to understand your options before creditors take enforcement action, suppliers withdraw terms, or essential assets become unavailable. A consultation does not obligate you to file.

Can a business owner be personally responsible for corporate debt?

Possibly. Personal guarantees, the legal structure of the business, and certain tax or payroll obligations can create personal exposure. This is fact-specific, so speak with your accountant and a Licensed Insolvency Trustee before making major financial decisions.

Is a proposal the same as bankruptcy?

No. A proposal is a formal arrangement to compromise or restructure debts, while bankruptcy is a separate legal process. Whether a proposal is appropriate depends on the company’s viability, assets, liabilities, cash flow, and creditor situation.

The message for Toronto and the GTA is balanced but clear: new businesses are still being created, but active businesses are declining, closures are elevated, and formal insolvency filings are rising. That is a story worth paying attention to, not to create panic, but to encourage timely, informed action.

Source note: Statistics and quotations in this article are based on the two Better Dwelling reports published on August 5, 2026, and August 13, 2026. The underlying Statistics Canada and Office of the Superintendent of Bankruptcy data are attributed as reported by Better Dwelling. BMO’s position is attributed to BMO Capital Markets senior economist Robert Kavcic.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future; call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Ira Smith is President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Ira stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.Image of a worried business owner as Toronto business closures are increasing in 2026

#TorontoBusiness #GTABusiness #BusinessClosures #CorporateRestructuring #BusinessInsolvency #DebtRestructuring #CommercialProposal #DivisionIProposal #BusinessBankruptcy #FinancialDistress #LicensedInsolvencyTrustee #StartingOverStartingNow
Categories
Brandon Blog Post

PROTECTION FROM CREDITORS: WHAT TORONTO ENTREPRENEURS ABSOLUTELY NEED TO KNOW BEFORE IT’S TOO LATE

protection from creditors

Protection From Creditors: The Real Problem Toronto Business Owners Face

I need to start by reminding you that I am a licensed insolvency trustee, not a lawyer. This Brandon’s Blog on protection from creditors is not about how to hide your assets from creditors when financial trouble looms. It is also not legal advice. For that, you need to see your lawyer.

Rather, this is for informational purposes about the realization that pretty much every Toronto entrepreneur risks losing their assets to business debt. This Brandon’s Blog is meant to provide practical steps to gain protection from creditors for your personal assets while resolving business financial troubles from a licensed insolvency trustee with many success stories.

Meet Carlos. He started a food truck in Toronto selling arepas in 2022. By 2024, food costs doubled, and he took out a $100,000 loan using his North York home and his food truck as collateral. Now, he’s three months behind on payments. The bank wants his business AND his house.

Carlos isn’t alone. Nearly 3 out of 4 small business owners in Ontario lose sleep over mixed personal and business debts. With consumer debt hitting record highs and business bankruptcies up almost 18% in Ontario last year, keeping your business problems from becoming problems for your personal financial affairs is crucial.

Protection From Creditors: Why Your Business Debt Becomes Personal -Three Common Traps

Trap #1: Using Personal Credit Cards for Business

“I just needed to buy supplies quickly.”

The hard truth: When you swipe your card for business expenses, you’re personally responsible for that debt. 68% of new businesses use personal credit.

Trap #2: Signing Personal Guarantees

“The bank said I had to sign my name to get the loan.”

The hard truth: Almost all Canadian small business loans (92%) require personal guarantees. Last year, a Mississauga contractor lost his heavily mortgaged home because he guaranteed a $350,000 equipment loan he could not repay.

Trap #3: Mixing Money

“I don’t have time to keep everything separate.”

The hard truth: When your personal and business money flows through the same accounts, you’re asking for trouble. Almost 9 out of 10 bankruptcy cases get more complicated and expensive because of mixed finances.

Toronto entrepreneur standing at crossroads between business debt storm and financial protection path with CN Tower skyline in background
protection from creditors

Four Ways Toronto Entrepreneurs Can Get Protection From Creditors

Option 1: Creditor Protection Through Business Restructuring (For Incorporated Companies)

This uses Canada’s Companies’ Creditors Arrangement Act (CCAA) or the restructuring provisions of the Bankruptcy and Insolvency Act (BIA) to:

  • Keep your business running while you work out new payment terms
  • Shield your personal stuff from business creditors

Real example: A restaurant group kept six locations open through this process last year.

Good points:

  • Protects your personal assets
  • Keeps your employees working

Not-so-good points:

  • CCAA only works for bigger companies ($5+ million in debt) and is court-driven and therefore very expensive.
  • For companies that owe less than $5 million, the restructuring provisions of the BIA are available and is a less costly process than the CCAA. Technically, nothing is stopping a debtor that qualifies under the CCAA to use the BIA instead.
  • Takes 6-18 months to complete

Option 2: Consumer Proposal (Perfect for Many Small Unincorporated Business Owners)

A consumer proposal can legally:

  • Cut up to 80% off your total debt
  • Let you keep your assets if completed successfully
  • Stop collection calls, lawsuits, and bank account seizures immediately

Real example: A Scarborough sole proprietor cut $150,000 in mixed debts down to $30,000 through a consumer proposal.

How it works:

  1. Meet with a licensed insolvency trustee (free first meeting)
  2. File paperwork under the BIA
  3. Make one affordable monthly payment for up to 5 years that your unsecured creditors have agreed to either at a meeting of creditors (if required) or having agreed in advance, and therefore no meeting is necessary

Option 3: Strategic Personal Bankruptcy

Sometimes starting fresh makes the most sense, especially when:

  • Your business can’t be saved
  • You need immediate relief from overwhelming debt
  • You don’t own any or many assets

What Can You Keep? Ontario’s 2025 Bankruptcy Exemptions

When dealing with serious debt problems, many Toronto entrepreneurs worry they’ll lose everything. Good news – Ontario law lets you keep certain things even during bankruptcy or proposals.

Your Home

You can keep your home if: You have $10,783 or less in equity (that’s your home’s value minus what you still owe on your mortgage).

You might lose your home if: Your equity is higher than $10,783. In that case, the trustee might sell your home to pay creditors, but you’d still get the first $10,783.

What Else Can You Keep?

Household Items: Furniture, appliances, dishes, and food up to $14,180

Work Tools: Equipment you need for your job or business up to $14,450

Your Car: One vehicle worth up to $6,600

Clothes: All your necessary clothing, no dollar limit

Retirement Savings: Most RRSPs are protected (except money you put in during the 12 months before filing)

Life Insurance: Many policies are protected from creditors

For Farmers: Special protections for livestock, equipment, and tools up to $31,379

Real-World Example: I will call this woman Samira. When Samira, a Toronto web designer, filed for bankruptcy, she kept her car valued at $5,000, her computer equipment (valued at $8,000), and her condo (because her equity was only $9,000). This gave her the fresh start she needed without losing essential assets. She still had lots of secured debt, which is another issue, but she did not have to give up those assets.

Note: These exemption numbers can change yearly with regulations. Always check with a licensed insolvency trustee for the most current exemption amounts.

Option 4: Debt Consolidation (The 2025 Method)

Many Toronto entrepreneurs are now:

  • Working with alternative lenders to the big banks, such as credit unions
  • If of sufficient value, using business equipment as collateral instead of their homes

Warning: Be careful with this option. Nearly half of consolidated debts end up in default within two years.

Get Protection From Creditors Today: The One-Hour Checklist

Step 1: Separate Your Money (This Afternoon)

  • Open business accounts at a different bank from your personal accounts
  • Stop using credit cards that you cannot afford to pay off monthly for business expenses
  • Set up automatic transfers for your business’s “salary”

Step 2: Document Everything (This Evening)

  • Take photos of all business equipment
  • Make copies of all loan agreements
  • Create a list of who you owe money to (both business and personal)

Step 3: Get Help (This Week)

  • Contact the Ontario Business Legal Clinic for free advice
  • Visit Toronto’s Office of Financial Empowerment
  • Calculate your business debt ratio (Total Debts ÷ Total Assets)

    Toronto entrepreneur standing at crossroads between business debt storm and financial protection path with CN Tower skyline in background
    protection from creditors

Protection From Creditors: Real Toronto Success Stories

The Tech Startup That Bounced Back

Problem: A Markham software company owed $2.3 million to creditors, both secured creditors and unsecured creditors. The founder had used his $900,000 condo as loan collateral.

Solution: Through a court-supervised restructuring, the company cut their debt by 60%. Today, they’re profitable and employ 12 people.

The Food Truck Owner Who Saved His Home

Problem: Carlos (from our opening story) had $230,000 in combined debt. The CRA was about to garnish his income.

Solution: Through a consumer proposal, he reduced his unsecured debt to $30,000 and will be paying it off over five years ($500 monthly). He can pay that along with his bank loan payments and therefore keep his home and his food truck.

Protection From Creditors: Three Things To Do Before Friday

  1. Download our free worksheet: “Toronto Debt Relief Worksheet“. Fill out all the requested information. Warning: it asks for a lot of information because it aims to look at every important aspect of your financial situation.
  2. Review carefully all the information you filled in: If you were honest and completed the whole worksheet, the issues you need to work on will jump right off the page at you.
  3. Book your free consultation: If the worksheet highlights issues you don’t know what the best solution would be to fix them, contact us for a no-cost consultation.

    Toronto entrepreneur standing at crossroads between business debt storm and financial protection path with CN Tower skyline in background
    protection from creditors

Top Questions Toronto Business Owners Ask About Debt Protection From Creditors

Q: Why should I worry about separating business and personal debt?

A: Almost 60% of Toronto entrepreneurs end up losing personal assets because of business debts. With business bankruptcies up 17.8% in Ontario last year and consumer debt hitting record highs, keeping these separate isn’t just smart—it’s survival. Many of my clients couldn’t sleep at night until they protected their personal finances from business troubles.

Q: Can the CRA take my house for business taxes?

A: Yes, if:

  • Your business is incorporated but has unpaid employee source deductions or outstanding HST. That is a personal liability of all directors, notwithstanding your business is run by a separate legal entity.
  • You operate your business as a proprietorship or partnership. In those situations, your business debts are also your personal debts.

We helped several Toronto families keep their homes from CRA collection last year alone. The CRA has stronger collection powers than most creditors and can place liens on your property for unpaid taxes.

Q: My business is incorporated—doesn’t that protect me automatically?

A: This is a dangerous myth I see hurting Toronto entrepreneurs. Incorporation only protects you if you never personally guaranteed any loans or credit cards. The truth? About 92% of Canadian small business loans require personal guarantees, which means your home and savings are still at risk.

Q: How fast can I stop collection actions?

A: As soon as you do an insolvency filing. It is something called the “stay of proceedings” that kicks in. This legally stops all collection efforts immediately, usually within 5-7 days of your first meeting with a licensed insolvency trustee. Last month, we helped a restaurant owner stop garnishment actions that were just 48 hours away from freezing her accounts.

Q: How do I know if I’ve fallen into the “mixed finances trap”?

A: Check these warning signs: Do you use the same credit card for groceries and business supplies? Is your business operating account at the same bank as your personal chequing account? Have you ever transferred money between personal and business accounts without proper documentation? If you answered yes to any of these, you need to take action immediately.

Q: What’s better for a small business owner—bankruptcy or consumer proposal?

A: For most Toronto entrepreneurs I work with, either a consumer proposal or a BIA restructuring proposal (for those who owe more than the consumer proposal limit of creditors in excess of $250,000, not including any debts secured against your home) offers a better alternative. You can keep your assets (including your home), reduce unsecured debts by up to 75%, and rebuild your credit faster. Bankruptcy should be your last resort, though it works well when you need immediate relief and don’t have significant assets to protect.

Q: How do I know which debts are dischargeable in bankruptcy?

A: Most business and personal unsecured debts can be eliminated through bankruptcy, including credit cards, lines of credit, and supplier accounts. However, some debts survive bankruptcy, including student loans less than seven years since you stopped being a student, court fines, and child support. I recommend bringing a complete list of your debts to your consultation for a personalized assessment.

Protection From Creditors Conclusion

I hope you’ve found this protection from creditors Brandon’s Blog, helpful. There is a lot of uncertainty in business today. The time to properly plan to gain asset protection from creditors is when you begin your business. Once your business is in financial trouble, it is too late.

If you or someone you know is struggling with too much debt, remember that the financial restructuring process, while complex, offers viable solutions with the right guidance. As a licensed insolvency trustee serving the Greater Toronto Area, I help entrepreneurs understand their options and find a path forward during financial challenges.

At the Ira Smith Team, we understand the financial and emotional components of debt struggles. We’ve seen how traditional approaches often fall short in today’s economic environment, so we focus on modern debt relief options that can help you avoid bankruptcy while still achieving financial freedom.

The stress of financial challenges can be overwhelming. We take the time to understand your unique situation and develop customized strategies that address both your financial needs and emotional well-being. There’s no “one-size-fits-all” approach here—your financial solution should be as unique as the challenges you’re facing.

If any of this sounds familiar and you’re serious about finding a solution, reach out to the Ira Smith Trustee & Receiver Inc. team today for a free consultation. We’re committed to helping you or your company get back on the road to healthy, stress-free operations and recover from financial difficulties. Starting Over, Starting Now.

The information provided in this blog is intended for educational purposes only. It is not intended to constitute legal, financial, or professional advice. Readers are encouraged to seek professional advice regarding their specific situations. The content should not be relied upon as a substitute for professional guidance or consultation. The author, Ira Smith Trustee & Receiver Inc., and any contributors do not assume any liability for any loss or damage.

Toronto entrepreneur standing at crossroads between business debt storm and financial protection path with CN Tower skyline in background
protection from creditors
Categories
Brandon Blog Post

COMPANIES ARE DECLARING BANKRUPTCIES EVEN THOUGH THEY RECEIVED THE CANADA EMERGENCY BUSINESS ACCOUNT: LOANS, REPAYMENTS, AND BANKRUPTCIES

Declaring Bankruptcies Introduction

Picture this: April 2020, and your small Canadian business survive on thin margins. Suddenly, a global pandemic hits, lockdowns ensue, and your revenue disappears overnight. Then, a lifeline appears in a twist of fate: the Canada Emergency Business Account (CEBA).

On February 18, 2025, Statistics Canada released an economic paper written by Sean Clarke, Jasper Hui, and Dave Krochmalnek, “Borrowing, repayments and bankruptcies by industry: Results from the Canada Emergency Business Account program”. This post explores how this initiative influenced many businesses’ trajectories – some soared, while others crumbled under new pressures as the pandemic’s aftermath unfolded forcing many declaring bankruptcies.

declaring bankruptcies

Declaring Bankruptcies: Understanding CEBA – Lifesaver or Temporary Relief?

The CEBA was introduced to help small and medium enterprises (SMEs) during the COVID-19 pandemic. But what exactly does this mean for you? CEBA aimed to provide interest-free loans to businesses struggling to survive the economic fallout. With a staggering $49 billion allocated to various sectors, it was a significant lifeline for many. But was it enough?

Overview of CEBA and Its Objectives

CEBA was designed to assist businesses in covering essential operational costs. The loans, which could reach up to $60,000 per Canadian business, were intended to keep the doors open during the toughest times. Think of it as a safety net. But how effective was this net in catching those who fell?

  • Total funding: $49 billion
  • Maximum loan per business: $60,000

Total Funding

Maximum Loan per Canadian Business

$49 billion

$60,000

The Definition of Client-Facing Industries

Client-facing industries are sectors that directly interact with customers. This includes accommodations, food services, and transportation. These industries were hit hard during the pandemic. Imagine a restaurant forced to close its doors. The impact was immediate and severe. Output in these sectors dropped between 30% and 60% during the initial lockdowns. How could they survive without support?

In contrast, industries like construction and retail rebounded more quickly. Construction even saw a boom due to increased demand for single-family homes. This disparity raises questions about the fairness of the support provided. Why did some sectors receive more funding than others?

How CEBA Disbursement Shaped Business Survival

CEBA’s disbursement was crucial for many businesses. As one expert noted,

“CEBA was a crucial bridge for many businesses caught in the pandemic’s storm.”

This statement encapsulates the essence of the program. It was a bridge, but was it strong enough to support all who relied on it?

While many businesses managed to repay their loans, a significant portion—about 18.8%—remained outstanding by the forgiveness deadline. This translates to approximately $9.2 billion still owed. Instead of being forgiven, these loans transitioned into three-year term loans at a 5% interest rate. For businesses already struggling, this new burden was daunting.

Some sectors faced even higher rates of outstanding loans. For instance, the transportation and warehousing industry had 30.7% of loans outstanding. Accommodation and food services were not far behind at 21.9%. Even construction, which seemed to recover quickly, had 20.1% of loans still outstanding. This paints a picture of a complex recovery landscape.

It’s essential to evaluate the overall effectiveness of CEBA. Did it truly save businesses, or just delay the inevitable? The number of companies declaring bankruptcies decreased initially, likely due to government interventions like CEBA. However, as time passed and economic conditions changed, bankruptcy filings surged. By early 2024, over 1,200 businesses declared bankruptcy, many of which had received CEBA loans.

This situation raises critical questions. Did CEBA merely mask deeper vulnerabilities in the economy? The interconnected nature of these economic factors is evident. While CEBA provided immediate relief, the long-term implications remain uncertain.

CEBA was a significant initiative at supporting SMEs during an unprecedented crisis. However, the varying impacts across industries and the subsequent challenges faced by many businesses highlight the complexities of economic support measures. As we continue to navigate these waters, understanding the full scope of CEBA’s impact is essential for future economic resilience.

Declaring Bankruptcies: Diving into the Discrepancies – Who Benefited Most?

When we look at the impact of the CEBA program, it’s clear that not all industries were created equal. Some sectors thrived while others struggled. Why is that? Let’s dive into the numbers and uncover the surprising disparities in funding allocations and the reasons behind them.

Comparison of Industry Sectors

First, let’s consider the sectors that fared differently during the pandemic. The client services industry, which includes accommodations, food services, and transportation, saw a staggering drop of 30% to 60% in output during the initial lockdowns. That’s a significant hit! On the other hand, industries like manufacturing bounced back much quicker. In fact, construction even experienced a boom due to increased demand for single-family homes.

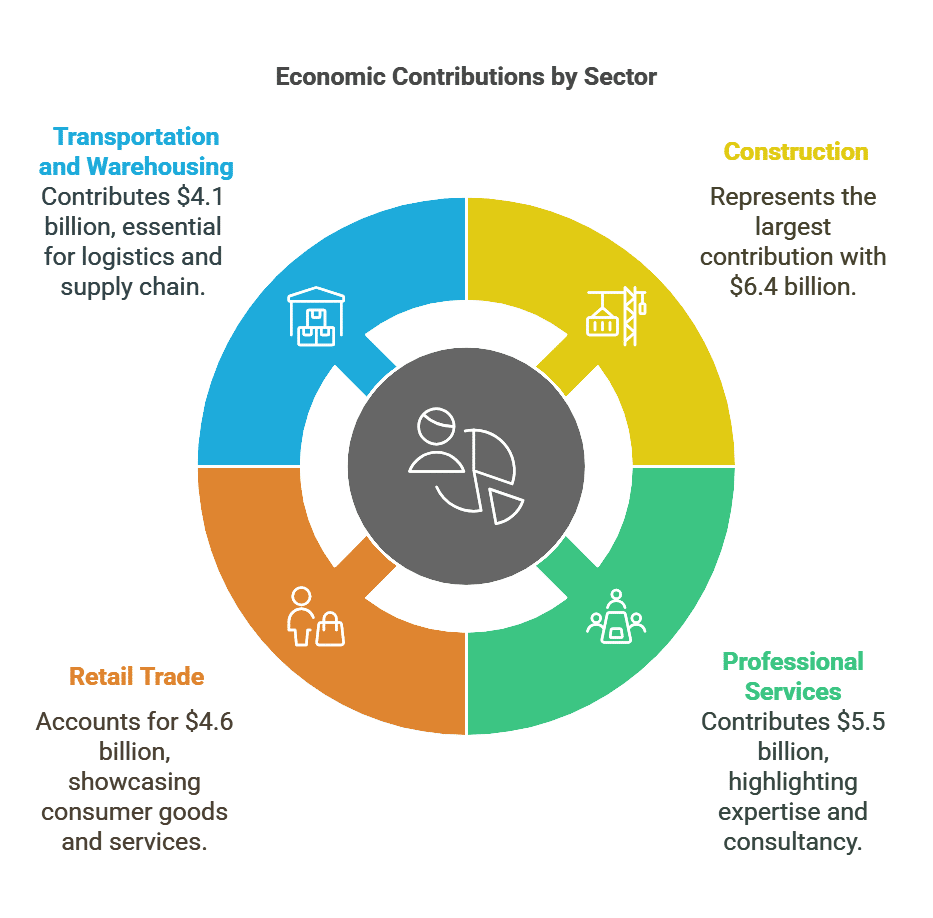
It’s fascinating to see how these differences played out in funding. Construction received a whopping $6.4 billion from CEBA, which is about 13% of the total funding. This is surprising, especially considering that construction was recovering faster than many other sectors. Why did they get such a large slice of the pie?

Surprising Funding Allocations

To put things into perspective, let’s look at the funding allocations:

  • Construction: $6.4 billion
  • Professional Services: $5.5 billion
  • Retail Trade: $4.6 billion
  • Transportation and Warehousing: $4.1 billion

declaring bankruptcies

These numbers reveal a clear trend. The sheer number of businesses in the construction sector likely allowed more companies to qualify for CEBA loans. But what about the service industries? They faced deeper impacts and yet received less funding overall.

Reasons Behind the Disparities

So, what explains these disparities in loan distribution? One reason is the nature of the businesses themselves. The hardest-hit sectors also had a higher rate of outstanding loans. For instance, the transportation and warehousing industry had 30.7% of loans still outstanding, while accommodation and food services faced a rate of 21.9%. Even construction had 20.1% of its loans outstanding, indicating that not all businesses in recovering sectors were out of the woods.

As you can see, the funding landscape is complex. While some sectors received substantial support, others were left to fend for themselves. This raises important questions about the effectiveness of such programs. Are they truly helping those in need, or are they simply delaying the inevitable for some businesses?

As we explore the outcomes of the CEBA program, it’s crucial to consider the broader implications. The differences in funding allocations and the varying impacts on different sectors highlight the need for tailored economic support strategies. Understanding these nuances can help us navigate future economic challenges more effectively.

declaring bankruptcies

The CEBA was a lifeline for many businesses during the pandemic. It provided essential financial support when the world was in turmoil. But what happened after the loan forgiveness deadline? This question is crucial as we analyze the trends in corporate bankruptcies that emerged in the wake of CEBA.

Initial Effects of the Loan Forgiveness Deadline

When the loan forgiveness deadline approached, many businesses faced a harsh reality. A staggering 18.8% of CEBA loans remained outstanding. This meant that instead of being forgiven, these loans transformed into three-year term loans with a 5% interest rate. For businesses already struggling, this was like adding fuel to a fire.

Imagine running a small restaurant. You relied on that loan to keep your doors open during lockdowns. Now, you have to pay it back with interest. How do you manage that when customers are still hesitant to return? This scenario played out in many sectors, particularly those that were client-facing.

Rising Bankruptcy Rates in Various Sectors

As we moved into early 2024, bankruptcy rates surged. In the first quarter alone, there were 12,000 bankruptcies. Alarmingly, 39% of these corporate bankruptcies involved businesses that had taken CEBA loans. The ticking time bomb of conversion to debt ultimately revealed serious vulnerabilities in many businesses once they started incurring CEBA debt service costs.

  • Accommodation and food services were hit hardest, accounting for 20.3% of bankruptcies among CEBA participants.
  • Retail trade and construction followed, with 13.7% and 11.8% respectively.

These numbers paint a grim picture. The pandemic had already decimated many businesses. Now, the added burden of repaying loans pushed some over the edge. It’s like trying to swim with weights tied to your ankles. You can only struggle for so long before you sink.

Impact of Economic Conditions Post-Pandemic

The economic landscape post-pandemic was anything but stable. Rising interest rates and escalating input costs created a perfect storm. Businesses that had managed to survive the initial lockdowns now faced new challenges. The combination of these factors led to a significant increase in declaring bankruptcies.

In fact, the report indicates that while bankruptcy rates initially decreased during the pandemic, they reversed course in mid-2022. This shift coincided with the looming deadline for loan forgiveness. As businesses scrambled to adapt, many found themselves unable to cope with the financial strain.

Consider the transportation and warehousing industry. They had a staggering 30.7% of loans outstanding. Even sectors that seemed to recover quickly, like construction, faced challenges. About 20.1% of construction businesses still had loans outstanding. This suggests that the recovery was not uniform across industries.

As you reflect on these trends, it’s clear that the CEBA program had both positive and negative effects. While it provided immediate relief, the long-term consequences are now unfolding. Businesses are left grappling with financial obligations, and the economic recovery remains fragile.

In summary, the consequences of CEBA are complex. The initial relief provided by the loans has transitioned into a burden for many. As bankruptcy rates rise, it’s essential to understand the interconnected nature of these economic factors. The pandemic has left its mark, and the path to recovery is fraught with challenges.

The Ripple Effect: Beyond Declaring Bankruptcies

The economic landscape has changed dramatically in recent years. The COVID-19 pandemic shook businesses to their core. Many faced unprecedented challenges. But what happens when the dust settles? What are the long-term implications of the support provided, like the Canada Emergency Business Account (CEBA)? Let’s dive into the ripple effects of these financial lifelines.

1. Long-Term Economic Implications

When we think about the CEBA program, we often focus on immediate relief. However, the long-term effects are just as crucial. Businesses received interest-free loans, but at what cost? The loans were meant to provide a safety net, yet they may have created a larger debt burden. This can stifle growth in the long run.

  • Debt Burden: Many businesses now face significant repayments. This can limit their ability to invest in growth.
  • Market Dynamics: With rising debt, companies may become more risk-averse, avoiding new ventures.
  • Sector Disparities: Some industries, like construction, received more funding but recovered faster. Others, like food services, are still struggling.

It’s essential to ask: Are we setting businesses up for success or failure? The answer may lie in how these loans are managed in the future.

2. The Impact of Rising Inflation and Interest Rates

Inflation and interest rates are like the weather—unpredictable and often harsh. As inflation rises, so do costs for businesses. This can squeeze profit margins. Additionally, interest rates have been climbing, making it harder for companies to manage their debt.

  • Cost of Goods: Rising prices can lead to increased operational costs.
  • Loan Repayments: Higher interest rates mean higher repayments. This can be a heavy burden putting pressuer on being able to repay both secured creditors and unsecured creditors.
  • Consumer Behaviour: As costs rise, consumers may cut back on spending, affecting sales.

As one expert put it,

“It’s a complex interplay of factors—like juggling flaming swords while riding a unicycle through a storm.”

This analogy perfectly captures the precarious balance businesses must maintain.

3. Vulnerability in Businesses Pre- and Post-Pandemic

The pandemic revealed vulnerabilities in many businesses. Some were already struggling before COVID-19 hit. The support from CEBA helped, but it also masked deeper issues. Now, as the economy shifts, these vulnerabilities are resurfacing.

  • Pre-Pandemic Weakness: Many businesses were operating on thin margins. The pandemic exposed these weaknesses.
  • Post-Pandemic Recovery: As the economy reopens, businesses must adapt. Those that don’t may face business bankruptcy.
  • CEBA Recipients vs. Non-Recipients: Interestingly, CEBA participants had a bankruptcy rate of 0.7% compared to 1.3% for non-participants. This shows that support can make a difference, but it’s not a cure-all.

As we analyze the data, it’s clear that while CEBA provided immediate relief, it also created a new set of challenges. Businesses are now navigating a complex landscape of debt, rising costs, and changing consumer behavior.

The ripple effects of the CEBA program are profound. The long-term economic implications, the impact of rising inflation and interest rates, and the vulnerabilities exposed during the pandemic all intertwine. As businesses continue to adapt, they must find ways to manage their debts while also investing in future growth. The journey ahead is uncertain, but understanding these factors will be crucial for navigating the new economic reality.

declaring bankruptcies

A Cautious Path Forward: Lessons Learned

The COVID-19 pandemic has left many businesses grappling with vulnerabilities. As we reflect on the lessons learned from the CEBA program, it’s essential to consider how we can move forward. What can we take away from this experience? How can we ensure that future financial programs are more effective and sustainable?

Takeaways for Future Financial Programs

First and foremost, we need to recognize that not all businesses are created equal. Different industries have different needs. The CEBA program provided crucial support, but it also highlighted the disparities in recovery among sectors. For instance, while construction thrived, accommodations and food services struggled. This brings us to a vital takeaway: future financial programs must be tailored to the specific needs of industries.

  • Understand industry-specific needs: Programs should be designed with a clear understanding of the unique challenges faced by different sectors.
  • Flexibility is key: Financial support should be adaptable, allowing businesses to pivot as conditions change.
  • Monitor outcomes: Regular assessments can help identify which programs are working and which are not.

The Importance of Targeted Support

Targeted support is crucial for effective recovery. The CEBA program showed us that blanket solutions often miss the mark. For example, many businesses in the transportation and warehousing sector faced significant challenges, with 30.7% of loans remaining outstanding. This indicates that a one-size-fits-all approach can lead to unintended consequences.

As we move forward, we must ask ourselves: How can we provide support that truly meets the needs of businesses? The answer lies in targeted interventions. By focusing on specific sectors, we can ensure that resources are allocated where they are needed most.

Looking Ahead to Sustainable Recovery Strategies

Looking ahead, sustainability in economic recovery is paramount. As the quote goes,

“Sustainability in economic recovery depends on a nuanced understanding of industry needs and vulnerabilities.”

This means that recovery strategies must be holistic and context-sensitive. We need to consider not just immediate relief but also long-term resilience.

Some strategies to consider include:

  • Investing in training and development: Equip businesses with the skills they need to adapt to changing markets.
  • Encouraging innovation: Support businesses in developing new products or services that meet emerging demands.
  • Building partnerships: Foster collaboration between businesses, government, and community organizations to create a supportive ecosystem.

The lessons learned from the CEBA experience are invaluable. We must embrace a more nuanced approach to financial support, one that recognizes the unique challenges faced by different industries. By focusing on targeted support and sustainable recovery strategies, we can help businesses navigate the complexities of the post-pandemic landscape. The road ahead may be cautious, but with the right strategies in place, we can foster resilience and ensure a brighter future for all. Remember, the key to successful recovery lies in understanding the diverse needs of our economy and responding accordingly.

declaring bankruptcies

Declaring Bankruptcies: CEBA FAQ

What was the purpose of the Canada Emergency Business Account (CEBA) program?

The CEBA program was introduced by the Government of Canada on March 27, 2020, to provide interest-free loans to eligible small and medium-sized businesses to help cover their operating costs during the COVID-19 pandemic. The loans were up to $60,000, with a portion (up to one-third) forgivable if repaid by a set deadline. The aim was to help businesses maintain solvency and operations during a period of significant economic disruption.

Which industries received the most CEBA funding and why?

The construction industry received the most CEBA funding, totaling over $6.4 billion (13.1% of total loan disbursements), largely distributed among residential building construction businesses, building equipment, and building finishing contractors. This was partly due to the high number of legal entities within the construction sector. Client-facing service industries such as professional, scientific, and technical services; retail trade; transportation and warehousing; and accommodation and food services also received significant funding because they were among the most severely impacted by public health restrictions and disruptions to traditional business operations.

What were the repayment terms and deadlines for CEBA loans?

The original repayment deadline to qualify for partial loan forgiveness was December 31, 2022. This was extended to December 31, 2023, and then again to January 18, 2024. If the loan was not repaid by this final deadline, the outstanding balance was converted into a three-year term loan, subject to an interest rate of 5% per annum, with the loan forgiveness option no longer available. The final repayment date for these term loans is December 31, 2026.

Which industries had the highest rates of outstanding CEBA loans after the repayment deadline?

Industries that were hardest hit by pandemic-related lockdowns and experienced slower recoveries tended to have the highest rates of outstanding CEBA loans. These included transportation and warehousing (30.7% outstanding), administrative and support, waste management and remediation services (22.7% outstanding), accommodation and food services (21.9% outstanding), and construction (20.1% outstanding). These sectors often faced prolonged disruptions and financial pressures, making it difficult to repay loans by the deadline.

How did bankruptcies among CEBA borrowers change during and after the pandemic?

Business bankruptcies initially declined in the first half of the pandemic but began to accelerate in mid-2022, reaching a high in the first quarter of 2024, coinciding with rising interest rates, elevated input costs, and the end of the CEBA program forgiveness period. The proportion of bankrupt businesses that had taken out CEBA loans increased from 39% in the first quarter of 2021 to 70% in the first quarter of 2024. After this acute period, bankruptcies dropped sharply over the remainder of 2024.

Which industries saw the most bankruptcies among businesses that had received CEBA loans?

The accommodation and food services industry accounted for the largest share of bankruptcies among CEBA borrowers (20.3%), with full-service restaurants and limited-service eating places being particularly affected. Retail trade (13.7%) and construction (11.8%) also had significant proportions of CEBA borrowers declaring bankruptcy.

What were the overall bankruptcy rates for CEBA borrowers compared to non-borrowers?

Of the 898,271 CEBA borrowers, 6,343 (0.7%) eventually declared bankruptcy by the end of September 2024. In contrast, the overall bankruptcy rate for all businesses between the second quarter of 2020 and the third quarter of 2024 was 0.9%, and for businesses that did not take CEBA loans, the bankruptcy rate was 1.3%. This suggests that while many CEBA borrowers did face bankruptcy, their overall rate was lower than that of businesses that did not receive CEBA support.

What were the expectations of businesses regarding their ability to repay outstanding CEBA loans?

According to Statistics Canada’s Survey on Business Conditions, nearly two-thirds (65.6%) of businesses with outstanding CEBA loans anticipated having the liquidity or access to credit to repay the loan by December 31, 2026. However, approximately one-fifth (19.9%) were uncertain about their ability to repay, and 14.5% did not expect to have the necessary liquidity or credit access, indicating that repayment challenges persisted for a significant minority of businesses.

Declaring Bankruptcies Conclusion

The CEBA provided crucial financial lifelines to many businesses during the COVID-19 pandemic. However, disparities in funding distribution and subsequent declaring bankruptcies highlight a complex economic landscape that continues to evolve. Don’t let the storm of bankruptcy catch you off guard. Take proactive measures now, and you may find yourself on the path to recovery.

I hope you enjoyed this declaring bankruptcies Brandon’s Blog. Do you or your company have too much debt? Are you or your company in need of financial restructuring? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or someone with too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern debt relief options to get you out of your debt troubles while avoiding the bankruptcy process. We can get you debt relief freedom using processes that are a bankruptcy alternative.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a plan, we know that we can help you.

We know that people facing financial problems need a realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team.

That is why we can develop a restructuring process as unique as the financial problems and pain you are facing as your alternative to bankruptcy. If any of this sounds familiar to you and you are serious about finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation. We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The information provided in this Brandon’s Blog is intended for educational purposes only. It is not intended to constitute legal, financial, or professional advice. Readers are encouraged to seek professional advice regarding their specific situations. The content of this Brandon’s Blog should not be relied upon as a substitute for professional guidance or consultation. The author, Ira Smith Trustee & Receiver Inc. as well as any contributors to this Brandon’s Blog, do not assume any liability for any loss or damage.

declaring bankruptcies
Categories
Brandon Blog Post

BANKRUPTCY OF THE COMPANY: OUR ENTREPRENEUR’S COMPREHENSIVE GUIDE TO REBUILDING AFTER BANKRUPTCY

Bankruptcy of the Company: Introduction

Imagine being at the helm of a thriving business, only to watch the bankruptcy of the company. As an insolvency professional, a Canadian licensed insolvency trustee (formerly called a trustee in bankruptcy), I have witnessed the rollercoaster of emotions that come with financial failure, often paired with the entrepreneur’s sense of guilt and loss that can feel insurmountable.

Recovering from the bankruptcy of the company is challenging but possible. By understanding the impacts, assessing finances, creating a strong recovery plan, and rebuilding credit and reputation, business owners can rise again with resilience and prepare for future growth.

This is not the end. It’s a transformative stage that opens doors to rethinking, reconstructing, and revitalizing your future. Let’s explore the roadmap to recovery together, filled with actionable advice and insightful anecdotes.

Bankruptcy of the Company: Understanding Business Bankruptcy

Canadian law offers two primary types of bankruptcy for addressing the insolvent company corporate bankruptcy process:

Liquidation

Liquidation is the process of closing a business and selling its assets to generate funds. The proceeds from these sales are then used to pay off creditors. While it represents the conclusion of the company’s operations, understanding this process can help you navigate the winding down of a business effectively.

Reorganization

This initiative aims to thoughtfully reshape the company’s financial and operational structures, ensuring its ongoing success and stability. Reorganization presents a valuable opportunity for businesses facing financial difficulties, allowing them to effectively address and potentially overcome their economic challenges. Typically, this process is carried out through a commercial proposal under the Bankruptcy and Insolvency Act. For larger corporations with debts of at least $5 million, reorganization can take place under the Companies’ Creditors Arrangement Act.

Let’s take a closer look at each of these options to better understand how they can help.

Liquidation under bankruptcy of the company

Liquidation is the process of winding up a company that can no longer meet its financial obligations. It follows a structured corporate bankruptcy process outlined in the BIA, which bears similarities to Chapter 7 of the US Bankruptcy Code. Corporate bankruptcy is also called commercial bankruptcy.

Here’s a step-by-step breakdown of liquidation:

  • The decision to file:
  • The board of directors makes the difficult decision to file for bankruptcy and appoint a person to sign the official bankruptcy documents.
  • Assignment in Bankruptcy: A director, or the sole director, signs the required bankruptcy documents to make the company’s assignment into bankruptcy.
  • Appointment of the Licensed Insolvency Trustee: An insolvency trustee is appointed to oversee the process.
  • Asset Transfer: All corporate assets are transferred to the Licensed Insolvency Trustee, which then manages and sells them.
  • Distribution to Creditors: Proceeds from asset sales, after the cost of the corp bankruptcy proceedings, are distributed to creditors based on a predetermined legal priority.
  • Secured creditors, such as lenders with liens on company assets, generally have priority over unsecured creditors.
  • The company ceases to operate: Once assets are distributed, although the bankrupt corporation is not legally dissolved, it no longer operates.

Depending on whether the company is federally or provincially incorporated, eventually, the appropriate government authority will cancel the company’s charter due to the bankruptcy of the company.

Liquidation can be a complex process, but it offers a clear and organized approach to closing a company that is experiencing significant financial challenges. This process ensures that assets are distributed fairly among creditors, helping to bring some resolution to a difficult situation. If you find yourself in this position, rest assured that there are steps in place to manage the process as smoothly as possible.

“The closure of a business doesn’t just impact balance sheets, it impacts lives.”

A picture of a jigsaw puzzle with some pieces missing and a picture of a businessman over the puzzle to reporesent the bankruptcy of his company and his putting the pieces back together to start over.
bankruptcy of the company

Reasons for Bankruptcy of the Company

Financial Challenges

  • Cash Flow Management: Many companies struggle to manage their cash flow effectively, leading to a buildup of debt and ultimately, the bankruptcy of the company. This can be due to a variety of factors, including poor budgeting, delayed payments from customers, or over-reliance on credit.
  • High Debt Levels: Companies that take on too much debt can quickly become overwhelmed by their financial obligations. This can be particularly true for companies that have taken on debt to finance expansion or acquisitions.
  • Inefficient Use of Assets: Companies that fail to optimize their use of assets, such as inventory or equipment, can struggle to generate sufficient revenue to meet their financial obligations.
  • Poor Financial Planning: Companies that fail to plan for the future or make poor financial decisions can quickly find themselves in a difficult financial situation.

Operational Issues

  • Inefficient Operations: Companies that fail to streamline their operations or make inefficient use of resources can struggle to remain competitive and profitable.
  • Lack of Scalability: Companies that may not be fully attuned to shifts in the market or industry can find it difficult to scale their operations effectively. By staying adaptable and responsive to changes, businesses can better meet growing demand and seize new growth opportunities.
  • Poor Management: Companies that are poorly managed or lack effective leadership can struggle to make sound business decisions and ultimately, may force the bankruptcy of the company.
  • Failure to Innovate: Companies that fail to innovate or adapt to changes in the market can quickly become obsolete and struggle to remain competitive.

External Factors

  • Economic Downturn: Companies that operate in industries that are heavily reliant on consumer spending or are sensitive to economic fluctuations can be particularly vulnerable to bankruptcy during economic downturns.
  • Regulatory Changes: Companies facing evolving regulations or laws may find it challenging to adapt. However, with the right strategies and support, they can navigate these changes effectively and avoid potential difficulties. It’s important to stay informed and seek assistance to thrive in a dynamic regulatory environment.
  • Competition: Companies that operate in highly competitive industries can struggle to remain profitable and may force the bankruptcy of the company if they are unable to differentiate themselves or compete effectively.
  • Natural Disasters: Companies that are affected by natural disasters, such as hurricanes or wildfires, can struggle to recover and may ultimately be forced into bankruptcy.

Understanding the Ripple Effects of Bankruptcy

The bankruptcy of the company can turn your business life upside down. But understanding its effects can help you navigate this rough terrain. What are the immediate and long-term consequences?

Understanding The Immediate Effects on Your Credit Score

It’s important to know that your business’s credit score is separate from your credit score. The company is considered a distinct legal entity, meaning that, generally, its financial activities do not directly impact your credit score. However, as an entrepreneur, if you’ve personally guaranteed any bank loans or lines of credit for your business, this could affect you personally. If the company is unable to repay those loans, the bank will look to you to cover any outstanding amounts.

Additionally, as a director of the company, you hold responsibility for any unremitted employee source deductions and unremitted HST owed to the Canada Revenue Agency. Being aware of these obligations can help you manage your financial responsibilities more effectively and protect your credit standing. If you have questions or need further clarification, don’t hesitate to reach out for assistance.

So although the bankruptcy of the company does not directly affect your personal credit score, depending on what your financial position is now and how it is affected by the bankruptcy of the company, it could very well have a negative impact on your credit score.

The bankruptcy of the company gets reported to the two Canadian credit bureaus, TransUnion and Equifax. Depending on how your financial situation is affected by the bankruptcy of the company, your credit score may then suffer. It usually suffers in two ways:

  • Loss of borrowing capacity: You might find it challenging to get credit lines or loans.
  • Higher interest rates: If you do get offers, they may come with steep rates.

Loss of Trust Among Stakeholders

Trust is hard to regain once lost. After filing for corporate bankruptcy, if you wish to start up a new business, suppliers may hesitate to extend credit, leaving you in a bind. Customers might question your reliability, and partnerships can falter.

Legal Limitations Post-Bankruptcy

Additionally, there are legal limitations that follow the bankruptcy of the company. If you are applying for a job or credit for a new business, there could be a question to answer like “Have you ever been a director of a company that filed for bankruptcy”. Your answer could include restrictions on the types of businesses you can operate or positions you can hold.

Understanding these ripple effects is crucial. As financial advisor Jamie Carter wisely said,

“Bankruptcy can be a valuable lesson if you are willing to learn from it and adapt.”

Remember, the impacts extend beyond finances to reputational damage and legal constraints. You can emerge stronger if you take the time to understand these dynamics.

A picture of a jigsaw puzzle with some pieces missing and a picture of a businessman over the puzzle to reporesent the bankruptcy of his company and his putting the pieces back together to start over.
bankruptcy of the company

Reflecting on Financial Health Post-Bankruptcy

Understanding Your Financial Landscape

Recovering from the bankruptcy of the company can feel overwhelming. But remember, it all starts with understanding your financial situation. You can’t chart a path forward if you don’t know where you stand. So, how do you begin?

1. Gather Your Financial Documents

  • Start by collecting all of your financial statements and paperwork.
  • Make sure to include documents that reflect your current cash flow, outstanding debts, and assets.
  • Having this information organized will give you a clear understanding of your current financial position, making it easier to assess your situation effectively.

2. Create a List of Assets and Debts

Take the time to write down what you own and what you owe. Having a clear picture of your financial reality is crucial.

  • Total Debts: $200,000
  • Remaining Assets: $50,000

This exercise can feel daunting. But it’s necessary for redefining your reality. Consider this: how can you build a new foundation without understanding the ground underneath? Remember that you may have given personal guarantees to a lender to the company.

3. Set Realistic Financial Goals

Having a goal gives you direction. Break your recovery journey into achievable steps:

  1. Short-term goals: Focus on income generation, budget management and expense reduction.
  2. Long-term goals: Aim for debt reduction and credit score improvement.

Your goals should be tangible and reflect your new financial reality. It’s about letting clarity drive your recovery.

Using Financial Statements as a Roadmap

Your financial statements will serve as a roadmap throughout your recovery journey. They provide essential guidance when making decisions. For example, if you see a consistent cash flow issue, it might be time to revisit your business strategy.

Visualizing Your Financial Position

Understanding your debts versus assets is vital. The chart below visualizes your financial health:

Financial Element

Amount ($)

Total Debts

$200,000

Remaining Assets

$50,000

Preparation involves a meticulous assessment of your financial landscape. It’s about clarity, honesty, and setting yourself up for real change.

Crafting a Proactive Recovery Blueprint

Recovery is not merely about surviving; it’s about thriving. You can turn challenges into opportunities with the right proactive plan. Let’s break down some essential steps.

1. Establishing a Comprehensive Budget

Creating a detailed budget is crucial. It serves as your roadmap. Think of it as a financial GPS that helps guide your decisions.

  • Forecasting Cash Flows: This allows you to anticipate income and expenses. By understanding your cash flow, you can eliminate any surprises. Wouldn’t it be great to know your financial future better?
  • Identifying Fixed and Variable Costs: Understanding the difference between fixed and variable costs is essential for effective planning. Fixed costs, such as rent and salaries, remain constant regardless of production levels, while variable costs fluctuate based on your business activity.
  • By recognizing these distinctions, you can make more informed decisions and enhance your financial strategy.

2. Exploring Cost-Cutting Avenues

The goal here is to reduce costs without sacrificing quality. It’s a delicate balance.

  • Assess your needs and look for ways to get better deals.
  • Cut unnecessary expenditures.

How much could you save by embracing smarter practices?

3. Implementing Financial Management Systems

Robust financial management systems help ensure future stability. They make monitoring and adjusting your budget easier. They are available to everyone at a reasonable cost.

  • Adopt accounting software: This can automate processes and save time.
  • Conduct regular financial reviews: Staying updated allows for timely adjustments.

“Failing to prepare is preparing to fail.” – John C. Maxwell

These strategies don’t guarantee instant success, but they set a solid foundation for recovery. It’s about making informed decisions today to secure a better tomorrow.

A picture of a jigsaw puzzle with some pieces missing and a picture of a businessman over the puzzle to reporesent the bankruptcy of his company and his putting the pieces back together to start over.
bankruptcy of the company

Rebuilding Business Credit: It’s a Marathon, Not a Sprint

Getting into a new business requires building your business credit and access to financing after hardship is a journey. It’s a marathon, not a sprint. Why rush? Quick fixes can lead to long-term pain. Instead, focus on long-term strategies. Patience is your best friend here.

1. Opening New Credit Lines Responsibly

Start slow. Open new credit lines when you can manage them. This is your stepping stone. Think of it like planting seeds. You need to nurture them to grow. Responsible borrowing can improve your credit utilization ratio. This, in turn, boosts your credit score.

  • Choose accounts that report to credit bureaus.
  • Start with secured credit cards or smaller loans.

2. Using Secured Credit Cards

Secured credit cards are excellent tools for growth. They require a deposit, but they report your payments to credit bureaus. This means you’re building a positive credit history, one payment at a time. It’s about creating a solid foundation for your credit profile.

3. The Importance of Timely Payments

Let’s take a moment to discuss the significance of making payments on time. Your financial reputation is important, and timely payments play a crucial role in demonstrating your responsibility and stability. Think of it as essential for maintaining a healthy credit score – just like breathing is for your well-being.

If you happen to miss a payment, it can negatively impact your score, so it’s important to stay consistent. By prioritizing timely payments, you’re setting yourself up for financial success!

“Rebuilding credit will require discipline and strategy but can lead to an empowered financial future if handled well.”

4. Learning from Others

Many businesses have successfully navigated this path. Their stories are inspiring. They show that it’s possible to come back stronger. Embrace the lessons from those who have rebuilt their credit. Their experiences can guide you.

Remember, this isn’t just about fixing credit. It’s about creating a healthier future for your business. Stay focused on these long-term strategies to ensure lasting impact and success.

Repairing Your Company’s Image: The Reputation Rehabilitation

Repairing Trust through Transparent Communication

After a reputation setback, you might wonder how to regain trust. The answer lies in transparent communication. Regularly update your stakeholders about your journey. Share not just successes but also hurdles. This honesty shows integrity.

Consider this: Wouldn’t it be easier to trust someone who is open about their difficulties? When your audience perceives you as authentic and genuine, it becomes much simpler to reconnect with them.

Leveraging Digital Platforms for Positive Narratives

In today’s connected world, digital platforms play a crucial role. Use social media and your company website to share uplifting stories. Highlight how you’re improving and what your team is excited about.

  • Share success stories from employees or customers.
  • Post updates on community involvement and corporate social responsibility initiatives.
  • Engage with your audience through polls or Q&A sessions.

“Your brand is a story unfolding across all customer touchpoints.” – Jonah Sachs

As this suggests, every interaction is an opportunity to shape your narrative.

Documenting Changes to Restore Confidence

Last but not least, it’s vital to document and showcase changes. This can be anything from new management practices to enhanced product quality. Displaying tangible improvements can effectively demonstrate your commitment to recovery.

Regular updates not only remind stakeholders of your progress but also instill confidence. Keep in mind, that restoring your reputation is a journey, not a sprint.

So, how ready are you to engage fully in your reputation rehabilitation? Embracing these strategies can set your business on the right path.

A picture of a jigsaw puzzle with some pieces missing and a picture of a businessman over the puzzle to reporesent the bankruptcy of his company and his putting the pieces back together to start over.
bankruptcy of the company

Innovating Your Way Back to Success: Growth Beyond Recovery

With a foundation grounded in recovery, you’re now in a position to think bigger. The journey ahead is about more than just bouncing back; it’s about redefining your business potential. Let’s explore some key strategies you can adopt.

1. Identifying New Markets and Opportunities for Diversification

After any setback, understanding where to pivot is essential. Ask yourself: Are there untapped markets waiting for your offerings? Consider the possibilities:

  • Geographic expansion: Could your product resonate in a different region?
  • New demographics: What about targeting younger or older audiences?
  • Product diversification: Have you considered exploring complementary products or services that could enhance your offerings? This could be a great way to provide more value to your customers!

2. Investing in Tech and Innovative Practices

In today’s fast-paced environment, standing still is not an option. Innovation is power. Investing in technology can provide you with a competitive edge. For instance:

  • Automation: Streamline processes to save time and costs.
  • Data analytics: Leverage data to make informed decisions.
  • Digital marketing: Boost your online presence to engage and attract new customers effectively.

3. Building Alliances and Partnerships

Alone, you might find challenges hard to overcome. But together? You can achieve new heights. Consider forming strategic alliances. It could mean collaborating with other businesses to:

  • Share resources, which can lower costs.
  • Access new audiences through shared marketing efforts.
  • Mutual growth leads to stronger foundations for both parties.

“In today’s interconnected world, collaboration is the new competition.”

The Importance of Innovation

Absolutely! It’s important to recognize that innovation goes beyond just technology – it’s fundamentally about our mindset. By adopting an innovative approach during recovery phases, we can create opportunities for sustainable growth. Embracing this perspective can truly make a difference!

As you explore these avenues for growth, keep a sharp focus on your core mission and values. This will reignite your passion and drive for business.

Measuring Progress and Celebrating Wins Along Your Journey

Recovery is a journey filled with small victories. To make your path clear and effective, you need to start by establishing Key Performance Indicators (KPIs). These are measurable values that demonstrate how effectively you’re achieving your recovery goals. Think of them as signposts that guide you along the way.

Establishing KPIs to Monitor Your Recovery Journey

Choose KPIs that resonate with your specific recovery objectives. Here are a few ideas:

  • Credit score improvements
  • Reduction in outstanding debts
  • Revenue growth
  • Customer retention rates

Why is it important to track these KPIs? Regular updates and adjustments to your recovery strategy are essential. When you notice patterns in your progress, you can adapt your plan accordingly. Are you hitting targets? Celebrate that achievement! Are numbers not improving? Analyze what might need to change.

Acknowledging Small Milestones

It’s crucial to acknowledge and celebrate small milestones. Each small win is a step forward. Taking a moment to recognize these successes not only boosts morale but also motivates you to keep pushing onward. Think about what you have accomplished—each step is proof of your progress.

Incorporating these practices—setting KPIs, adjusting strategies as necessary, and celebrating your successes—can transform your recovery journey. By implementing effective tracking and celebrating your achievements, you can maintain a positive outlook and remain committed to your goals.

“Documenting progress not only keeps you accountable but also energizes your journey forward.”

Remember, recovery from the bankruptcy of the company is not just about bouncing back. It’s about moving forward stronger and more resilient than before. Embrace the journey, celebrate each victory, and you’ll find the path to success becomes much clearer. Keep pushing your limits, and don’t shy away from recognizing the efforts that take you further along your journey.

A picture of a jigsaw puzzle with some pieces missing and a picture of a businessman over the puzzle to reporesent the bankruptcy of his company and his putting the pieces back together to start over.
bankruptcy of the company

Bankruptcy of the Company FAQ

1. What happens when my company goes bankrupt?

In Canada, the bankruptcy of the company can be taken down one of two main paths: liquidation and reorganization.

  • Liquidation involves closing the business, selling its assets, and using the proceeds to pay off creditors. It signifies the end of the company’s operations.
  • Reorganization, typically through a proposal under the Bankruptcy and Insolvency Act, aims to restructure the company’s finances and operations to enable its continued existence.

The specific process and outcome will depend on the chosen path and the company’s individual circumstances.

2. How does company bankruptcy affect my personal credit score?

Generally, the bankruptcy of the company doesn’t directly impact your personal credit score. Companies are considered separate legal entities. However, there are exceptions:

  • Personal Guarantees: If you personally guaranteed any of the company’s debts, you become liable for those debts if the company can’t pay. This can negatively affect your credit score.
  • Director Liabilities: As a director, you are responsible for unremitted employee source deductions and HST owed to the CRA. Failure to remit these could impact your creditworthiness.

While the bankruptcy of the company isn’t a direct hit, the resulting financial strain from personal guarantees or liabilities can indirectly affect your creditworthiness.

3. What are the immediate consequences of bankruptcy beyond finances?

The impact of the bankruptcy of the company extends beyond just the financial aspect. You might experience:

  • Loss of Trust: Stakeholders like suppliers, customers, and potential partners might hesitate to work with you due to the bankruptcy of the company.
  • Reputational Damage: The bankruptcy of the company becomes a public record, potentially affecting your future business prospects.
  • Legal Limitations: You might face restrictions on the types of businesses you can operate or positions you can hold.

These consequences highlight that bankruptcy’s impact can be far-reaching and affect your ability to rebuild.

4. How can I understand my financial situation after company bankruptcy?

Start by:

  1. Gathering Financial Documents: Collect all personal and business financial statements, including cash flow statements, debt records, and asset documentation.
  2. Listing Assets and Debts: Create a comprehensive list of what you own and what you owe, including any personal guarantees for company debts.
  3. Setting Realistic Goals: Define achievable short-term goals (income generation, budgeting) and long-term goals (debt reduction, credit score improvement).

This process helps you understand your current financial position and create a roadmap for recovery.

5. How do I rebuild business credit after bankruptcy?

Rebuilding business credit takes time and strategic effort. Focus on:

  1. Responsible New Credit Lines: Start small with secured credit cards or loans that report to credit bureaus, gradually building a positive credit history.
  2. Timely Payments: Consistently making payments on time demonstrates financial responsibility and is crucial for improving your credit score.
  3. Learning from Others: Seek advice and inspiration from other businesses that successfully rebuilt their credit after bankruptcy.

Remember, patience and responsible financial management are key to rebuilding business credit.

6. How can I repair my company’s reputation after bankruptcy?

Focus on:

  1. Transparent Communication: Openly communicate with stakeholders about the bankruptcy of the company, your recovery plan, and progress made. This honesty builds trust.
  2. Leveraging Digital Platforms: Utilize your website and social media to share positive stories, highlight improvements, and engage with your audience.
  3. Documenting Changes: Showcase tangible improvements in your operations, management practices, and product quality to demonstrate your commitment to recovery.

By actively managing the narrative and showcasing positive change, you can gradually rebuild trust and restore your company’s reputation.

7. What are some strategies for growth after recovering from bankruptcy?

Consider these strategies:

  1. Identifying New Markets: Explore untapped markets by expanding geographically, targeting new demographics, or diversifying your product/service offerings.
  2. Investing in Innovation: Embrace technology and innovative practices through automation, data analytics, and digital marketing to gain a competitive edge.
  3. Building Partnerships: Form strategic alliances with other businesses to share resources, access new audiences, and achieve mutual growth.

Growth after the bankruptcy of the company involves strategic planning and proactive efforts to explore new opportunities and redefine your business potential.

8. How do I measure my progress and stay motivated during recovery?

Utilize these methods:

  1. Establish KPIs: Define key performance indicators (KPIs) that align with your recovery goals, such as credit score improvement, debt reduction, revenue growth, etc.
  2. Track and Adjust: Regularly monitor your KPIs and adjust your recovery strategy as needed, celebrating successes and addressing areas requiring improvement.
  3. Acknowledge Milestones: Celebrate even small wins and acknowledge your progress to maintain motivation and a positive outlook throughout the recovery journey.

By actively tracking your progress and celebrating achievements, you can stay focused and committed to rebuilding your business stronger than before.

Bankruptcy of the Company: Conclusion

I hope you enjoyed this bankruptcy of the company Brandon’s Blog. Do you or your company have too much debt? Are you or your company in need of financial restructuring due to distressed real estate or other reasons? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or someone with too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding the bankruptcy process. We can get you debt relief freedom using processes that are a bankruptcy alternative.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a plan, we know that we can help you.

We know that people facing financial problems need a realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team.

That is why we can develop a restructuring process as unique as the financial problems and pain you are facing. If any of this sounds familiar to you and you are serious about finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation. We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The information provided in this Brandon’s Blog is intended for educational purposes only. It is not intended to constitute legal, financial, or professional advice. Readers are encouraged to seek professional advice regarding their specific situations. The content of this Brandon’s Blog should not be relied upon as a substitute for professional guidance or consultation. The author, Ira Smith Trustee & Receiver Inc. as well as any contributors to this Brandon’s Blog, do not assume any liability for any loss or damage resulting from reliance on the information provided herein.

A picture of a jigsaw puzzle with some pieces missing and a picture of a businessman over the puzzle to reporesent the bankruptcy of his company and his putting the pieces back together to start over.
bankruptcy of the company
Categories
Brandon Blog Post

NAVIGATING CORP BANKRUPTCY IN CANADA: OUR COMPREHENSIVE GUIDE FOR BUSINESS OWNERS

Corp Bankruptcy Introduction

Running a business can be tough. Sometimes, despite your best efforts, your company may face overwhelming financial difficulties. When business debts pile up and staying afloat seems impossible, it might be time to consider corp bankruptcy proceedings. This can be stressful and complex, but understanding your options is crucial for making the best decisions for your company and yourself.

This guide aims to demystify Canada’s different types of company insolvency proceedings. We’ll break down the intricacies of bankruptcy, Division I proposals, and receivership, providing clarity on their implications for debt resolution and your business’s future.

Understanding What Is Corp Bankruptcy

In Canada, corp bankruptcy, also known as commercial bankruptcy or business bankruptcy, is a legal process that allows the incorporated legal entity unable to pay their debts to seek relief by filing bankruptcy. It provides a framework for either liquidating the company and distributing assets to creditors or reorganizing the business to become financially stable again.

Corp bankruptcy is fundamentally different from personal bankruptcy, which pertains to individuals, including sole proprietorships and partnerships. While personal bankruptcy is designed to assist individuals in obtaining a fresh start by addressing their personal assets, corporate bankruptcy seeks to facilitate either an orderly dissolution of the company or its restructuring.

A businessman on a sinking ship in turbulent waters representing a corporation heading to bankruptcy with a helicopter above throwing a restructuring lifeline.
corp bankruptcy

Navigating this process necessitates specialized knowledge. A Licensed Insolvency Trustee, who is a federally licensed professional, plays an essential role in guiding you through the proceedings. They ensure compliance with the Bankruptcy and Insolvency Act (BIA) and other relevant regulations while effectively managing a variety of financial matters.

Types of Corp Bankruptcy Proceedings in Canada

Canadian law offers two primary avenues for addressing the corp bankruptcy process:

Liquidation

This involves closing down the business, selling its assets, and using the proceeds to pay creditors. It’s a final step, signifying the end of the company’s operations.

Reorganization

The objective of this initiative is to strategically restructure the company’s financial and operational frameworks, thereby ensuring its continued viability. Reorganization serves as a critical opportunity for businesses facing financial challenges, enabling them to navigate and potentially surmount their economic obstacles.

Let’s explore each type in greater detail.

Liquidation under Corp Bankruptcy

Liquidation is the process of winding up a company that can no longer meet its financial obligations. It follows a structured corporate bankruptcy process outlined in the BIA, which bears similarities to Chapter 7 of the US Bankruptcy Code.

Here’s a step-by-step breakdown of liquidation:

  • Decision to File:
  • The board of directors makes the difficult decision to file for bankruptcy
  • . Assignment in Bankruptcy: A director, or the sole director, signs the required bankruptcy documents to make the company’s assignment into bankruptcy
  • Appointment of the Licensed Insolvency Trustee: An insolvency trustee is appointed to oversee the process.
  • Asset Transfer: All company assets are transferred to the Licensed Insolvency Trustee, which then manages and sells them. Distribution to Creditors: Proceeds from asset sales, after the cost of the corp bankruptcy proceedings, are distributed to creditors based on a predetermined legal priority.
  • Secured creditors, such as lenders with liens on company assets, generally have priority over unsecured creditors.
  • The company ceases to operate: Once assets are distributed, although the bankrupt corporation is not legally dissolved, it no longer operates.

Depending on whether the company is federally or provincially incorporated, eventually, the appropriate government authority will cancel the company’s charter.

Liquidation can be a challenging process, but it provides a structured way to wind down a company facing insurmountable financial difficulties and allows for a fair distribution of assets to creditors.

“The closure of a business doesn’t just impact balance sheets, it impacts lives.”

Reorganization: A Path to Recovery

Reorganization, often known as “bankruptcy protection,” provides struggling but viable businesses an opportunity to restructure their debts and operations, helping them avoid shutting down completely.

In Canada, there are two main legal options for corporate reorganization:

  1. Companies’ Creditors Arrangement Act (CCAA): This federal law is designed for larger corporations with debts over $5 million. The CCAA process is supervised by the court to ensure fairness and transparency.
  2. Division I Proposal under the BIA: This option is geared towards smaller businesses that don’t meet the debt threshold required for the CCAA.

Both of these processes are similar to Chapter 11 reorganizations in the US Bankruptcy Code, offering a structured way for companies to get back on their feet.

The reorganization process generally follows these steps:

  1. Filing for Protection: The company initiates the bankruptcy process by filing under the CCAA with the court or the Bankruptcy and Insolvency Act (BIA) with the Office of the Superintendent of Bankruptcy. A Licensed Insolvency Trustee is assigned to oversee the process, acting as either the Monitor for CCAA cases or the Proposal Trustee for Division I Proposals under the BIA.
  2. Stay of Proceedings: Once the filing is done, the court grants a stay of proceedings. This means creditors are temporarily barred from starting or continuing any legal actions against the company while it works on its reorganization.
  3. Plan Development: The company then creates a plan of arrangement (for CCAA) or a proposal (for BIA) that details how it plans to restructure its debts and operations.
  4. Creditor Approval: The proposed plan is presented to the creditors, who must approve it. A two-thirds majority vote is needed for the plan to pass.
  5. Court Approval: Finally, the court reviews the plan and must give its approval before the company can move forward with the implementation. This step is especially important for filings under the CCAA.

“Understanding your options is essential for financial clarity and future success.”

Division I Proposals vs. Bankruptcy: Understanding Key Legislation and the Nuances

Although both Division I proposals and bankruptcy fall under the umbrella of corp bankruptcy proceedings, they offer distinct approaches to dealing with financial distress.

Here’s a closer look at the key differences:

Feature

Division I Proposal

Bankruptcy

Eligibility

Smaller corporations (debt typically below $5

Any insolvent

Any insolvent corporation

Court involvement

Less involved; primarily oversees the approval process

Potentially more involved in settling disputes

Flexibility

More flexible; allows for tailored debt restructuring plans

Less flexible; focuses on asset liquidation and distribution

Timeframe

Shorter timeframe for filing a plan

No specific timeframe

Outcome if rejected

Automatic bankruptcy

N/A

Cost

Can be more costly due to the need to restructure operations and negotiate with creditors

Cost depends on complexity and types of assets to be sold

A businessman on a sinking ship in turbulent waters representing a corporation heading to bankruptcy with a helicopter above throwing a restructuring lifeline.
corp bankruptcy

Choosing the right path depends on your company’s specific circumstances, the severity of its financial troubles, and the potential for recovery.

Receivership: When Secured Creditors Take Action

Receivership is a legal process that empowers a receiver, which in Canada can only be a licensed insolvency practitioner, to take control of a company’s assets when it defaults on secured loans.

There are two types of receivership:

  • Private Receivership: The secured creditor appoints a receiver based on the terms of the security agreement, through an appointment letter.
  • Court-Appointed Receivership: The court appoints a receiver upon application, usually by a secured creditor.

The receiver has the authority to:

  1. Take possession of corporate assets.
  2. Manage the assets, potentially running the business temporarily.
  3. Sell assets to recover the secured creditors’ debts, in order of priority.

The primary responsibility of a privately appointed receiver is to the appointing creditor. In contrast, a court-appointed receiver has a duty to all stakeholders and may be subject to court-imposed restrictions.

Receivership can be a powerful tool for secured creditors seeking to recover their funds, but it often results in the liquidation of the company. It may also occur concurrently with corp bankruptcy proceedings, especially when secured creditors hold significant claims against the company.

Corp Bankruptcy: Weighing the Pros and Cons

Each corp bankruptcy proceeding presents unique advantages and disadvantages. Let’s examine these for each option:

Advantages and Disadvantages of Liquidation

Advantages

Disadvantages

Provides a legal framework for businesses unable to pay their debts.

Results in the closure of the business.

Offers an orderly process for winding down the business.

This may lead to action taken due to personal liability for directors for specific debts.

Facilitates the fair distribution of assets to creditors based on their legal priority.

Can be a time-consuming and expensive process.

Can negatively impact the reputation of the directors.

Advantages and Disadvantages of Reorganization

Advantages

Disadvantages

Offers a chance to save the business and preserve jobs.

May not be successful, leading to eventual liquidation.

Provides an opportunity to improve profitability and efficiency.

Can negatively impact employee morale and customer confidence during the restructuring process.

Allows for the modernization of strategies and financial arrangements.

Requires a significant time investment and may cause cash flow challenges.

Can be conducted informally or formally through the BIA or CCAA.

“Reorganization aims to breathe new life into a struggling company.”

Advantages and Disadvantages of Receivership

Advantages

Disadvantages

Offers a direct and efficient method for secured creditors to recover their funds.

Focuses primarily on protecting the interests of the secured creditor, potentially neglecting the interests of other stakeholders.

May facilitate the sale of the business as a going concern, preserving jobs.

The receiver may face conflicts of interest between their duty to the appointing creditor and their duty to the company.

A businessman on a sinking ship in turbulent waters representing a corporation heading to bankruptcy with a helicopter above throwing a restructuring lifeline.
corp bankruptcy

Corporate Recovery and Restructuring: Exploring Alternatives to Corp Bankruptcy in Canada With Other Potential Recovery Options

Before resorting to corp bankruptcy proceedings, it’s essential to explore alternative solutions that might help your company recover without resorting to formal legal processes.

Here are five alternatives to consider:

Cost-Cutting and Budgeting

Implement tighter spending controls and create a realistic cash flow budget. Identifying and eliminating unnecessary expenses can free up funds to address debt obligations.

Debt Refinancing

Consider looking into refinancing options to combine your current debts into a more manageable repayment plan. This could include discussing with your lenders to secure lower interest rates or longer repayment terms.

Shareholder Investment

Consider seeking additional investment from existing shareholders. This infusion of capital can bolster the company’s financial stability and allow it to meet its obligations.

Informal Debt Settlement

Engage in direct negotiations with creditors to reach an informal debt settlement agreement. This might involve proposing a reduced payment amount or a revised payment schedule.

Asset Sales

Evaluate the possibility of selling non-core assets to raise capital. This can provide immediate cash flow to address pressing debt payments and improve the company’s overall financial health.

Informal workouts, negotiated directly with creditors, often provide a more cost-effective and faster solution than formal corp bankruptcy proceedings. However, they require cooperation and flexibility from all parties involved.

If these alternatives prove insufficient, and the company has the potential for long-term viability, restructuring through the CCAA or a Division I proposal under the BIA becomes a viable option. However, if the company is deemed not viable, receivership may be the most appropriate course of action, especially for secured creditors.

Corp bankruptcy FAQs

  1. What is the difference between “insolvency” and “bankruptcy” in Canada?

While the terms are often used interchangeably, they have distinct meanings under Canadian law. Insolvency is a financial state where a debtor is unable to pay their debts as they become due. This could be due to various reasons like business downturns or personal financial mismanagement.

Bankruptcy, on the other hand, is a legal process initiated when an insolvent person’s assets are transferred to a Licensed Insolvency Trustee. The insolvency trustee then distributes these assets to creditors based on a priority order set by the BIA.

In simpler terms, insolvency is the financial condition, while bankruptcy is the legal process to address it.

  1. What are the primary laws governing insolvency and bankruptcy laws in Canada?

Canada’s insolvency framework primarily comprises two federal statutes: The BIA: This Act applies to both personal and corporate bankruptcies. It outlines the procedures for filing for bankruptcy, governs insolvency trustee licensing, and dictates the distribution of a bankrupt entity’s assets among creditors. The CCAA: This Act provides a framework for restructuring insolvent companies with debts exceeding $5 million. It allows for the creation of a Plan of Arrangement to compromise with creditors or facilitate the sale of the business under court supervision.

  1. What does the Office of the Superintendent of Bankruptcy (OSB) do?

The OSB is the federal agency that oversees bankruptcy processes in Canada. Its main responsibilities include:

  • Overseeing cases under the Bankruptcy and Insolvency Act (BIA) and the Companies’ Creditors Arrangement Act (CCAA).
  • Making sure that the laws set out in the BIA and CCAA are followed.
  • Regulating Licensed Insolvency Trustees.
  • Keeping a public record of filings related to the BIA and CCAA.

4. What happens to a company’s operations when it files for bankruptcy?

Typically, day-to-day business operations cease upon filing for bankruptcy. A LIT takes control of the company’s assets, liquidates them, and distributes the proceeds to creditors based on the BIA’s priority rules.

Shareholders generally lose their investments, and directors may face personal liability for certain debts, depending on specific circumstances and provincial laws.

  1. How does the Canadian insolvency system prioritize creditors?

The BIA establishes a specific order of priority for creditor claims:

  • Deemed trusts: Amounts like unremitted source deductions from employees and unremitted HST are held in trust for the Crown and are paid first.
  • Unpaid suppliers: Suppliers can reclaim unpaid goods delivered within a specific timeframe before bankruptcy.
  • Super-priorities: These include unpaid wages, pension contributions, and costs for environmental cleanup.
  • Secured claims: Creditors with security over specific assets are paid from the proceeds of those assets.
  • Preferred claims: Certain unsecured claims under section 136(1) of the BIA, such as administrative costs of the bankruptcy, are prioritized.
  • Ordinary unsecured claims: All other claims are paid proportionally from the remaining funds.
  1. Can a company avoid bankruptcy in Canada?

Yes, alternatives to bankruptcy debt relief options are:

  • Proposal to Creditors (BIA): A company may propose a plan to restructure its debts and negotiate compromises with creditors. If this proposal is accepted by both the creditors and the court, the company can successfully avert bankruptcy.
  • Restructuring under the CCAA: Corporations with debts exceeding $5 million may seek court protection under the CCAA to undertake a restructuring of their operations and financial obligations.
  • Informal Arrangements: Companies have the option to engage in direct negotiations with creditors to establish informal agreements, which may include debt restructuring or payment deferrals.
  1. What is receivership, and how does it relate to bankruptcy?

Receivership is a legal process where a secured creditor appoints a receiver to take control of a debtor’s assets, typically to enforce a security interest. This appointment can be made privately by the creditor or through a court order.

While receivership can happen at the same time as bankruptcy, it mainly aims to protect the interests of the secured creditor. The receiver may sell off assets to pay back the secured debt, whereas a trustee in bankruptcy oversees the distribution of assets to all creditors following the priorities set out in the BIA.

  1. How can a foreign company with operations in Canada be affected by Canadian insolvency laws?

If a foreign company has assets or carries on business in Canada, it falls under the jurisdiction of Canadian insolvency laws like the BIA and CCAA. It can be subject to bankruptcy proceedings or restructuring efforts in Canada.

The BIA also has provisions for recognizing and cooperating with foreign insolvency proceedings, allowing for coordination between Canadian courts and foreign jurisdictions in cross-border insolvency cases.

Conclusion: Seeking Expert Guidance for Corp Bankruptcy

Navigating the complexities of corp bankruptcy in Canada demands a thorough understanding of the legal frameworks and available options. Bankruptcy, Division I proposals, and receivership each offer distinct paths with varying implications for debt resolution, business operations, and stakeholder interests.

Remember, seeking professional advice is paramount. A LIT and a qualified lawyer specializing in insolvency can provide expert guidance, ensuring you make informed decisions and protect your rights throughout the process. Early intervention and expert assistance can significantly improve the chances of a successful outcome, whether that means restructuring your company or navigating a controlled and dignified wind-down.

I hope you enjoyed this corp bankruptcy Brandon’s Blog. Do you or your company have too much debt? Are you or your company in need of financial restructuring due to distressed real estate or other reasons? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or someone with too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding the bankruptcy process. We can get you debt relief freedom using processes that are a bankruptcy alternative.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a plan, we know that we can help you.

We know that people facing financial problems need a realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team.

That is why we can develop a restructuring process as unique as the financial problems and pain you are facing. If any of this sounds familiar to you and you are serious about finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation. We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The information provided in this Brandon’s Blog is intended for educational purposes only. It is not intended to constitute legal, financial, or professional advice. Readers are encouraged to seek professional advice regarding their specific situations. The content of this Brandon’s Blog should not be relied upon as a substitute for professional guidance or consultation. The author, Ira Smith Trustee & Receiver Inc. as well as any contributors to this Brandon’s Blog, do not assume any liability for any loss or damage resulting from reliance on the information provided herein.

A businessman on a sinking ship in turbulent waters representing a corporation heading to bankruptcy with a helicopter above throwing a restructuring lifeline.
corp bankruptcy
Categories
Brandon Blog Post

WHAT DOES BANKRUPTCY PROTECTION MEAN? THE ABSOLUTELY IMPORTANT THINGS YOU NEED TO KNOW


what does bankruptcy protection mean

What does bankruptcy protection mean? Canada’s Bankruptcy & Insolvency Act

What does bankruptcy protection mean? Bankruptcy protection is a legal status granted to individuals or businesses under Canada’s Bankruptcy and Insolvency Act (BIA). This protection shields debtors from creditor actions while working towards a fresh financial start, whether through bankruptcy or a consumer proposal.

Common questions are:

  • How does bankruptcy protect my assets?
  • What is the difference between a Consumer Proposal and bankruptcy?
  • How does bankruptcy protect my income?
  • Can I file for bankruptcy if I have no assets or income?
  • What happens to my debts after bankruptcy?
  • Do I need a bankruptcy lawyer to file for bankruptcy?

In this Brandon’s Blog, I demystify the concept of bankruptcy protection, shedding light on its significance and the various forms it can take. I answer these and other questions to explain “What Does Bankruptcy Protection Mean?“.

The legal framework of bankruptcy protection is rooted in the BIA in Canada. This act provides a structured process for individuals and business debtors facing overwhelming debt to seek relief and a fresh financial start.

Here’s a breakdown of the key elements:

Automatic Stay: Upon filing for bankruptcy or a Consumer Proposal, an automatic stay comes into effect. This legal measure serves as a shield against creditor actions. It immediately halts all collection attempts, including legal actions, wage garnishments, and asset seizures.

Exempt Assets: Contrary to the misconception that bankruptcy leads to complete asset forfeiture, provincial laws designate certain assets as exempt. These assets, encompassing essential items like household goods, a vehicle, limited home equity, tools of the trade, and certain RRSPs, are protected during bankruptcy proceedings. The specific value allowances for these exemptions vary by province.

Asset Protection Mechanisms: Even if an individual possesses assets exceeding the prescribed exemption limits, there are options to retain them. The repurchase of a person’s equity in the assets allows individuals, such as a family member, to keep an asset by paying the non-exempt portion of its value into the bankruptcy estate.

Alternatives to Bankruptcy: Consumer Proposals offer an alternative path to bankruptcy while still protecting through an automatic stay. In a Consumer Proposal, individuals negotiate a reduced debt repayment plan with their creditors, preserving their assets.

Income Protection: Bankruptcy filings protect income from creditors, effectively preventing wage garnishments and bank account freezes. This protection extends to most creditors, including the Canada Revenue Agency, with exceptions like ongoing child or spousal support payments. During bankruptcy, earned income goes directly to the individual. Depending on the income level, a person may need to pay over a portion using monthly payments for the benefit of the creditors.

It’s worth mentioning that bankruptcy protection laws can be quite complicated. It’s a good idea to consult with qualified professionals, like a licensed insolvency trustee (formerly known as a bankruptcy trustee or a trustee in bankruptcy), who can offer tailored advice and assist you in understanding the process.

what does bankruptcy protection mean

What Does Bankruptcy Protection Mean? Types of Bankruptcy Protection

The BIA is a federal law that covers bankruptcy protection. Provincial laws determine which assets you can keep when filing for bankruptcy. Here are the main types of bankruptcy protection in Canada:

Canadian Liquidation Bankruptcy (known in the United States as a Chapter 7 bankruptcy)

This is a legal process available to both companies and individuals. The company or the person declares themselves unable to repay your debts when filing an assignment in bankruptcy. This results in a stay of proceedings that prevents creditors from taking action against you or your property. A licensed insolvency trustee will be appointed to manage your bankruptcy.

The bankrupt person or company may be required to surrender some assets to the Trustee, who will then sell them and distribute the funds to your creditors. However, for individuals, certain assets are protected under provincial law. For a first-time bankrupt person with no surplus income, you will be discharged from bankruptcy, usually within nine months, after which your debts will be wiped out, with limited exceptions.

Consumer Proposal (known in the United States as a Chapter 13 bankruptcy)

A consumer proposal is a financial restructuring bankruptcy alternative for people who owe $250,000 or less, other than for any debts registered against your principal residence. In a consumer proposal, you offer your creditors a partial repayment of your debt through a licensed insolvency trustee. If your creditors accept the proposal, your debts are consolidated into one settlement, and you make payments over some time, typically up to five years. Your assets are not affected by a consumer proposal, and you are protected from creditor actions while the proposal is in effect.

Commercial Proposal (known in the United States as a Chapter 11 bankruptcy)

Companies, or people who owe more than $250,000, can get bankruptcy protection, restructure their finances and avoid bankruptcy through the commercial proposal section of the BIA.

Restructuring under the Companies’ Creditors Arrangement Act (this is the closest we have to a US Chapter 11 bankruptcy protection filing)

Companies that owe $5 million or more, can gain bankruptcy protection and restructure their operations and finances using federal legislation called the Companies’ Creditors Arrangement Act.

All of the above bankruptcy protection alternatives require a licensed insolvency trustee to administer the process.

What Does Bankruptcy Protection Mean? Key Concepts of Bankruptcy Protection

Automatic Stay

What is a stay of proceedings and how does it work? A stay of proceedings is a legal measure triggered by filing for bankruptcy or a Consumer Proposal for financial restructuring. It immediately halts all creditor actions against you, including collection calls, legal proceedings, and asset seizures. This provides relief from creditor harassment and safeguards your assets and income while navigating the process.

Debt Restructuring through bankruptcy or consumer proposal

Two primary methods for debt restructuring in Canada are bankruptcy and consumer proposals. People understand how consumer proposals are for debt restructuring because that is exactly what it does. But how can personal bankruptcy be a debt restructuring tool?

Both options provide legal protection from creditors and offer a path toward financial stability.

Bankruptcy process

Filing for bankruptcy initiates a legal process and invokes the stay of proceedings. That halts all creditor actions, including collection calls, lawsuits, and wage garnishments. This protection extends to most creditors, including government agencies like the Canada Revenue Agency, with a few exceptions, like family support payments.

A common misconception is that bankruptcy leads to the loss of all assets. However, there are provincial laws in Canada that intersect with federal bankruptcy laws. One such provincial statute is the Ontario Execution Act, R.S.O. 1990, c. E.24, which designates certain assets as “exempt”. These exempt assets, based on liquidation value, not original cost, are protected during bankruptcy and can include:

  • Household furnishings and appliances – $13,150
  • Equity in a vehicle – $6,600
  • Home equity up to $10,000
  • RRSPs, other than for contributions made in the 12 months before filing bankruptcy
  • Medical aids and devices that are required to assist with a disability or a medical or dental condition
  • Cash surrender value of life insurance policies where a spouse or family member is an irrevocable designated beneficiary

Even if an asset exceeds the exemption limit, options exist to retain it. These options include repurchasing the asset by paying the non-exempt value into the bankruptcy estate or including that value in calculating what you need to pay for a successful consumer proposal instead.

To file for bankruptcy, you need to owe at least $1,000. You need debts to file; it doesn’t require any assets or income to be eligible! Individuals with minimal or no assets can still file for bankruptcy and benefit from its protections.

Consumer Proposal

A consumer proposal is a formal arrangement between a debtor and their creditors, arranged through a licensed insolvency trustee. This option helps debtors combine their debts and propose to repay creditors a portion of what they owe, typically between 20% and 50% of the total debt.

Consumer proposals offer several advantages:○

  • You do not lose your assets, making it suitable for those with significant non-exempt assets.
  • Interest charges stop accruing.
  • Creditors are legally prevented from starting or pursuing further collection actions due to the “stay of proceedings”.
  • Although a consumer proposal isn’t technically bankruptcy, it provides similar legal protections and debt relief benefits.

Both bankruptcy and consumer proposals are complex legal processes. Consulting with a licensed insolvency trustee, the only professional authorized to administer these proceedings is crucial to determine the most suitable option for individual circumstances. We can assess your financial situation, explain the implications of each choice, and guide you through the process.

what does bankruptcy protection mean

What Does Bankruptcy Protection Mean? Rights and Responsibilities of Debtors

Rights of Debtors:

  • Stay of Proceedings
  • Asset Protection
  • Options For Non-Exempt Assets
  • Income Protection: Bankruptcy shields debtors’ income from most creditors, protecting them from wage garnishments and bank account seizures. This includes protection from the CRA. There are some specific cases where income protection is not available, such as ongoing child or spousal support payments.
  • Eligibility Regardless of Assets or Income
  • Consumer Proposals as an Alternative: Consumer proposals provide a bankruptcy alternative, allowing debtors to consolidate debts and negotiate a reduced repayment plan with their creditors10. While offering similar creditor protection through a stay of proceedings, consumer proposals do not impact assets, making them attractive for individuals with significant non-exempt equity.

Responsibilities of Debtors:

While the sources primarily focus on the rights and protections offered by bankruptcy and consumer proposals, there are certain inherent responsibilities:

  • Full Disclosure: Debtors are obligated to provide accurate and complete financial information to their licensed insolvency trustee, including all assets, debts, income, and expenses.
  • Cooperation: Debtors must cooperate with their Trustee throughout the bankruptcy or proposal process, attending meetings, providing requested documentation, and adhering to the terms of their agreement.
  • Compliance with Legal Requirements: Debtors must fulfill the specific legal requirements of their chosen debt relief solution, which may include attending financial counselling sessions or making agreed-upon payments.

Choosing the Right Path

Deciding between bankruptcy and a consumer proposal requires careful consideration with the guidance of a licensed insolvency trustee. The Trustee’s expertise helps determine the most suitable option based on individual circumstances, ensuring debtors understand their rights and obligations.

What Does Bankruptcy Protection Mean? The Role of Bankruptcy Courts

In Canada, bankruptcy courts play a crucial role in the administration of bankruptcy and insolvency proceedings. Here are some key responsibilities of bankruptcy courts in Canada:

  • Hearing Bankruptcy Applications: Bankruptcy courts hear petitions filed by individuals or businesses seeking to be declared bankrupt be it personal or business bankruptcy. The court determines whether the applicant is eligible to be declared bankrupt and whether the petition is valid.
  • Approving Reorganization Plans: In cases where a company is seeking to restructure its debt through BIA or CCAA reorganization plans, the bankruptcy court must approve the plan. The court ensures that the plan is fair and reasonable and that it provides for the payment of creditors in a timely manner.
  • Approving Asset Sales: Bankruptcy courts have the authority to approve asset sales conducted by the Trustee. This ensures that the sales are conducted fairly and reasonably and that the assets are sold for a fair price under the circumstances.
  • Hearing Creditors Appealing the Trustee’s Disallowance of Their Claim: Bankruptcy courts hear appeals of claim disallowances against the bankrupt’s estate. The court determines if the Trustee’s decision on the validity and priority of each claim is correct or not if appealed.
  • Approving Settlements: Bankruptcy courts can approve settlements between the Trustee and creditors, ensuring that the settlement is fair and reasonable.
  • Overseeing the Administration of the Bankrupt’s Estate: Bankruptcy courts monitor the administration of the bankrupt’s estate, ensuring that the Trustee is performing their duties following the BIA and that the estate is being managed fairly and reasonably.
  • Making Rulings on Disputes: Bankruptcy courts make rulings on disputes that arise during the bankruptcy process, such as disputes between the Trustee and creditors, or between creditors themselves.
  • Providing Guidance: Bankruptcy courts can guide the Trustee, creditors, and other stakeholders on the interpretation and application of the BIA and other relevant laws in response to such a motion.
  • Bankrupt’s opposed discharges: The Court hears all opposed applications for discharge of the bankrupt person and rules on what kind of discharge the person is entitled to.

    what does bankruptcy protection mean
    what does bankruptcy protection mean

What Does Bankruptcy Protection Mean? The Role of the Office of the Superintendent of Bankruptcy Canada

The Office of the Superintendent of Bankruptcy Canada (OSB) is a federal agency that manages bankruptcy and insolvency proceedings across the country. The OSB is essential for enforcing the BIA and making sure the insolvency system runs smoothly and fairly. Here are some of the main responsibilities of the OSB:

  • Regulation and Oversight: The OSB regulates and oversees the activities of trustees, receivers, and other insolvency professionals to ensure that they comply with the BIA and other relevant laws.
  • Licensing and Registration: The OSB licenses and registers trustees, receivers, and other insolvency professionals, ensuring that they meet the necessary qualifications and standards.
  • Monitoring and Investigation: The OSB monitors and investigates complaints and concerns related to the administration of bankruptcy and insolvency proceedings, including allegations of misconduct or fraud.
  • Enforcement: The OSB enforces the BIA and other relevant laws, including issuing warnings, fines, and penalties to individuals and companies that violate the law.
  • Guidance and Education: The OSB provides guidance and education to stakeholders, including trustees, creditors, and debtors, on the BIA and other relevant laws and regulations.
  • Research and Analysis: The OSB conducts research and analysis on insolvency trends, statistics, and best practices, which help inform policy decisions and improve the effectiveness of the insolvency system.
  • Policy Development: The OSB develops and recommends policies to the Minister of Justice and Attorney General of Canada, which helps shape the direction of the insolvency system.
  • Public Education: The OSB provides public education and awareness campaigns to inform Canadians about the insolvency system, the consequences of bankruptcy, and the importance of financial literacy.
  • Collaboration with Other Agencies: The OSB works closely with other government agencies, such as the CRA and the Financial Consumer Agency of Canada (FCAC), to ensure a coordinated approach to insolvency and debt management.
  • Reporting and Accountability: The OSB is responsible to Parliament and reports directly to the Minister of Justice and Attorney General of Canada. This structure ensures transparency and accountability in its operations and decisions.

In summary, the OSB is essential for maintaining the integrity and efficiency of Canada’s insolvency system and safeguarding the rights of creditors, debtors, and other parties involved.

What Does Bankruptcy Protection Mean? Impacts of Bankruptcy Protection

Financial Relief for Debtors

Bankruptcy provides an opportunity for debt relief. While it does not require the debtor to have any assets, it might involve surrendering non-exempt assets to the bankruptcy estate. However, debtors can explore options like a family member repurchasing assets by paying the non-exempt value or filing a Consumer Proposal, which allows for debt consolidation and partial repayment to creditors without surrendering assets.

Bankruptcy allows individuals and businesses struggling with debt to restructure or eliminate their debts and rebuild a stable financial future. After the personal bankruptcy process, debtors receive a discharge, typically within nine months for a first-time bankrupt person, marking the end of their bankruptcy and the elimination of eligible debts. In corporate bankruptcies, there is not a discharge process.

Effects on Credit Scores

Filing for bankruptcy becomes a matter of public record and is reported to credit bureaus. This information remains on your credit report for a significant period, typically six to seven years in Canada, though this can vary based on provincial laws and the type of bankruptcy protection filed. This negative mark on your credit history will likely result in a significant drop in your credit score.

Lenders use credit scores to assess the risk associated with lending money. A low credit score resulting from bankruptcy makes it difficult to obtain new credit, such as loans, credit cards, or mortgages. Even if you do qualify for credit, you may face less favourable terms, including higher interest rates and lower credit limits.

While not directly related to credit scores, bankruptcy can impact other aspects of your financial life. For instance, some employers and landlords may consider credit history when making hiring or rental decisions.

what does bankruptcy protection mean

What Does Bankruptcy Protection Mean FAQ

Here is our what does bankruptcy protection mean FAQ:

  1. What does “Bankruptcy Protection” mean? Bankruptcy protection refers to the legal safeguards provided to individuals or companies when they file for bankruptcy. It essentially halts all debt collection activities, legal actions, and wage garnishments by creditors. This protection is activated through an “automatic stay” upon filing for bankruptcy.
  2. What does Bankruptcy Protection protect? Bankruptcy protection is designed to help you keep your assets safe from creditors. It provides a legal way to either reorganize your finances or sell off assets in an orderly fashion under court oversight. Many people think that filing for bankruptcy means you have to give up everything, but that’s not the case. Some laws allow you to keep important items such as your home, car, and personal possessions.
  3. How does the automatic stay work? The automatic stay is a court order that takes effect immediately upon filing for bankruptcy. It acts as a legal shield, prohibiting creditors from taking any further action to collect debts incurred before the bankruptcy filing. This includes stopping lawsuits, wage garnishments, bank account freezes, and even harassing phone calls.
  4. Does filing for bankruptcy mean I will lose all my assets? Not necessarily. While bankruptcy may involve liquidating some assets to repay creditors, the bankruptcy code provides exemptions that allow you to keep certain assets deemed necessary for your livelihood. These exemptions vary by state but generally include a homestead exemption for your primary residence, a vehicle exemption, and exemptions for personal property like clothing, furniture, and tools needed for your profession.
  5. How does bankruptcy protection help me keep my assets? Bankruptcy protection helps preserve your assets in two primary ways:
  6. Automatic Stay: It prevents creditors from seizing your assets while you reorganize your finances or create a repayment plan. Exemptions: These legal provisions shield specific assets from liquidation, ensuring you retain essential possessions.
  7. What is the difference between Bankruptcy and a Consumer Proposal? Bankruptcy means selling off non-exempt assets to repay creditors. It’s generally an option for individuals or businesses that are struggling with low income and limited assets. On the other hand, a consumer proposal is a way for individuals with a steady income to suggest a repayment plan to their creditors that lasts up to five years. This option lets you keep your assets while getting rid of your debt.
  8. How can I learn more about bankruptcy protection and whether it’s right for me? If you’re looking to learn more about bankruptcy protection and whether it’s the right choice for you, it’s important to talk to a licensed insolvency trustee. They can provide insights tailored to your financial situation, explain the various bankruptcy options available, clarify how it might affect your assets, and help you navigate the legal steps involved.
  9. What are some misconceptions about bankruptcy? You will lose everything: While some assets may be liquidated, exemptions exist to protect essential belongings. It will ruin your credit forever: While bankruptcy negatively impacts credit scores, it is possible to rebuild credit over time with responsible financial management. It is a mark of shame: Bankruptcy is a legal process designed to provide individuals and businesses with a fresh financial start.

What Does Bankruptcy Protection Mean Conclusion

Navigating the world of bankruptcy protection can feel daunting, but fear not! It’s a valuable safety net designed to help both individuals and businesses get back on their feet during tough financial times. Think of it as a wonderful opportunity to reorganize debts and embrace a fresh start.

By familiarizing yourself with the different types of bankruptcy, understanding the implications of filing, and discovering how it may affect your credit score, you’ll be well-equipped to make smart choices for your financial future. While bankruptcy isn’t the perfect fit for everyone, it can truly be a lifesaver for those in need of a financial reboot. So take a deep breath and explore your options—you’ve got this!

I hope you enjoyed this what does bankruptcy protection mean Brandon’s Blog. Do you or your company have too much debt? Are you or your company in need of financial restructuring due to distressed real estate or other reasons? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or someone with too much personal debt.

You are worried because you are facing significant financial challenges. It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding the bankruptcy process. We can get you debt relief freedom using processes that are a bankruptcy alternative.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a plan, we know that we can help you.

We know that people facing financial problems need a realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team.

That is why we can develop a restructuring process as unique as the financial problems and pain you are facing. If any of this sounds familiar to you and you are serious about finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.

Call us now for a free consultation. We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The information provided in this Brandon’s Blog is intended for educational purposes only. It is not intended to constitute legal, financial, or professional advice. Readers are encouraged to seek professional advice regarding their specific situations. The content of this Brandon’s Blog should not be relied upon as a substitute for professional guidance or consultation. The author, Ira Smith Trustee & Receiver Inc. as well as any contributors to this Brandon’s Blog, do not assume any liability for any loss or damage resulting from reliance on the information provided herein.

what does bankruptcy protection mean
Categories
Brandon Blog Post

NAVIGATING BUSINESS INSOLVENCY IN CANADA: A LAWYER AND ACCOUNTANT’S COMPREHENSIVE GUIDE TO MASTERING INSOLVENCY LAW

Introduction to Business Insolvency

Welcome to our Brandon’s Blog where we will explore the intricate world of insolvency and its profound impact on businesses in Canada from my perspective as a professional in the field. In this exploration of business insolvency, we will uncover the implications that insolvency brings for creditors, shareholders, their lawyers and accountants, and employees alike.

Understanding the complexities of financial distress is crucial for businesses to navigate through turbulent times successfully. Join me as we discuss effective strategies and best practices to mitigate the challenges of insolvency, ensuring a smoother transition toward financial stability.

Definition of Business Insolvency

Business insolvency in the Canadian context refers to the financial state of a business where it is unable to pay its debts as they become due. It is a financial condition, not a legal one. Do not confuse the business or company with the financial condition of being an insolvent person with the legal condition of being involved in bankruptcy proceedings. Corporate insolvency is not corporate bankruptcy.

Corporate insolvency results in the business being unable to pay its debts when due which may make it impossible for the business to continue its operations. Insolvent companies may very well end up in the legal state of bankruptcy or as an alternative to bankruptcy, in insolvency restructuring proceedings.

Business insolvency can force the business to choose one of the insolvency options for businesses, including bankruptcy filings or proposals for restructuring and repayment plans under the Bankruptcy and Insolvency Act (Canada) (BIA).

In Canada, the number of business insolvencies has been on the decline for many years, but the impact of the COVID-19 pandemic has seen a reversal of this trend. Business insolvency filings are on the rise again. However, there are many small businesses where a business bankruptcy process does not make any sense as there are either no or few assets to offset the large company debts. We get calls daily from entrepreneurs of such companies where we tell them it is in their best interests to merely close the business doors rather than spend money to put their company into bankruptcy.a picture of an overwhelmed man to represent the owner of an insolvent company turning into a picture of a calm and happy business owner representing a solvent and profitable company with people walking up a staircase representing company profitability and growth

Causes and Warning Signs of Business Insolvency

Economic Downturn and Market Volatility

One of the primary contributors to business insolvency in Canada is the unpredictable nature of economic fluctuations and market volatility. As businesses strive to adapt to shifting market trends and consumer demands, they are often met with unforeseen challenges that can strain financial resources. Economic downturns, changes in consumer behaviour, and global market dynamics all play a pivotal role in determining the financial health of businesses across various sectors.

Cash Flow Problems: Overleveraging and Excessive Debt Burden

Another significant factor that can precipitate business insolvency is overleveraging and an excessive debt burden. While leveraging can be a strategic tool for growth and expansion, it becomes problematic when businesses accumulate debt beyond their capacity to repay. High levels of debt, coupled with declining revenues or profitability, can create a precarious financial situation, ultimately leading to insolvency if left unaddressed.

Poor Financial Planning and Management

Effective financial management and planning are essential components of sustainable business operations. However, inadequate financial oversight and poor planning can leave businesses vulnerable to insolvency. From misaligned budgeting strategies to ineffective cash flow management, deficiencies in financial management practices can exacerbate existing challenges and hasten the onset of insolvency.

Navigating the complex regulatory landscape in Canada can pose significant challenges for businesses, especially concerning compliance and legal matters. Failure to adhere to regulatory requirements, such as tax obligations or industry-specific regulations, can result in legal disputes, penalties, and fines, placing additional strain on financial resources. Moreover, litigation and legal challenges can further impede business operations and contribute to business insolvency.

Technological Disruption and Industry Shifts

The rapid pace of technological innovation and industry shifts can disrupt traditional business models and market dynamics, presenting both opportunities and challenges for businesses in Canada. Failure to embrace technological advancements or adapt to changing industry trends can render businesses obsolete or inefficient, leading to a decline in competitiveness and financial viability. As such, businesses must remain agile and proactive in leveraging technology to stay ahead of the curve and mitigate the risk of insolvency.

External Shocks and Unforeseen Events

External shocks and unforeseen events, such as natural disasters, geopolitical instability, or pandemics, can have profound implications for business continuity and financial stability. The unprecedented disruptions caused by such events can severely impact supply chains, disrupt operations, and erode consumer confidence, thereby jeopardizing the financial health of businesses. While certain external shocks may be beyond the control of businesses, proactive risk management and contingency planning are essential to mitigate their adverse effects.

Remember, proactive planning, decisive action, and collaboration with knowledgeable professionals are the cornerstones of navigating business insolvency effectively.

Business Insolvency: Overview of Insolvency Law in Canada

In Canada, insolvency law plays a vital role in guiding businesses through financially distressed situations. As a professional knowledgeable in this field, I will delve into the types of insolvency proceedings and the key legislation and regulations that govern insolvency processes.

  • Types of Insolvency Proceedings: In Canada, businesses can navigate various types of insolvency proceedings:
    • bankruptcy;
    • proposal;
    • corporate restructuring;
    • receivership.

Bankruptcy involves the liquidation of assets to repay creditors, while a proposal allows for negotiating repayment plans to avoid bankruptcy. For larger corporations, corporate restructuring under different legislation than a proposal (discussed next) is available. Finally, when a secured creditor enforces its security to liquidate the business assets, that is receivership.

Understanding the nuances between these proceedings is essential for businesses facing financial challenges. All of these proceedings are described in detail in my previous blogs in the Lawyer and Accountant Series over the last few weeks.

  • Key Legislation and Regulations: The BIA applies to all business bankruptcy, proposal and receivership proceedings in Canada. The Companies’ Creditors Arrangement Act (CCAA) applies to corporations that owe more than $5 million to creditors who wish to avail themselves of Canadian bankruptcy protection to restructure their operations and finances.

These are the pivotal legislation for an insolvent person, be they a consumer, individual, proprietorship, partnership or corporation. They govern personal insolvency and business insolvency in Canada. The BIA will govern any personal bankruptcy or corporate bankruptcy.

Understanding these aspects of insolvency law is imperative for businesses as they navigate through financial difficulties. By recognizing the procedures and regulations outlined in the key legislation, businesses can protect their interests and work towards a successful resolution of insolvency issues.

As we continue to unravel the intricate landscape of insolvency law in Canada, I will now explore the specific roles of lawyers and accountants in business insolvency, shedding light on their invaluable contributions to navigating insolvency proceedings effectively.a picture of an overwhelmed man to represent the owner of an insolvent company turning into a picture of a calm and happy business owner representing a solvent and profitable company with people walking up a staircase representing company profitability and growth

Role of a Lawyer in Business Insolvency

Lawyers play a critical role in guiding businesses through the challenging landscape of insolvency. There are many complexities and responsibilities involved in representing clients during financial distress. Let’s explore the legal responsibilities and duties, as well as effective strategies for representing clients in insolvency proceedings.

A lawyer’s primary responsibility is to ensure that their clients navigate the legal proceedings smoothly, legally and ethically. Upholding the highest standards of professionalism and compliance with relevant laws is paramount in protecting the interests of all involved parties. From providing sound legal advice to negotiating on behalf of clients, every action must align with the legal framework outlined in insolvency law.

In insolvency proceedings, it’s essential to draft and review legal documents meticulously, such as restructuring plans and agreements, to safeguard the rights of creditors, shareholders, and employees. Transparency and adherence to the law are non-negotiable aspects that guide a lawyer’s responsibilities in representing clients effectively.

Strategies for Representing Clients

When representing clients in business insolvency cases, adopting a strategic approach is key to achieving successful outcomes. Clear communication with clients to understand their objectives and concerns forms the foundation of developing a tailored strategy. By conducting in-depth research, analyzing financial documents, and collaborating with other professionals like accountants and insolvency practitioners, lawyers can offer comprehensive legal services.

Each client’s situation is unique, requiring a personalized strategy that addresses their specific needs and goals. Through a combination of legal expertise, practical considerations, and proactive communication, lawyers strive to navigate the complexities of insolvency proceedings effectively. By working collaboratively with clients and other professionals, especially the insolvency professionals, they can secure the best possible resolutions for their clients’ insolvency challenges.

Role of an Accountant in Business Insolvency

Accountants also play a critical role in the realm of business insolvency. The CPA understands the importance of financial analysis and compliance with accounting standards in navigating through the complexities of insolvency. Let’s explore how accountants play a pivotal role in helping businesses facing financial distress.

Financial Analysis and Reporting

Financial analysis and reporting are fundamental aspects of dealing with business insolvency. The accountant’s role involves carefully assessing the financial health of a company experiencing insolvency issues. By analyzing crucial financial statements, cash flow projections, and other relevant data, CPAs can provide insights that help the business understand its current financial situation.

Through their expertise in financial analysis, CPAs identify key areas of concern and create accurate reports that are essential for stakeholders, including creditors, shareholders, and employees, to make informed decisions. Effective financial analysis enables businesses to develop strategies for managing financial distress, paving the way for a smoother resolution of insolvency issues.

Compliance with Accounting Standards

Compliance with accounting standards is a cornerstone for businesses navigating insolvency in Canada. The CPA will ensure that the financial statements are prepared in adherence to the relevant accounting principles and regulations. This commitment to compliance promotes transparency and upholds the integrity of financial reporting.

By maintaining strict compliance with accounting standards, businesses demonstrate their dedication to ethical practices and financial accuracy. This, in turn, fosters trust among creditors, shareholders, and other stakeholders during times of financial distress. Upholding accounting standards is crucial for businesses to mitigate legal and financial risks, emphasizing the need for meticulous attention to regulatory requirements.

CPAs recognize the significance of financial analysis and compliance with accounting standards in guiding businesses through the insolvency process. By providing invaluable financial expertise ensuring adherence to regulatory guidelines, and working with other professionals, especially the insolvency professionals, the external CPA supports businesses in making well-informed decisions and navigating the complexities of business insolvency successfully.

This is how both non-insolvency lawyers and accountants can still play a meaningful role in business insolvency, especially in a business restructuring process. A successful outcome of the business restructuring is the best way for the existing lawyer and accountant to maintain both the client but also a close meaningful business relationship for the long term.a picture of an overwhelmed man to represent the owner of an insolvent company turning into a picture of a calm and happy business owner representing a solvent and profitable company with people walking up a staircase representing company profitability and growth

Impact of Business Insolvency

Job Losses and Unemployment

The impact of Canadian business insolvency on job losses and unemployment can be significant. When a business becomes insolvent, it may be forced to lay off employees or shut down entirely, leading to job losses. This can result in a higher unemployment rate as workers find themselves without a job and struggle to secure new employment.

The COVID-19 pandemic has exacerbated these challenges, with many entrepreneurial businesses in Canada continuing to face financial difficulties and the continued risk of closure. Such businesses are still struggling to return to normal revenues, carry unpaid debt taken on during the pandemic, and face rising costs and a shortage of labour.

Targeted measures and support for small businesses are crucial to prevent closures and job losses. By assisting, such as financial aid, access to resources, and support for restructuring, the impact of business insolvency on job losses and unemployment can be mitigated. Additionally, policies like the recent amendments to prioritize creditor claims related to defined-benefit pension plans can help protect employees’ financial security in the event of insolvency.

Effects on Suppliers and Creditors

The effects of Canadian business insolvency on suppliers and creditors can be significant. When a business becomes insolvent, suppliers may face challenges in receiving payment for goods or services provided to the business. This can result in financial difficulties for the suppliers themselves, especially if they rely heavily on the insolvent business as a major customer.

Creditors, including financial institutions and other lenders, may also experience losses when a business files for bankruptcy or proposes a restructuring plan. In most cases, creditors will not receive the full amount owed to them, or they may have to wait a significant amount of time to receive any repayment.

Overall, Canadian business insolvency can have a ripple effect on suppliers and creditors, leading to financial challenges and losses for those involved in the business’s operations. Suppliers and creditors need to assess their credit risks before extending credit and take appropriate measures to protect their interests in the event of a business insolvency.

Potential Closure or Sale of the Business

In Canadian business insolvency, the potential closure or sale of the business can have significant implications for the business owner, employees, creditors, and the economy as a whole. If an entrepreneurial business is unable to meet its financial obligations and is forced to close its doors, it can result in job losses, financial losses for creditors, and a decrease in economic activity in the local community.

For the business owner, the closure or sale of the business can mean the end of their entrepreneurial venture, financial loss, and potential personal liability for both Director liabilities as well as any corporate debt personally guaranteed by the entrepreneur. Such liabilities can have a significant impact on their financial well-being and prospects.

For employees, the closure of a business can result in job loss, uncertainty, and financial hardship. They may struggle to find new employment, especially if the closure is due to broader economic challenges in the industry or region.

For creditors, the closure of a business can mean they probably will not recover the full amount owed to them. They may have to write off the debt as a loss, which can impact their financial stability and ability to extend credit to other businesses.

In terms of the economy, the closure or sale of a business can contribute to a decrease in economic activity, reduced consumer confidence, and a negative impact on the overall business environment. It can also lead to a loss of tax revenue for the government, further impacting public services and infrastructure.

Overall, the potential closure or sale of a business in a Canadian business insolvency is a complex and challenging situation that requires careful consideration of the implications for all stakeholders involved. It underscores the importance of effective financial management, planning, and risk mitigation strategies for entrepreneurial businesses to avoid insolvency and closure in the first place.

Reputation Damage

Reputation damage arising from a Canadian business insolvency can have long-lasting effects on a company. When a business becomes insolvent, it is unable to fulfill its financial obligations, leading to creditors and suppliers losing trust in the company. This can result in difficulty in securing credit, partnerships, and contracts in the future.

Moreover, news of a business insolvency can spread quickly, damaging the company’s reputation among customers and stakeholders. Customers may lose faith in the company’s ability to deliver products or services, leading to a loss of business and revenue. Employees may also become concerned about job security and employee wages. Morale suffers and the most qualified employees can find new jobs quickly. All of this leads to morale suffering which makes the business insolvency closer to a self-fulfilling prophecy.

Reputation damage from a business insolvency can be difficult to overcome. Rebuilding trust with creditors, suppliers, customers, and employees may take time and effort. Companies trying to implement a restructuring insolvency plan need to implement strong communication strategies to address concerns and demonstrate a commitment to financial stability and responsibility.

Overall, reputation damage arising from Canadian business insolvency can have significant consequences for a company’s long-term success and viability. Businesses need to address insolvency issues promptly and transparently to mitigate potential reputational harm.

Initiating the Insolvency Process

In Canada, the process of initiating insolvency proceedings is a critical step for businesses facing financial distress. There are two kinds of processes; 1. voluntary and 2. involuntary.

The voluntary process normally begins with the insolvent business formally declaring insolvency by filing for bankruptcy protection under either the BIA or CCAA to begin the restructuring process. Alternatively, the insolvent business can file corporate bankruptcy if liquidation is the only answer for a business that is no longer viable.

The involuntary process would normally begin with either a secured creditor privately appointing or making an application to the Court for the appointment of a receiver. Alternatively, one or more unsecured creditors owed in total at least $1,000 can launch a Bankruptcy Application against the insolvent company.

Seeking professional guidance from experts like insolvency lawyers and licensed insolvency trustees is essential to navigate this complex process effectively. Businesses can begin addressing their financial challenges by initiating insolvency proceedings and working toward a resolution.

Managing Stakeholder Relationships

Managing stakeholder relationships is paramount during times of business insolvency in Canada. Creditors, shareholders, and employees all have vested interests in the outcome of insolvency proceedings. Effective communication and transparency are essential to build trust and mitigate potential conflicts. By keeping stakeholders informed, addressing their concerns, and involving them in decision-making processes, businesses can navigate insolvency proceedings with clarity and confidence.

Business insolvency is a complex issue that requires careful navigation. By understanding the implications for all stakeholders and seeking professional advice, businesses can better prepare for financial challenges.a picture of an overwhelmed man to represent the owner of an insolvent company turning into a picture of a calm and happy business owner representing a solvent and profitable company with people walking up a staircase representing company profitability and growth

There are two main avenues for addressing legal issues within insolvency cases: 1. Negotiation and Mediation Techniques, as well as 2. Litigation and Court Proceedings. I will now delve into the strategies and approaches essential for navigating through challenging financial times successfully.

Negotiation and Mediation Techniques

When faced with legal issues within insolvency cases, negotiation and mediation techniques can be powerful tools for finding amicable solutions. Insolvency trustees find that engaging in constructive dialogue with stakeholders can often lead to mutually beneficial outcomes. By exploring innovative and collaborative approaches, businesses can avoid unnecessary conflicts and costly legal battles.

  1. Effective negotiation involves understanding the concerns and needs of all parties involved.
  2. Mediation offers a platform for open communication, ensuring that diverse perspectives are heard and respected.
  3. Skilled mediators facilitate the process, guiding toward agreements that protect the interests of creditors, shareholders, and employees.

By adopting a strategic and empathetic approach to negotiation and mediation, businesses can navigate the complexities of insolvency issues with resilience and integrity. The ability to find common ground and explore creative solutions is essential in any business restructuring.

Litigation and Court Proceedings

While negotiation and mediation are preferred methods for resolving legal issues within the insolvency case, there are instances where litigation and court proceedings become inevitable. This is more so within a liquidating bankruptcy proceedings rather than in a business reorganization. Licensed insolvency trustees understand the importance of legal recourse in protecting the rights and interests of all stakeholders involved.

  1. Litigation provides a formal platform for resolving disputes and making legally binding decisions.
  2. Court proceedings ensure that insolvency matters are adjudicated fairly and by the law.
  3. Legal experts specializing in insolvency law offer invaluable guidance throughout the litigation process.

By preparing meticulously and engaging competent legal representation, businesses can navigate the complexities of court proceedings with confidence. While litigation may signify a more adversarial approach, it can also lead to definitive resolutions that provide clarity and direction in times of financial turmoil.

4 Common Business Insolvency FAQs

  1. What is the difference between company insolvency and personal bankruptcy?

Company insolvency refers to a company that is unable to pay its bills and debts owed, while personal bankruptcy is a legal process for individuals who cannot pay their bills to eliminate debt.

  1. When should a company consider filing for bankruptcy?

A company should consider filing for bankruptcy or bankruptcy protection to restructure when they are facing overwhelming financial difficulties, such as a loss of income, high levels of debt, inadequate cash flow, and reliance on personal credit to meet obligations. This only makes sense if action is taken relatively early in the insolvency when there are still assets that can be used in perhaps a different corporate form to continue to run the viable part of the insolvent business.

  1. How much debt does a business need to owe to file for bankruptcy in Canada?

In Canada, an insolvent person or insolvent business needs to owe $1,000 or more to unsecured creditors to be eligible to file for bankruptcy.

  1. Can sole proprietorships and partnerships file for business bankruptcy?

Yes, sole proprietorships and partnerships can file for business bankruptcy, and they would need to work with a Licensed Insolvency Trustee to do so. In these forms of business, it is the sole proprietor or partners who would be filing bankruptcy. As this would be a consumer insolvency, the bankruptcy rules dealing with the insolvency of individuals would guide this kind of bankruptcy process.

Business Insolvency Conclusion

Navigating business insolvency in Canada is a multifaceted challenge that requires careful consideration and strategic planning. As a licensed insolvency trustee, I have explored the intricacies of insolvency law and its impact on businesses, creditors, shareholders, and employees. Understanding the complexities of insolvency is pivotal for businesses to weather financial storms successfully for a brighter financial future.

The role of corporate lawyers and accountants in helping to guide businesses through insolvency proceedings is an important one. By recognizing the significance of legal responsibilities, financial analysis, and compliance with accounting standards, businesses, with the help of a Licensed Insolvency Trustee and insolvency legal counsel can tackle insolvency issues with confidence and resilience.

I hope you enjoyed this business insolvency Brandon’s Blog. Individuals and business owners must take proactive measures to address financial difficulties, consumer debt and company debt and promptly seek assistance when necessary. It is crucial to recognize that financial stress is a prevalent concern and seeking help is a demonstration of fortitude, rather than vulnerability. Should you encounter challenges in managing your finances and find yourself burdened by stress, do not delay in pursuing aid.

Revenue and cash flow shortages are critical issues facing people, entrepreneurs and their companies and businesses with debt problems that are in financial distress. Are you now worried about just how you or your business are going to survive? Are you worried about what your fiduciary obligations are and not sure if the decisions you are about to make are the correct ones to avoid personal liability? Those concerns and more associated with your company debt are obviously on your mind.

The Ira Smith Team understands these overwhelming debt financial health concerns. More significantly, we know the requirements of the business owner or the individual who has way too much financial debt. You are trying to manage these difficult financial problems and you are understandably anxious. It is not your fault you can’t fix this problem on your own and it does not mean that you are a bad person. The pandemic has thrown everyone a curveball. We have not been trained to deal with this. You have only been taught the old ways. The old ways do not work anymore.

The Ira Smith Team uses innovative and cutting-edge methodologies, to adeptly navigate you through the intricacies of your financial challenges ensuring a resolution to your debt-related predicaments without resorting to the rigours of the bankruptcy process. We can get you debt relief now! We have helped many entrepreneurs and their insolvent companies who thought that consulting with a Trustee and receiver meant their company would go bankrupt.

On the contrary. We helped turn their companies around through financial restructuring. We look at your whole circumstance and design a strategy that is as distinct as you are. We take the load off of your shoulders as part of the debt settlement strategy we will draft just for you.

The Ira Smith Trustee & Receiver Inc. team understands that people facing money problems require a lifeline. That is why we can establish a restructuring procedure for you and end the discomfort you feel. Call us now for a no-cost consultation. We will listen to the unique issues facing you and provide you with practical and actionable ideas you can implement right away to end the pain points in your life, to begin your debt-free life, Starting Over, Starting Now.a picture of an overwhelmed man to represent the owner of an insolvent company turning into a picture of a calm and happy business owner representing a solvent and profitable company with people walking up a staircase representing company profitability and growth

Categories
Brandon Blog Post

Corporate Bankruptcy in Canada: The Essential Truth On What Actually Happens to Your Company, Your Assets and You

I hope you’re safe and well. If your Canadian company can’t pay its debts, it is understandable to worry about what happens next: to the business, its assets, its employees and you personally. Corporate bankruptcy in Canada is one possible route, but it is not the only one. The first step is to understand whether the business can be reorganized or whether an orderly wind-down is the more realistic path.

Corporate Bankruptcy in Canada: Key Takeaways

  • The first question is viability: can the company operate sustainably if its debt or operations are restructured?
  • A corporate bankruptcy in Canada is a legal process under the Bankruptcy and Insolvency Act (BIA) administered by a Licensed Insolvency Trustee (LIT). It does not automatically make directors bankrupt.
  • A Division I Proposal or a proceeding under the Companies’ Creditors Arrangement Act (CCAA) may give a viable business time and legal protection to restructure.
  • In bankruptcy, the trustee administers the company’s property, subject to valid secured claims and statutory priorities. Ordinary unsecured creditors are generally near the end of the distribution order.
  • Personal guarantees and certain director liabilities, including some unremitted source deductions and GST/HST obligations, may survive the company’s filing.
  • Before deciding, gather current financial records and get advice on cash flow, secured debt, tax remittances, employee claims, guarantees and available restructuring options.

Highlights


Is my company viable, and why does that question come first?

In my first meeting with directors, I ask what the business would look like with a workable debt burden and enough cash to meet its ongoing obligations. I also ask whether there are parts of the business they would rather not continue and whether they could find a way to do that. Those questions help distinguish a reorganization, an attempt to change the company’s finances or operations so it can continue, from liquidation, the sale of assets to satisfy claims and wind down the business.

Viability is not simply whether the company has customers or valuable equipment. We look at realistic cash flow, operating costs, profitability potential, debt, the security granted to lenders, tax arrears, employee obligations and whether new financing or a restructuring plan is achievable. A business can be busy and still lose money on every job. It can also have a sound core business but be overwhelmed by debt, a temporary cash crunch or an unsustainable cost structure.

What owners are usually surprised to learn is that filing for corporate bankruptcy in Canada is not the first decision we have to make. We first need to understand the company’s position and compare realistic paths. That is how we avoid rushing into a process that may not serve the business or its stakeholders.

Business professionals reviewing a cash-flow forecast and discussing a potential recovery plan to avoid a corporate bankruptcy in Canada

As context, the Office of the Superintendent of Bankruptcy (OSB) reported that Canadian business insolvencies in August 2026 were 4.9% higher than in August 2025, while business insolvencies over the 12 months ending August 2026 were 6.6% lower year over year. These are national figures, not a prediction for any one company. See the OSB’s August 2026 insolvency statistics.


What is corporate bankruptcy in Canada, exactly?

A corporation is a separate legal entity. When it becomes insolvent, it may make an assignment in bankruptcy under the federal Bankruptcy and Insolvency Act (BIA). Insolvent generally means the company cannot meet its obligations as they become due, has stopped paying current obligations in the ordinary course, or has insufficient property to pay its obligations.

A Licensed Insolvency Trustee is a federally licensed professional authorized to administer bankruptcy and proposal proceedings. In a corporate bankruptcy in Canada, the trustee administers the corporation’s estate (the property and claims dealt with in the proceeding) and distributes available proceeds according to the law. Unlike an individual, a corporation does not receive a discharge that lets it resume life free of old debt. Bankruptcy is usually part of a wind-down, followed by the end of the business once the estate is administered.

The distinction matters for an unincorporated business. A sole proprietorship is not legally separate from its owner, and a partnership can expose partners to personal liability, depending on its structure and circumstances. Those situations may involve personal insolvency, not a corporation’s bankruptcy. The rules and consequences differ.


What are the reorganization paths: Division I Proposal and CCAA?

When a business has a credible path forward, a formal restructuring can provide time to negotiate with creditors and try to preserve value. The two main statutory routes are a Division I Proposal under the BIA and a CCAA proceeding.

A Division I Proposal is a formal offer to creditors to compromise or reschedule debts. It is administered by an LIT and can give the company a statutory stay. A pause on certain creditor enforcement actions. Under the BIA, section 69(1) applies to a Notice of Intention To Make a Proposal, and section 69.1(1) applies to a proposal. A proposal requires approval by the required majority in number and at least two-thirds in value of creditors who vote, followed by court approval. If creditors reject the proposal, or the court refuses to approve it, the company is automatically deemed to have made an assignment in bankruptcy. See the BIA provisions on proposals.

A CCAA proceeding is a court-supervised restructuring generally available to an insolvent company, or affiliated companies, with claims of at least $5 million. The court can grant a stay, appoint a monitor and oversee a plan or other restructuring steps. Creditors vote in classes; approval generally requires a majority in number and two-thirds in value of voting creditors in each class, followed by court sanction. For an overview, see the OSB’s CCAA information.

The CCAA threshold is not a cap on BIA proposals: a Division I Proposal is not limited to companies with less than $5 million in debt. The right process depends on the company’s needs, complexity, creditor structure and ability to fund a restructuring.

An informal workout is a negotiated agreement with creditors outside a formal court process. It may be less disruptive, but a creditor that has not agreed to the arrangement is generally not bound by it.

Which path might fit? This table is a high-level guide, not a recommendation for a particular company. Costs, outcomes and legal effects depend on the facts.

PathWhat it isWho it may suitCourt or court-free?What happens to the business?What happens to directors?Typical cost and main risk
BIA bankruptcy liquidationTrustee administers the corporation’s bankruptcy estate and realizes available assets.A company without a viable, fundable restructuring path.Formal statutory process; court involvement may arise in disputes or applications.Operations often stop or change; assets may be sold and the company wound down.Not automatically bankrupt; guarantees and statutory liabilities may remain.Fees and expenses depend on assets and complexity. Risk: insufficient proceeds and remaining personal exposure.
Division I ProposalBIA compromise or rescheduling of debts, administered by an LIT.A company with a workable plan and ability to meet proposal obligations.Formal process with creditor voting and court approval.May continue operating while it pursues the proposal, subject to the process and circumstances.Not automatically bankrupt; director protections or releases are not blanket guarantees.Professional and administration costs vary. Risk: rejection, failure to perform or deemed bankruptcy.
CCAAFlexible court-supervised restructuring under the CCAA, generally for claims of more than $5 million.A larger or more complex restructuring needing court-managed relief.Court-supervised; a monitor is appointed.May continue operating, restructure, sell assets or pursue another court-approved outcome.Directors remain responsible for their own legal obligations; court relief is case-specific.Usually significant professional and court costs. Risk: plan failure, value loss or unsuccessful financing.
Informal workoutVoluntary negotiation with creditors outside a statutory filing.A company able to negotiate and obtain necessary creditor cooperation.Court-free unless a dispute or later proceeding requires court action.Usually continues operating under agreed terms.Directors continue managing, subject to duties and any agreements or security rights.No single standard cost; advisory costs may apply. Risk: a non-consenting creditor may enforce its rights.

Scroll the table sideways to see every column. General information only. The appropriate process depends on the company’s facts, assets, liabilities, financing and objectives.

What actually happens in a corporate bankruptcy liquidation?

Prior to filing a voluntary corporate bankruptcy in Canada, it always begins with a review of the company’s financial position to understand which option is best for the company. Before any formal insolvency process under either the BIA or CCAA, a board resolution authorizing the filing is required. The LIT prepares the required documents, including a statement of affairs, which is a summary of the company’s assets, liabilities and creditors. The LIT files, in this case, a corporate assignment in bankruptcy with the OSB, which issues a Certificate of Appointment confirming the corporate bankruptcy in Canada event date and time, the trustee’s appointment and the date and time of the First Meeting of Creditors.

The trustee takes control of the bankruptcy estate and administers the company’s unencumbered assets. Unencumbered means not subject to a valid security interest or other property right. A secured creditor may have separate rights to its collateral, and those rights must be reviewed rather than assumed away by the filing.

The trustee notifies creditors, reviews claims, realizes on unencumbered assets where appropriate and reports on the administration. A meeting of creditors is held as required by the BIA. The trustee ultimately distributes funds according to the statutory scheme and the circumstances of the estate. The company may stop operating immediately upon filing or sometime thereafter, but the timing and steps depend on whether continuing operations briefly would preserve value or assist a sale.

Who gets paid first, and who is last?

No universal one-line order applies to every dollar or asset. A valid secured creditor generally looks first to the collateral covered by its security. Certain statutory claims can affect priority. For example, unremitted employee source deductions are a deemed-trust claim and rank ahead of secured claims. The treatment of GST/HST is not identical; the specific statute, timing and proceeding matter. In a corporate bankruptcy in Canada, the GST/HST claim becomes an unsecured claim.

After secured and statutory rights are addressed, the BIA provides for specified preferred claims, such as certain employee claims, ahead of ordinary unsecured claims. Suppliers and other ordinary unsecured creditors generally share in any available distribution after higher-ranking claims. Shareholders are last: they receive value only if all prior claims are paid, which is uncommon in an insolvent liquidation.

The Supreme Court of Canada’s decision in Century Services Inc. v. Canada (Attorney General), 2010 SCC 60, illustrates why tax priority cannot be assumed in every restructuring: the treatment of a Crown deemed trust depends on the statute and the insolvency proceeding. The practical benefit of a claim-by-claim review is that directors and creditors can make decisions based on actual priorities, not a generic list.

What does company failure mean for directors, guarantees and CRA?

Corporate bankruptcy in Canada does not automatically make its directors personally responsible for every corporate debt. But that does not mean directors are insulated from all consequences.

A director may face personal liability under applicable legislation for unremitted employee source deductions, including income tax withholdings, Canada Pension Plan contributions and Employment Insurance premiums. Directors may also face liability under GST/HST legislation in some circumstances. These claims have statutory conditions, time limits and potential due-diligence defences. The Canada Revenue Agency explains director liability in its information on directors’ liability. Get advice promptly if remittances are behind; delay can make it harder to understand the record and options.

A personal guarantee is different. It is a promise by an individual to pay a corporate debt if the company does not. A corporate bankruptcy in Canada does not by itself erase that promise. The guarantee’s wording, amount, security and the lender’s actions need to be reviewed by legal counsel.

If company shares become worthless, shareholders should also speak with a tax professional. A capital loss or allowable business investment loss may be available only if the relevant tax-law requirements are met. A bankruptcy filing alone does not automatically establish a deductible loss.

A business director reviewing payroll remittance records and tax documents with an insolvency professional in anticipation of a corporate bankruptcy in Canada filing

If you are a director or shareholder who has guaranteed debt or may face statutory liability, assess your personal finances separately. Personal bankruptcy or a consumer proposal is not automatic after corporate bankruptcy in Canada; it may be considered if personal debts cannot be managed. An LIT can explain the options in light of your own situation.

What alternatives are worth exploring before filing?

If the business may be viable, I recommend testing practical options quickly, not just hoping that cash flow improves. Depending on the facts, the following may be lifelines:

  1. Control cash flow. Prepare a short-term cash forecast, prioritize essential operating costs and identify spending that can be reduced without damaging revenue.
  2. Explore refinancing. New or restructured financing may help, but review its cost, security, guarantees and repayment capacity before committing.
  3. Consider shareholder funding. Additional capital or a shareholder loan may buy time, but it should be documented and assessed against the company’s full debt position.
  4. Negotiate an informal workout. Some creditors may accept revised payments or terms. The company needs to know which creditors must agree and what happens if one does not.
  5. Sell surplus assets. A sale can raise cash, but check ownership, security interests, tax consequences and whether the asset is essential to operations.

If the company is not viable, a secured lender may appoint a receiver under its security or seek a court-appointed receiver. Receivership is not the same as bankruptcy: a receiver generally takes control of specified property of the business for the secured creditor’s purposes, while a bankruptcy trustee administers the bankrupt corporation’s estate under the BIA for the benefit of the unsecured creditors. A receiver may continue operations temporarily to preserve sale value, but this is not a promise that the business will be rescued. The company’s security documents and circumstances determine the scope.

What should I do in the first 30 days?

The right timetable depends on the urgency. If enforcement, payroll or tax remittances are pressing, do not wait 30 days to seek advice. Start here:

  1. Gather the records: recent financial statements, bank statements, aged receivables and payables, tax filings, payroll records, leases, loan agreements and security documents.
  2. List all creditors and guarantees: identify amounts, arrears, collateral, court actions and any personal guarantees.
  3. Reconcile CRA accounts: separate source deductions, GST/HST, corporate income tax and other balances. Do not treat them as interchangeable.
  4. Build a realistic cash-flow forecast: show expected receipts and essential payments over the coming weeks, using realistic assumptions.
  5. Avoid unusual asset transfers or selective payments without advice: transactions made while insolvent may raise legal issues or be challenged.
  6. Speak with an LIT and, where needed, a business lawyer or accountant: ask what can be done immediately, which options are realistic and what each could mean for the company, directors, employees and creditors.

The point is not to create more paperwork. It is to replace uncertainty with a practical sequence of decisions.

What are common frequently asked questions (FAQ) about corporate insolvency?

Question 1 – How can a company come out of corporate bankruptcy in Canada?

Bankruptcy is generally a liquidation process, not a route for a corporation to receive a personal discharge and resume free of its debts. A business seeking to continue should consider a Division I Proposal or CCAA restructuring, if eligible and viable.

Question 2 – Do directors go bankrupt when the company does?

No. The corporation and its directors are separate legal persons. Directors may still have personal exposure under guarantees or specific statutes, but a personal insolvency filing is a separate decision.

Question 3 – What is the difference between bankruptcy and receivership?

A trustee administers a bankrupt company’s estate under the BIA, acting on behalf of the unsecured creditors. A receiver typically acts under a secured creditor’s rights or a court order over specified property or operations. The authority and purpose differ.

Question 4 – Can shareholders recover anything?

Possibly, but only if there is value left after secured claims, statutory priorities and all other creditor claims are satisfied. In a corporate bankruptcy in Canada liquidation, shareholders normally receive nothing.

Question 5 – How long does corporate bankruptcy in Canada take?

There is no single standard timeline. The duration depends on the assets, claims, disputes, tax matters, litigation and required steps to complete the administration.

Question 6 – What happens to employees?

A corporate bankruptcy in Canada automatically terminates the employment of the people by the company as employer. If the trustee continues operations in bankruptcy, a separate arrangement is established by the trustee to protect the trustee while paying the workers. Employees may have wage and other claims, and some eligible unpaid wages may be considered under the federal Wage Earner Protection Program. The facts and deadlines matter.

Can the company keep operating through a proposal?
Often, a company continues operating while pursuing a proposal, but it must manage its ongoing obligations and comply with the process. A proposal is not a guarantee that operations can continue indefinitely.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future, call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case.

About the Author:
Ira Smith is President of Ira Smith Trustee & Receiver Inc., a CPA CA and Licensed Insolvency Trustee.

A GTA business owner reviewing company books and a creditor letter alone at a desk after hours and considering corporate bankruptcy in Canada

#CorporateBankruptcy #BusinessInsolvency #DivisionIProposal #CCAA #CreditorPriority #DirectorLiability #CorporateBankruptcyInCanada #CorporateRestructuring #StartingOverStartingNow
Categories
Brandon Blog Post

ENTREPRENEURIAL CANADIAN BUSINESS BANKRUPTCIES: THE TIP OF A HUGE ICEBERG?

Insolvency for business including business bankruptcies

In the last two Brandon’s Blogs, I wrote about personal bankruptcy. The topic was the class of debts not released by a person’s discharge from personal bankruptcy. In this Brandon’s Blog, I discuss insolvency for business, and specifically, business bankruptcies, as a result of the recent report by the Canadian Federation of Independent Business (CFIB).

If a business is incapable to pay its financial obligations as they come due, it might deal with some negative effects, including legal action. However, this does not have to damage a business’s credibility forever, if management is prepared to take the required corrective activity before it is far too late.

If a business that is unable to pay its debts cannot turn itself around, it may be forced to declare business bankruptcies, which can have a devastating impact on the business and its employees.

What will happen to the company if it is insolvent?

If your company is financially troubled, it may need to assign itself into bankruptcy. Nonetheless, business bankruptcies are not always the automatic result of being insolvent. If your business is experiencing financial problems, it is essential to speak to a bankruptcy lawyer or a licensed insolvency trustee to review all of your realistic choices. Bankruptcy should be the last choice when nothing else will work.

Case in point, the recent report issued by the CFIB on small business insolvency says that its survey finds that only 10% of business owners would certainly declare bankruptcy if they were to shut down completely.

The CFIB report is meant to give a more comprehensive view of Canadian business insolvencies (bankruptcies + proposals). The data indicates that the number of businesses filing for bankruptcy has been on the rise and is now at the highest level of business insolvencies in two years.

As we recover from the COVID-19 pandemic, Canadian small businesses face a number of challenges in returning to normal operations, including debt from necessary pivots, increased costs of doing business and trouble finding employees to work.

The CFIB study found that half of the businesses (54%) are still seeing below-normal revenues, and over 60% are carrying unpaid debt from the pandemic. Small businesses are under significant financial pressure, with little room to maneuver.

Insolvency fears among Canadian small businesses are alarmingly high, and the true scope of the problem may be even greater than what is reflected in official statistics. Business owners have a range of options available to them when faced with financial difficulties, and bankruptcy is only one of these.

The CFIB recently released report details the different ways the surveyed small businesses in Canada said they would take if they had to shut down as follows:

  • 46% – Just ceasing all operations permanently.
  • 27% – Selling or transferring ownership to another party.
  • 10% – Filing for business bankruptcies or business bankruptcy protection.
  • 10% – Unsure at this time.
  • 7% – Exploring all options.

Interestingly enough, recapitalizing the legal entity or taking on more business debt by way of loans was not one of the answers. That should tell you how tapped-out Canadian small business shareholders are and that the businesses have no borrowing base room left on their assets to increase their bank borrowings.

business bankruptcies

Business bankruptcies: The insolvency of a business – First steps

The first step for the Directors is to consult with a business bankruptcy attorney/lawyer and a licensed insolvency trustee (formerly called a bankruptcy trustee) (sometimes referred to as “Trustee”). The lawyer can confidentially discuss the situation with the Directors and develop a proposed plan to deal with the situation.

The licensed insolvency trustee will review the company’s financial position and proposed game plan, and consider all options available to the company and its Directors. In Canada, the only party licensed to run the administration of bankruptcy, or any formal insolvency process, is a licensed insolvency trustee.

The licensed insolvency trustee will want to understand fully the company’s assets and liabilities. With a clear understanding of the company’s financial status, the Trustee can explain how best to implement the plan to either restructure or liquidate the company. If necessary, the Trustee can tweak the game plan.

The next question is whether the business is viable. Does it produce goods or services that are still in demand in the marketplace? If not, one option to consider is selling the business to another company that has complementary lines of business. Would the business fit in neatly with the buyer’s existing operations?

Could it perhaps be integrated in some way that would make your standalone business, which is not currently viable, become viable? Keep in mind for this to be an option, the company would need to have a solvent business.

If you can’t sell your unprofitable but still solvent company, you could always explore the option of a statutory liquidation. This would involve liquidating all the company assets, paying off any outstanding liabilities, and then distributing the remaining amount to shareholders.

Companies under business bankruptcy protection

If your business is struggling financially but still has potential, you may be able to restructure it through business bankruptcy protection. In Canada, there are two main possible federal statutes to restructure under; (i) the Bankruptcy and Insolvency Act (Canada); and (ii) the Companies’ Creditors Arrangement Act. One of these restructuring legal proceedings is an alternative to business bankruptcies.

A proposal under the Bankruptcy and Insolvency Act (Canada) (“BIA”)

The BIA is the canadian bankruptcy legislation containing all the rules and regulations in Canada’s bankruptcy regime. However, it also includes bankruptcy options such as a Division I Proposal for debtors who owe more than $250,000. This kind of financial restructuring allows the company to remain in business while it restructures. The essence of a BIA Proposal restructuring is that the company is offering a contract to its unsecured creditors to pay less than the total it owes those unsecured creditors in return for eliminating all of its unsecured debt.

To ensure that the company can successfully implement a proposal and pay its post-filing debts, the licensed insolvency trustee will need to be satisfied that all relevant information has been obtained and that the company has a good chance of success. The company’s cash flow will need to be monitored to ensure that it is sufficient to run the business and pay for the goods and services it needs going forward.

The Trustee will send all known creditors a copy of the proposal, a portion of the company’s statement of affairs listing the company’s assets and liabilities, a list of creditors, a proof of claim form, a voting letter and the Trustee’s report providing additional information and the Trustee’s recommendation.

The meeting of creditors is then held and if the proposal is accepted by the required majority of unsecured creditors, the licensed insolvency trustee takes the proposal documentation to Court for approval. If the proposal is accepted by creditors and approved by the court, the company is now bound by the proposal.

If the companies successfully complete their financial restructuring proposal, they will avoid business bankruptcies. However, if the company fails to get creditor or court approval, or fails to successfully complete the proposal, it will automatically go into bankruptcy under the BIA.

Financial restructuring under a Companies’ Creditors Arrangement Act (“CCAA”) plan of arrangement

Restructuring through a CCAA plan of arrangement is a financial restructuring process that provides companies with a way to restructure their debts and other obligations. This process can help companies to avoid the business bankruptcy process and to continue operating while they repay their creditors. It is very similar to a BIA proposal. The main difference is that it is only for companies with debts of $5 million or more, it is much more court-time intensive and there is no automatic business bankruptcy provision. In a CCAA, the licensed insolvency trustee acts as a monitor under the CCAA to administer the restructuring process.

When you hear when a company files for protection, or bankruptcy protection, in Canada it is usually under the CCAA. In the United States, it is under Chapter 11 of the US Bankruptcy Code.

business bankruptcies

Licensed insolvency trustees say if companies are insolvent and not viable the best option may be business bankruptcies

We still want to know if the business is viable when it is insolvent. If it is viable, then we could look at doing a restructuring as outlined above. After the company is restructured, we could either keep running it or look to sell it. If there are impediments to a successful restructuring, the approach we take even through business bankruptcies will be different than if it is not a viable business model any longer.

If the business is not viable and insolvent, then there is not much that can be done. The business is financially unhealthy and the marketplace no longer wants the product or service this business provides. Therefore, we are looking at bankruptcy if there is not a secured creditor who is going to enforce their security through a receivership. Receivership is a whole topic unto itself which is for a different day.

As a licensed insolvency trustee, I am responsible for understanding all the issues in business bankruptcies and preparing the necessary documentation for limited companies to assign themselves to business bankruptcies. A meeting of directors must be called for them to resolve that the company should put its business into bankruptcy and appoint one of the directors to be the designated officer.

The officer designated by the board should be the director with the most intimate knowledge of the company’s affairs. This officer will sign the bankruptcy documentation and be the company’s representative at the first meeting of creditors.

The Trustee attends the director’s meeting and prepares the meeting minutes, or the minutes will be prepared by the directors and provided to the Trustee. Then, the licensed insolvency trustee prepares the bankruptcy documents which include the statement of affairs, which is the listing of assets and liabilities, names addresses and amounts owing to each creditor. The designated officer then attests to the truthfulness of the information and signs it all.

The companies are insolvent and have to go into business bankruptcies

The Trustee files the necessary documentation with the Superintendent of Bankruptcy, who issues a certificate of bankruptcy and appoints the Trustee. That’s when a company is officially entered into the bankruptcy process and the bankruptcy proceedings begin. This is the process of a company filing an assignment into bankruptcy.

So in a commercial bankruptcy administration, the Trustee has several responsibilities. The Trustee has to deal with the assets. The Trustee has to first determine are the assets subject to the security of a lender. Is that lender’s security good and valid?

business bankruptcies

What happens when the certificate is issued for business bankruptcies?

If every one of the assets is covered by a lender’s valid security which makes the security cover the assets in priority to the rights of a Trustee, then the bankruptcy trustee would not take steps to handle the company’s secured assets unless the secured lender particularly requests the Trustee to do so separately either as Receiver or Agent of the secured lender.

So let’s simply take the case where in bankrupting the company, the Trustee is handling the assets either due to the fact that they’re not secured or because the secured financial institution wants the Trustee to handle the secured assets within the bankruptcy (which is not normal, but not unheard of either).

The Trustee needs to make certain that the corporate assets are safeguarded, that they’re appropriately insured and that the Trustee has carried out an inventory of those assets.

The Trustee then needs to figure out how is it going to offer those business assets for sale. The Trustee must do a risk-reward analysis to see if it makes good sense for the Trustee to run the business. If so, is the Trustee looking for a sale of assets as a going-concern business sale or just shut down the business and liquidate the assets once the reasons for running the business have been met?

If it doesn’t make sense for the Trustee to run the business, the Trustee will close it down and take a look at the alternatives available. The assets can be sold by public auction, private sale or by tender sale separating the assets up into blocs. If the assets are such that they would attract a retail audience where consumers would pay more than if it was sold in lots to wholesalers, then a retail sale would be the way to go. The nature of the assets will identify what sort of sale of assets the Trustee runs.

Business bankruptcies: How will I know what’s going on?

The Trustee alerts all of the company’s creditors listed in the sworn statement of affairs of the bankruptcy in a mailing. The Trustee includes a proof of claim form so that all creditors can file their claim. The Trustee examines the claims and holds the first meeting of creditors.

After the first meeting, a meeting of inspectors is held. Inspectors are creditor representatives who assist the Trustee in providing approval for the Trustee’s recommendations and actions it wishes to take. This includes any approval of asset sales the Trustee recommends after making an informed decision. Inspectors also need to approve the Trustee’s Final Statement of Receipts and Disbursements near the end of the administration of all business bankruptcies.

business bankruptcies

Finding a Licensed Insolvency Trustee

I hope you enjoyed this Brandon’s Blog on business bankruptcies. Are you or your company in need of financial restructuring? Are you or your company unable to survive the COVID pandemic and its aftermath? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or the person who has too much personal debt. You are worried because you are facing significant financial challenges.

It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding bankruptcy. We can get you debt relief freedom.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. We know that we can help you the way we take the load off of your shoulders and devise a debt settlement plan.

We realize that people and businesses in financial difficulty need practical advice and a workable solution in an easy-to-understand financial plan. The Ira Smith Team knows that not everyone has to file for bankruptcy in Canada. Most of our clients never do, as we are familiar with alternatives to bankruptcy. We assist many people in finding the relief they need.

Call or email us. We can tailor a new debt restructuring procedure specifically for you, based on your unique economic situation and needs. If any of this sounds familiar to you and you’re serious about finding a solution, let us know.

Call us now for a no-cost initial consultation.

If you would like our free e-Book, “Closing A Business Without Going Bankrupt” CLICK THE PICTURE BELOW

business bankruptcies
Call a Trustee Now!