Categories
Brandon Blog Post

DEBT CONSOLIDATION: DEBT CONSOLIDATION LOAN MAY START PLAYING HARD TO GET


Debt consolidation

Debt consolidation is a form of debt refinancing that entails taking out one loan to pay off many others. This commonly refers to a personal finance process

Introduction

On November 16, 2018, the Canadian Association of Insolvency and Restructuring Professionals (CAIRP) issued a press release on the state of consumer insolvencies in Canada. Hidden in the information was data which leads me to believe that debt consolidation may be tougher in 2019 and certainly in 2020.

A perfect storm is brewing

A historically low rate of interest and accessibility to credit have enabled some Canadians to stay up to date with debt and debt payments that would otherwise have gone into default. Interest rates are now rising and it is expected that the Bank of Canada will continue to raise its benchmark rate into 2019. Canadian household debt is on average at its highest level ever and is forecast to continue to rise. Rising household debt combined with rising interest rates is not a good combination.

Until now, Canadian real estate values have continued to rise, so consumers have been able to combine unsecured credit card and other debt into new mortgage or home equity line of credit debt secured by Canadian real estate. However, times have changed. Effective January 1, 2018, a new mortgage stress test came into effect. We described it in our blog “CANADA MORTGAGE STRESS TEST: WE EXPOSE THE SECRET TO TURN YOU FROM ZERO TO HERO”.

The mortgage stress test has resulted in one of its prime goals; a noticeable downturn in new mortgage loans. The second result is a slowing down of the runaway real estate markets in Vancouver and Toronto. If Canadian household debt continues to rise, interest rates keep rising making debt payments tougher and Canadians can no longer combine their unsecured debts by taking out a new loan by borrowing against their homes, debt defaults are going to rise.

That is why I say that debt consolidation loans may start playing hard to get.

The important relationships to consider

Below is a chart displayed in the CAIRP press release which I have reproduced here.debt consolidation 3
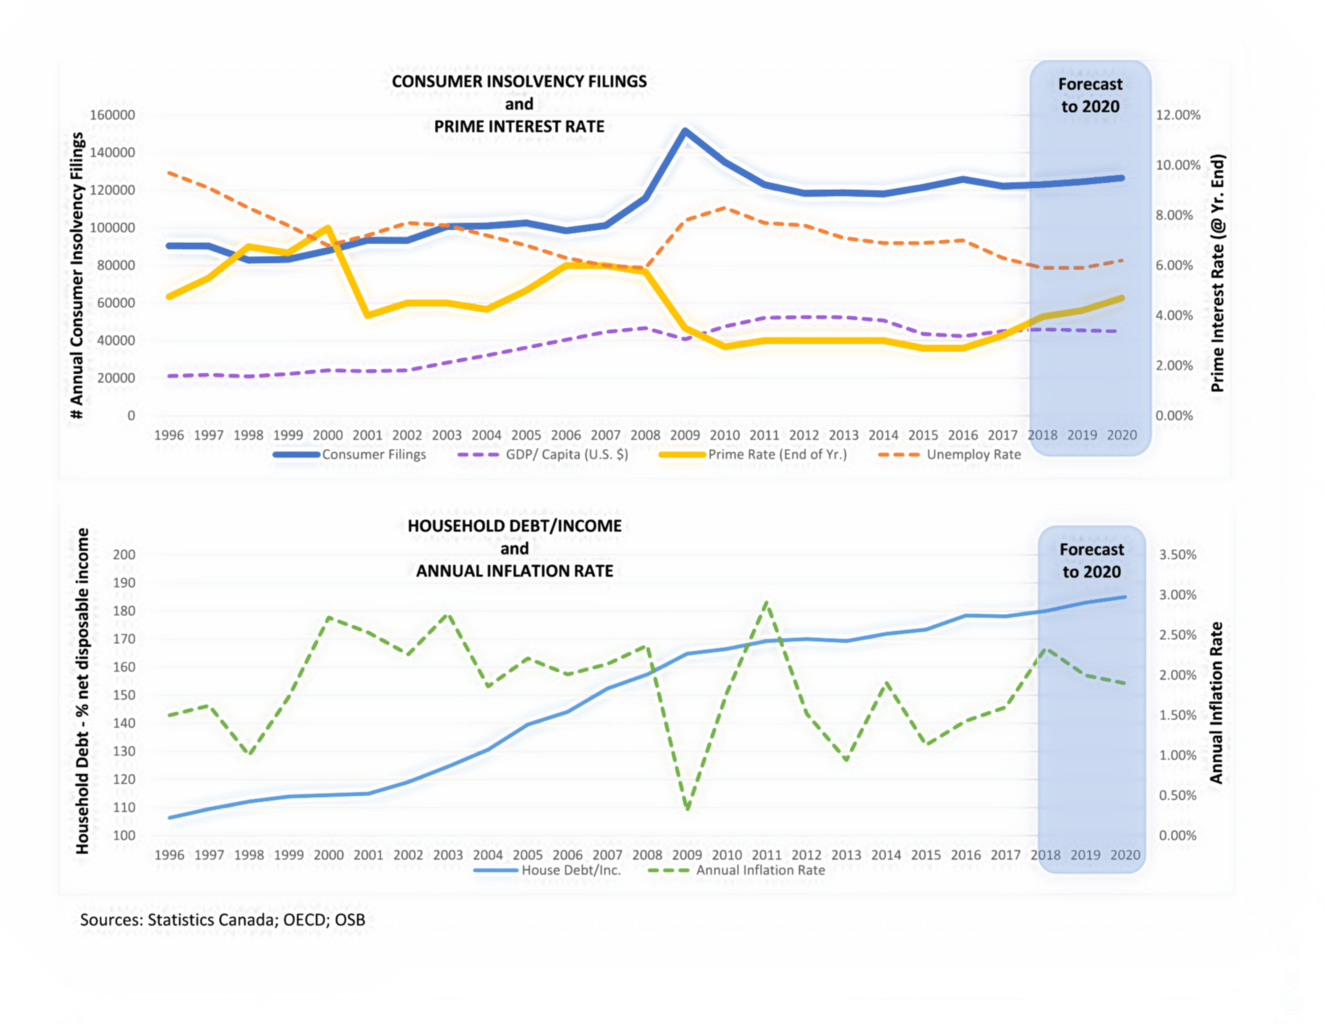
 

CAIRP came to some interesting conclusions about interest rates and consumer insolvencies, based on the trends shown in these charts. However, I believe they overlooked what I think is the central issue.

In the top chart, it shows that insolvency filings increased in the 2009-2010 years. CAIRP surmised that there was a lag between the time interest rates rose in the years 2006 through 2008 and the increased filings. This is true. However, the increase in filings mirrors the increase in unemployment in the 2009-2010 period. My personal view is that the more important finding is that the unemployment rate lagged the interest rate increase and it is the increase in the unemployment rate that produced a higher level of insolvencies.

With higher interest rates, corporations are paying more on their debt. Corporations want to show a steady increase in their profits year over year. If debt costs rise, companies have to find other costs to save. One cost that can be reduced in the short-term is labour costs. The forecast shows that as employees are terminated, the unemployment rate rises. Not everyone can find new work in the same time frame. This leads to increased consumer insolvency filings. In my view, the unemployment rate is a more important relationship to consumer insolvency filings.

Looking at 2019 and 2020

The bottom chart shows the relationship between household debt to income and the inflation rate. As you can see, the household debt to income ratio has kept a steady climb in 1996 through 2017 years. This steady climb has continued in 2018 and is forecast to rise even more in 2019 and 2020. The forecast also shows that inflation will nudge up to the 3% rate in 2020. So prices are expected to rise with inflation, and the household debt to income ratio is expected to rise also. This will put more pressure on Canadians trying to keep up with their debt payments.

The upper chart shows us that in 2019-2020, the forecast is that GDP stays flat, while interest rates continue to rise. In the same time frame, the downward trend in the unemployment rate bottoms out and begins to rise. Again, more unemployment and higher interest rates lead to problems for people trying to pay off debts. If you agree with my hypothesis that Canadians won’t be able to merge debt by borrowing more against their homes, this will lead to more financial problems and presumably an increase in consumer insolvency filings.

What you can do now

All is not doom and gloom. There are many things a person with a lot of debt can do now before things get out of control. There are many things that you can do right now to avoid a disaster down the road. My 5 steps for anyone who wants to resolve debt issues now are:

  1. Review your household budget now and cut spending on “wants” vs. “needs”. If you don’t have a household budget, develop a realistic one NOW!
  2. Rework the budget so that you spend less each month than you are currently spending. Look for ways to economize. Use that extra cash to paying down debt.
  3. Start paying more than the minimum monthly payment on your credit card and other unsecured debt. The more you can pay, the faster you can pay it off.
  4. Pay down the debt with the highest interest rate first. The less you pay in interest the better. That means more is going to pay down the principal debt.
  5. Perhaps you need to consider taking on a part-time extra gig to bring in more income.ira smith trustee

What if I can’t pay off my debts?

For Canadians that discover themselves not able to handle their debt on their own, there is a range of alternatives to take into consideration:

  • striking a deal with each of your major unsecured creditors through an informal debt settlement negotiation;
  • don’t give up on trying to combine all unsecured financial debts into one regular monthly payment;
  • a more formal debt settlement strategy with a consumer proposal; or
  • bankruptcy.

Identifying which choice is most appropriate depends upon a person’s scenarios as well as their unique asset and liability structure.

Debt consolidation: How we can help you

Licensed Insolvency Trustees (formerly called bankruptcy trustees) are the only experts accredited, licensed and supervised by the federal government to handle debt restructuring. As a licensed insolvency trustee, our personalized strategy will assist you to recognize all of your alternatives. The alternative you pick based on our recommendations will take away the stress and pain you are feeling because of your debt problems.

The Ira Smith Team has decades and generations of experience people and companies in financial trouble. Whether it is a consumer proposal debt settlement plan, a larger personal or corporate restructuring proposal debt settlement plan, or as a last resort, bankruptcy, we have the experience.

Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our front door. You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life. Call us today for your free consultation.
debt consolidation

Categories
Brandon Blog Post

SMALL BUSINESS CANADA TAX: LIBERALS UNFAIRLY TARGET SMALL BUSINESS TAXES IN CANADA RULES

small business canada taxFull disclosure: Ira Smith Trustee & Receiver Inc. is a licensed insolvency trustee firm in Vaughan (Toronto) Ontario. It is not an income tax advisory firm and does not provide income tax services. The information contained here is merely my opinion on SMALL BUSINESS CANADA TAX issues. This blog must not be relied upon for income tax advice or replace the advice of your income tax professional.

We are trying something new. At the bottom is an audiogram of this Brandon’s blog. If you would prefer to listen to it, and not read it, scroll down to the bottom and press on the play button. Let us know what you think by sending us a message in the Question box below.

Small business Canada tax: Introduction

In December 2017, our Federal Minister of Finance, Bill Morneau, disclosed some new policies he and Prime Minister Justin Trudeau were thinking about. The changes Finance Minister Morneau was touting, were for toughening up the small business Canada tax scheme. It would have affected entrepreneur’s businesses, their taxes, and their households.

The main aspect of small business Canada tax that our federal government wanted to attack was the age-old concept of family business income splitting. Its more modern name that you would have seen a lot in the press is called income sprinkling. The federal government was trying to advance the theory that small business owners whose family members were shareholders in the business, but not necessarily working in the business, were somehow cheating on their taxes.

Small business Canada tax: The Federal Government’s discussion points

The discussion focussed mainly on professionals, such as doctors, lawyers, and accountants who had a professional corporation. The government was trying to advance the argument how unfair it was for a professional earning say $250,000 annually, to “sprinkle” some of the income among family members older than 18 as compared to a salaried employee earning the same total amount in salary. I find it interesting that they used a quarter of a million dollars annually as an example, and not a lesser number. Do you think that was picked on purpose to subtly portray all family business owners as being fat cats?

The government’s position was that income that might have been paid to only the manager of the business, could be redirected to other family members by way of dividends. If those family members were in a lower-income tax bracket, then they would pay less tax. The government felt that was unfair.

Small business Canada tax: How income splitting or income sprinkling works

First, in order for this to work for a professional, the laws of the Province you live in has to allow you to have household members that aren’t professionals be shareholders of your professional firm. Second, if your spouse has a high taxable income already, then you will not profit by including him or her as an owner of the business. Lastly, you must decide if you’re going to add your children more than 18 years of age, as shareholders.

Assuming you’ve marked off all those issues, it can make a difference to your family’s overall income tax bill to add your partner and/or your grown-up kids as shareholders of your business. By doing this, you can choose to distribute dividends from the business and take advantage of their lower-income tax bracket.

Paying your partner or kids a salary is not as effective as making them shareholders of the firm and paying dividends. If you pay a salary, it needs to be a sensible one, for work that you can actually prove to the Canada Revenue Agency (CRA). In other words, you cannot simply pay your partner $100,000 for doing bookkeeping for the firm. CRA will certainly allow an affordable wage for that function, but it would have to be justified by comparison to the marketplace for such services.

The advantage of paying dividends to family members is that you do not need to prove it. The other benefit of paying dividends is that your firm recovers some of the business tax you’ve paid on dividends made by the firm’s financial investment portfolio. Refundable Dividend Tax on Hand (RDTOH) is the issue. Our firm does not do tax work. This is a complex topic, I will leave it up to you to research how RDTOH works.

Small business Canada tax: Tax changes effective January 1, 2018

Beginning January 1, 2018, the government changed the rules specifically to target professionals who have incorporated (specifically, doctors, lawyers, and accountants). Professionals who are gaining from reduced tax rates on what would have otherwise been fully taxed earnings at the highest marginal personal income tax rates, if not for their company.

The government is saying that these incorporate professionals aren’t adding their fair share to Canadian society by their decision to have a professional corporation. For that reason, they should not gain from the tax advantages of doing so.

So what are the changes? The Tax on Split Income (TOSI) rules has been amended to cover grown-up shareholders of private firms. Previously, TOSI rules only applied to minor children. The issue now becomes: If you’re a private company owner and pay dividends to adult family member shareholders, when can you do so without invoking the new regulations? Essentially, you need to be able to show much involvement in business.

Small business Canada tax: Clear bright line

The Federal government is putting what they’re calling a “clear bright-line”’ to exclude some relatives from the TOSI rules. The general TOSI exclusions are:

  1. The company owner’s spouse, providing they more than 65 years old.
  2. Children over 18 years old who have made a real labour contribution to the business. CRA is gauging this as an average of 20 hours a week during the year. Alternatively, there is also a test throughout any of the 5 earlier years.

The government has taken direct aim at professional corporations though. These exclusions do not apply where 90% + of the income of the corporation comes from the provision of services. Income from ownership of related businesses that earn income from the provision of services is also included in the calculation.

Inserting a trust into the ownership equation may get around this “excluded shares” provision. You need the advice of your income tax advisor to decide if it would be beneficial to you.

Small business Canada tax: Ottawa punishing small business Canada

When the federal government presented new tax rules, local business claimed they were being unjustly targeted by “punishing” measures. According to Small Business Association Canada, up to fifty percent of the country’s entrepreneurs state they’re feeling negative results.

The federal government also added changes to the passive income rules for private corporations. In the February 2018 Federal Budget, the Liberals added a grind-down mechanism for the small business tax deduction through which every dollar of investment income over $50,000 cuts profits eligible for the small business tax deduction by $5.

This has been especially challenging for organizations that use passive earnings to help in special capital funding. For example, paying for building and construction equipment or to acquire real estate used by the business.ira smith trustee

Small business Canada tax: The greatest tax battle in decades isn’t over

The Canadian Federation of Independent Business (CFIB) has asked the Provinces not to follow the Federal Liberals but to support small business.

For small businesses, the greatest tax battle in decades isn’t over. Private corporations who use responsible budgeting techniques and save up their profits and invest them to earn income, to be prepared for a rainy day, are being attacked. They may be saving to smooth out cash flow problems, or they might have a big upcoming purchase. Now they are being attacked through the income tax system for earning investment income in excess of $50K annually. It is clear that CRA will be looking closely at professional corporations’ income tax returns. I would not be surprised to see more CRA audits performed. The Federal government is looking to extract more income tax revenue from private corporations.

The rules are increasingly complex. Entrepreneurs will be spending more time dealing with more punitive income tax rules and income tax audits. All of this is designed by Ottawa for private corporations to pay more income tax. It ignores the investments small business makes. Creating jobs and making capital investments allows small business to contribute in many ways to the Canadian economy. This is aside from paying income tax.

Small business Canada tax: Does your company have too much debt?

Is your company under attack because of tax obligations or for other reasons. Is your company in need of restructuring to get debt relief?

The Ira Smith Team has decades and generations of experience people and companies in financial trouble. If your company is in need of a corporate restructuring proposal debt settlement plan, we have the experience to end your stress and pain and return you and your company to a healthy productive pain-free condition.

Our approach for each case is to develop a solution where Starting Over, Starting Now happens. This starts the moment you meet with us. You’re simply one call away from taking the necessary actions to return to leading a healthy and well-balanced problem-free life. Call us today for your free appointment.

Full disclosure: Ira Smith Trustee & Receiver Inc. is a licensed insolvency trustee firm in Vaughan (Toronto) Ontario. It is not an income tax advisory firm and does not provide income tax services. The information contained here is merely my opinion. This blog should not be relied upon for income tax advice or replace the advice of your income tax professional.

Categories
Brandon Blog Post

BANKRUPTCY TRUSTEE NEAR ME IS NOW A LICENSED INSOLVENCY TRUSTEE NEAR ME

Bankruptcy trustee near me: Introduction

This Brandon’s Blog is about picking a licensed insolvency trustee. As the title suggests, performing an online search for bankruptcy trustee “near me”, based solely on geography, is one way. Being around the corner is certainly convenient, but it may have no place in making a life-altering decision. This isn’t a coffee place you are looking for. If you required life-saving surgery, would you base your decision only upon which surgeon operates out of the hospital closest to your home? I don’t think so.

Bankruptcy trustee near me: Don’t fall into the debt consultant/debt settlement company trap

I am talking about people who actually hold a license issued by the Canadian Superintendent of Bankruptcy to administer the insolvency system in Canada. I am not talking about debt consultants or others who claim to be able to help you avoid bankruptcy and end debt.

There is no government licensing or supervision of debt consultants. They merely charge you for a first intake consultation, that a bankruptcy trustee would do for free. Once they have your information, you have paid them for the visit, and perhaps they have signed you up for more expensive “credit score improvement tools”, they hand you over to the licensed insolvency trustee who now will perform the actual work.

Using this type of arrangement costs you more money than you need to spend. The money you can’t afford to pay! The Superintendent of Bankruptcy is putting new controls in place over licensed insolvency trustees to stop bankruptcy trustees from allowing debt consultants to associate shoddy practices and perhaps even profit based on their relationships with licensed insolvency trustees.

Bankruptcy trustee near me: There are different types

I am not referring to good or bad when I say there are different types of bankruptcy trustees. I am talking about the type of practice they run. Generally, there are 4 groups; bankruptcy trustees who run:

  1. Only a personal bankruptcy practice out of one site;
  2. A corporate bankruptcy firm out of one or a few strategically placed locations around the greater metropolitan area of your city;
  3. Both a corporate and personal bankruptcy practice out of one or a limited number of locations; or
  4. The personal bankruptcy practice being operated out of many locations following a coffee or fast food restaurant model of being near every street corner.

So obviously you first need to recognize whether your financial issues are those for your company, you personally or both. As I said at the beginning, geography is nice, but it is not the most important criteria. One simple reason is that multi-location bankruptcy trustees do not make every office of theirs a full-time office. In contrast, you will see that they are operating out of either office for daily rent locations, a lawyer’s or accountant’s office, or the worst, a debt consultant’s office.

You cannot stretch yourself too thin over many offices. So, more often than not, even if your first free consultation is with a member of the Trustee’s staff, you may be meeting with an experienced clerk, but not the actual bankruptcy trustee.

My 5 point checklist to find a licensed insolvency trustee

  1. Quality and professionalism.

    Someone around the corner from you may not have the experience you need to solve your financial problems. To begin in selecting the very best bankruptcy trustee for you, look at the Canadian Association of Insolvency and Restructuring Professionals (CAIRP) website. Membership in this professional organization shows a Trustee committed to the industry and staying on top of all the current advancements. Also check the website of the Office of the Superintendent of Bankruptcy, to make sure the bankruptcy trustees you are thinking about are not under suspension or supervision by the regulator.

  2. You need to be able to interact with them on lots of levels.

    In the beginning, you’ll need them to be able to quickly comprehend your needs and desires and they need to offer you a realistic plan that you can follow through on. They also need to be available for you if you have issues or concerns show up. Search for their interest. Are they enthusiastic about their industry? Do you really feel the compassion they have for you? Can you form a bond with this person? This is exactly how you assess enthusiasm. An enthusiastic licensed insolvency trustee will make certain that you are offered the most effective suggestions and solutions. This type of person may not exist within walking distance of your home or workplace.

  3. Can you agree on the same concepts?

    Professional Trustees are not totally free. The price can differ based on how complicated your circumstance is. If you feel that the bankruptcy trustee is simply attempting to make money, you are less likely to trust them. Spend the time to discover those who seem to be on the same page as you for a realistic value for service. That type of licensed insolvency trustee may not be the closest drive from your home.

  4. Bankruptcy trustee websites.

    Today you can type in search terms like “bankruptcy trustee near me” and get various websites to go to. What sort of feel do you get from the website? Do they answer some of your more general questions through a bankruptcy FAQ page? Can you see pictures of people you would deal with? Do they show that they have a deep knowledge base from their blog page? You may not get the best feeling from the website of the licensed insolvency trustee whose place is closest to your home.

  5. Meet with several Trustees.

    You won’t know which one is the best fit for you until you are sitting across the table from him or her. Speak to at least two bankruptcy trustees to compare. The one you feel best about, may or may not be on the next street corner!

Bankruptcy trustee near me: The choice is up to you

Our best relationships are with our clients who were referred to us by someone they know, like or trust. If the referral source is trusted by you, we have already received the highest compliment possible. I am proud to say that we have helped family members of lawyers and accountants who know us. They felt safest referring a loved one to us. That is the best feeling in the world for everyone!

The Ira Smith Team has decades and generations of experience people and companies in financial trouble. Whether it is a consumer proposal debt settlement plan or a larger personal or corporate restructuring proposal debt settlement plan, we have the experience.

Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our front door. You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life. Call us today for your free consultation.bankruptcy trustee near me

Categories
Brandon Blog Post

407 ETR RATES: THE ONLY GUARANTEED TO WORK 407 ETR DEBT SETTLEMENT PLAN

407 etr rates

We are trying something new. At the bottom is an audiogram of this 407 etr rates Brandon’s blog. If you would prefer to listen to it, and not read it, scroll down to the bottom and press on the play button. Let us know what you think by sending us a message in the Question box below.

407 etr rates: Introduction

The purpose of this 407 etr rates is not to tell you what the new toll rates are. The simple answer is that they are always going up! Rather, it is an update to our earlier blogs for people who are having trouble paying their 407 toll payment.

As you probably know, the 407 etr has an arrangement with the Province of Ontario where if you have unpaid 407 etr charges, you will be put on plate denial the next time you have to renew your vehicle plate. For many, being denied a plate renewal means the end of your ability to earn an income.

Before the update, a bit of history to put everything into perspective for you.

407 etr rates: Our prior blogs

We previously wrote about how the 407 etr was trying to use the provincial law as a collection tool, even when a person filed for a debt settlement restructuring consumer proposal or for personal bankruptcy. Our prior blogs were:

I won’t repeat the history here as you can check those blogs yourself. Suffice to say they argued in Court, unsuccessfully, that the Province had the right to enforce its own plate issuance rules.

The lower Court and the Court of Appeal for Ontario disagreed with their right to enforce the plate issuance rules when it was a blatant action to collect an ordinary unsecured debt caught in the priority scheme of the Bankruptcy and Insolvency Act (R.S.C., 1985, c. B-3) (BIA). The Courts also found that they were trying to trump Federal law through Provincial law, which is illegal. Finally, the Supreme Court of Canada refused to hear their appeal, so that is where it ended, sort of.

407 etr rates: So that is where it ended, sort of

With those rulings, the 407 etr stated that they would comply and drafted a policy which was an extremely literal wording of the BIA. It technically complied with the Court rulings, but still had the effect of being very draconian and not changing their administrative policy.

The debts of an insolvent person, who has made a debt restructuring consumer proposal or bankruptcy filing, are not discharged until the insolvency process is complete. For a debt settlement plan, it is when the person finishes making their payments and receives their Certificate of Full Performance. In a bankruptcy, it is when they receive their absolute discharge.

How those processes work deserves their own blogs. Suffice to say the processes can take anywhere from a minimum of 9 months (first-time bankruptcy, no surplus income, no assets and no discharge opposition) up to 5 years (debt settlement plan). So the plate denial actually stayed in force for a long time.

The 407 etr also set up a very document intensive 407 etr login process that made applying for the eventual rescission of the plate denial very cumbersome.

407 etr rates: The class action lawsuit

The firm that independently runs Highway 407 ETR in the Greater Toronto Area agreed to pay $8 million to clear up this claim. The settlement, approved in November 2016, finishes the litigation that began in 2012.

The lawsuit affirmed that the toll freeway consortium unlawfully used provincial regulations to stop motorists that were insolvent or bankrupt from restoring their automobile permit plates. 407 ETR refutes it did anything incorrect and does not confess obligation in approving the out of court negotiation.

407 etr rates: Now for the update – The only 407 etr debt settlement plan guaranteed to actually work

The licensed insolvency administrator (LIT) acting as either the bankruptcy Trustee or consumer proposal Administrator, acting as either the bankruptcy Trustee or consumer proposal Administrator, will issue the Notice of Bankruptcy or Consumer Proposal. 407 ETR must be listed on your sworn Statement of Affairs as a creditor. It will then be sent a copy of the notice by the LIT.

Upon receipt, 407 ETR will end from plate rejection any amounts still owing from before the date of filing either for bankruptcy or a consumer proposal. This includes toll charges, interest, penalties and costs. They will then advise the Ministry of Transportation to upgrade their documents to show this change ending plate denial. This is a major change. You do not have to have completed your full insolvency process to get the lifting of the plate denial. This is the way fairness dictates it always should have been from the start.

There is a simple rule that you have to follow. It is the same rule that you need to follow in dealing with any leases or secured debt that you wish to continue to carry and that you can afford to. That is, you must not have any amounts owing to 407 etr for charges after your filing date which would qualify for plate denial.

407 etr rates: Are you worried about or need relief from plate denial

  1. Are you under plate denial, or afraid you will be soon?
  2. Will plate denial negatively affect your income and you need debt relief fast?
  3. Do you have other debts that need to be addressed too?
  4. Do you need budgeting help?
  5. Are you already experiencing financial difficulties?

If you answered yes to just one of these questions, you need a professional trustee. If yes, call the Ira Smith Team. Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our front door.

We always offer a free consultation. We listen to your issues and give you a full range of realistic options to help you get out of debt. Finding the best solution for YOU is just the right thing to do to help you meet total debt freedom.

The earlier you contact us, the more options we will have to carry out. Whether it is a corporate restructuring or personal debt settlement through a consumer proposal, the goal is to avoid bankruptcy. However, if bankruptcy turns out to be the best option, we can assist there too.

You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life, ending the pain and stress you are feeling forever. Call Ira Smith Trustee & Receiver Inc. today for your free consultation.

Categories
Brandon Blog Post

CONSUMER PROPOSAL ONTARIO: AMAZING GOVERNMENT PLAN TO REDUCE CONSUMER DEBT


Consumer proposal Ontario: Introduction

I am finding that more people are calling me to ask about a consumer proposal Ontario. This is a Canadian federal government authorized program for people to lower their consumer debt.

What is triggering the boost in these queries?

Consumer proposal Ontario: New Ipsos Canadian consumer debt survey

A brand-new study by Ipsos might assist. It paints an unpleasant scene of just how much debt some Canadians are holding on to. Of those asked 31% claim they do not make an adequate amount to pay their costs monthly. More state they are having a hard time to merely to survive. Ontario residents in this predicament are candidates for consumer proposal Ontario.

The study discovers many people are sorry for the sort of spending they’ve done to find themselves with such debt. Peoples’ incomes aren’t maintaining pace with the increase in their costs. I am not just talking about extras; I am also talking about the basics of life such as food and shelter.

Consumer proposal Ontario: Bank of Canada benchmark interest rate hike

At the very same time, on October 24, 2018, Stephen Poloz, the Governor of the Bank of Canada (BOC) announced the Bank of Canada interest rate hike by a quarter-point to 1.75%. This increases the cost of borrowing for Canadians. This is the 5th bump since the summertime of 2017.

The Bank of Canada states that the Canadian economic situation remains running near capacity and is reasonably broad-based. The rising cost of living is close to target so what stands apart is that the current rate at 1.75% is still negative in actual terms adjusting for inflation.

Since the old Free Trade Agreement, the new USMCA appears to be resolved, several think with this 800-pound gorilla out of the room, it’s most likely to unlock the Bank of Canada’s ability to continue with rate hikes.

Consumer proposal Ontario: How will higher interest rates affect you?

If you stay in a variable price home mortgage or credit line, your rate of interest has risen. What that indicates for your capital is that your month-to-month repayment has actually risen. If your home mortgage is half a million bucks, your month-to-month repayment has actually increased by sixty-five dollars.

It does not feel like a great deal. Nevertheless, if your loan(s) rate of interest rises during the rest of the year and right into 2019, that will certainly maintain raising your repayments.

It isn’t simply your variable price home mortgage. Canadians additionally lug debt with credit lines, automobile financings as well as bank cards. Each rate of interest rise will certainly increase the price of borrowing on those variable price financings.

The raised repayments will certainly maintain consumption in your capital. So for those battling to make ends meet, rates of interest boosts will just make life harder. A consumer proposal Ontario won’t help with secured debt, but it will help eliminate unsecured debt

Consumer proposal Ontario: Higher interest costs lead to belt-tightening

To regulate debt, Canadians need to be aggressive with their budgeting. Individuals need to take ways to boost their monetary scenario, such as:

When talking to a LIT, ask about how a consumer proposal Ontario can help you.

Consumer proposal Ontario: Nonetheless, many Canadians are still seeking help

Many Canadians continue to be haunted by debt. They experience remorse towards their existing and future debt scenario. Fifty percent are not certain that they will not have any kind of debt in retired life, while 44% are not certain they will have the ability to cover all living expenditures in the next year, without taking on additional debt.

Some Canadians are thinking about bankruptcy. Their first step must be to go to a Trustee. A Trustee is an expert that is certified by the Office of the Superintendent of Bankruptcy Canada (OSB). The OSB is the government organization that controls the insolvency system in Canada.

Consumer proposal Ontario: A government-approved strategy to end consumer debt

To most of our potential clients’ shock, I have told many that bankruptcy might not be essential for them. Sometimes I suggest that it is possible to remove their debt via a government-approved strategy to decrease consumer debt called a consumer proposal Ontario.

Your government authorized debt settlement program is an offer made to your creditors. The offer is to repay only a percentage of what you owe, over a duration of no more than 5 years.ira smith trustee

Consumer proposal Ontario: The benefits to you

There are benefits for you to file such a debt settlement plan. First, you keep your assets. Next off, an approved proposal binds all creditors to the arrangement.

We begin with having the individual complete the standard intake form that we call, the Debt Relief Worksheet. When totally filled in, it gives us a listing of the individual’s assets as well as what they owe. It additionally aids them to budget their income and expenses. Utilizing that info, I am able to formulate a proposal based on your capacity to pay.

The proposal is submitted to the OSB. Once submitted, you can quit paying your unsecured creditors. If creditors are garnishing your income or suing you, those activities are stopped. As soon as the proper documents are submitted with the OSB, I then send out the proposal to every one of your creditors.

The creditors then have 45 days to approve or decline the deal. If creditors are unhappy with the proposal, as the Trustee I can work out changes such as greater payments. However, it all is based on what you can still manage to safely pay.

I tell people that if the proposal is turned down, the individual will certainly need to consider various other alternatives to resolve their monetary troubles. This might include bankruptcy.

Once we get approval, you are then in charge of making routine payments to the LIT as the proposal administrator. The LIT will certainly use that cash to pay your creditors.

As part of the consumer proposal process, you will need to go to 2 counseling sessions in the LIT’s office. This will aid you to get back on your feet monetarily. If you fully complete your plan, you will certainly be legitimately released from your unsecured financial obligations.

Consumer proposal Ontario: There are 2 consumer proposal FAQs everybody asks me

What this affect my credit score?

Yes, it will certainly be influenced, I tell every person. Once the regards to the proposal are fulfilled, people can begin reconstructing their credit history and their economic future.

Just how much does it cost?

The cost is established by the Federal government. How much an individual pays in for an effective consumer proposal is totally unrelated to the allowable government authorized to charge. The Trustee earns the fee from the amount you pay into your debt settlement restructuring plan. So, that means, the cost is FREE!

Consumer proposal Ontario: That freedom feeling

Our clients who complete their consumer proposal are so pleased to get that letter from us enclosing their Certificate of Full Performance. That is the document that confirms they have become debt-free.

The Ira Smith Team has years of experience of negotiating with creditors for debtors. If you owe less than $250,000, other than for any mortgages against your home, you can enter into a consumer proposal debt settlement plan. If you owe more or are a corporation, we can still negotiate with your creditors and restructure you with a restructuring proposal debt settlement plan.

Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our door. You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life, recover your money and move on to the next investment opportunity.

Call us today for your free consultation.consumer proposal ontario

Categories
Brandon Blog Post

ONTARIO PENSION PLAN: DOUG FORD GUARANTEES ONTARIO PENSION PLAN RELIEF FOR ALGOMA STEELWORKERS

ontario pension plan

We are trying something new. At the bottom is an audiogram of this Ontario pension plan Brandon’s blog. If you would prefer to listen to it, and not read it, scroll down to the bottom and press on the play button. Let us know what you think by sending us a message in the Question box below.

Ontario pension plan: Algoma Steel

Ontario’s Premier Doug Ford is promising his help for Ontario steelworkers as well as their Ontario pension plan following the United States’ federal government’s 25 percent tariff on Canadian steel.

In news recently to Algoma Steel Inc. staff members in Sault Ste. Marie, Ont., Ford claimed the provincial government would assist in passing revisions under the Ontario Pension Benefits Act, R.S.O. 1990, c. P.8, along with insurance coverage from the Pension Benefits Guarantee Fund, subject to particular conditions.

Premier Ford didn’t provide any additional information on what specifically the help might be. However, he stated that negotiations are happening and extra info about just how Ontario is sustaining Algoma will certainly be introduced as quickly as possible.

Ontario pension plan: United Steelworkers

At the same time, the United Steelworkers union is prompting the federal government to enact regulations that would safeguard pension plans as well as benefits in situations of company bankruptcy, reorganization or liquidation. Union participants will be meeting legislators to check regulations focused on changing the Companies’ Creditors Arrangement Act (R.S.C., 1985, c. C-36) (CCAA) and the Bankruptcy and Insolvency Act (R.S.C., 1985, c. B-3) (BIA).

Ontario pension plan: Proposed federal legislation to date

We previously described the efforts of Scott Duvall, MP for Hamilton MountainA, , MP for Manicouagan and Senator Art Eggleton:

Ontario pension plan: Canadian Association of Retired Persons

The Canadian Association of Retired Persons (CARP) is calling out the federal government, claiming it’s unreasonable that Sears Canada could pay out millions of dollars in shareholder dividends, a large part of which went to the US. At the same time, the pension plans of Sears Holding Corp.’s American staff members will be safeguarded by the U.S.’s Pension Benefit Guaranty Corp. while Canadian workers will certainly see benefits cuts.

“It’s time for the government to take decisive action to protect Canadian pensioners,” said Wanda Morris, chief advocacy and engagement officer at the CARP, in a press release.

Ontario pension plan: Private member’s Bill C-405

On October 17, 2018, Bill C-405 was presented by Conservative Erin O’Toole, MP for Durham. It is called “An Act to amend the Pension Benefits Standards Act, 1985 and the Companies’ Creditors Arrangement Act”.

The proposal is to change the Pension Benefits Standards Act, 1985 (R.S.C., 1985, c. 32 (2nd Supp.)), setting out what ought to take place if a business is under liquidation with the CCAA or Part III of the BIA.

His proposed changes lay out what should happen if a company is under liquidation through the CCAA or BIA. It proposes to allow, pending the permission of participants and beneficiaries, to transform the framework of the plan and/or move the pension’s assets to one more plans.

Granted this would probably be a necessary part of any global overhaul of pension plans. However, it is important to realize that it doesn’t do anything to safeguard the pensions or give the plan members and beneficiaries greater priority.

Ontario pension plan: Has a life event thrown you a curveball

Life has a way of throwing curve balls sometimes to good people. In the event of:

  • Illness;
  • addiction;
  • divorce;
  • family death; or
  • job loss

unbearable financial pressures can occur.

The Ira Smith Team has generations and decades of experience in dealing with people or their companies fighting the pain, stress and suffering that comes with financial problems and too much debt.

Our method for each person is to develop an outcome where Starting Over, Starting Now occurs. This begins the minute you come through our door. You’re just one call far from taking the essential actions to return to leading a healthy and balanced life, moving forward pain-free.

Call us today for your cost-free consultation.

Categories
Brandon Blog Post

CANADA BANKING INFO COLLECTION: YOUR EXPECTATIONS VS REALITY ACCORDING TO JUSTIN TRUDEAU

Canada banking info collection: Introduction

On October 29, 2018, the Hon. Candice Bergen (Portage– Lisgar, CPC), stood in Parliament during Question Period. She talked to troubling reports this previous weekend that Statistics Canada was taking part in Canada banking info collection without the consent of the people whose info was being asked for.

Statistics Canada notified financial institutions, charge card businesses as well as credit reporting companies that it anticipates them to turn over individual financial information of a minimum of half a million Canadians without their consent or authorization. Financial institutions will not be able to tell their customers about the government demand for their financial transactions.

The noticeable issue is, that with the lengthy history of federal government personal privacy violations, Canadians are appropriately stressed over both the collection as well as the security of their individual economic deals. Ms. Bergen needed to know why the Liberals are accumulating the individual information of Canada without telling them.

Canada banking info collection: PM Justin Trudeau reacts

Our PM reacted by stating that the federal government is ensuring that the individual information of Canadians is secured. Stats Canada will certainly make use of the anonymized information for analytical functions only. No details will be revealed.

He stated that he understands (which is a way of repeating rumours or hearsay, or worse, that he truly does not understand whatsoever) that Statistics Canada is proactively involved with the Privacy Commissioner’s office, to make sure Canadians’ financial details stays safeguarded and private. High-grade and prompt information is important to guaranteeing that federal government programs stay pertinent as well as efficient for Canadians.

Canada banking info collection: Ms. Bergen had not been pleased, and neither ought to we

Ms. Bergen responded that the Liberal federal government strategies to get access to the individual details of Canadians without their knowing about it or permission. This consists of details like payments, internet purchases, charge card purchases, cash withdrawals and e-transfers between members of a family.

She wants to know if the Prime Minister will do the right thing. Will he guarantee Canadians that this invasion into their lives will be stopped?

Canada banking info collection: PM Justin Trudeau reacts by attempting to fault the Conservatives

Our PM reacted by stating that Canadians appropriately expect that federal government agencies like Statistics Canada will collaborate with the Privacy Commissioner. He said that Stats Canada will make certain that Canadians’ exclusive lives are shielded. Good words up until we hear that CRA obtained accessibility to the info, or even worse, cyberpunks!

Then for the good part. PM Trudeau said to the House of Commons and all Canadians that it was the Conservative federal government that selected to end the long-form census as a method of protecting an individuals’ exclusive info. So our PM is saying that in some way our private financial transactions is a straight substitute for basic analytical demographics? I don’t think so.

PM Justin Trudeau after that doubled down by stating that the Conservatives’ assaults on information and privacy continue.

Canada banking info collection: Mr. Alain Rayes (Richmond– Arthabaska, CPC)

Mr. Alain Rayes also participated. He repeated that Canadians expect the federal government to secure their private details, yet the Liberals wish to gain access to private information on 500,000 Canadians without their approval. They intend to consider loan repayments, ATM withdrawals, credit card transactions, financial institution money transfers and social insurance numbers.

Exactly how can the Prime Minister warrant these activities, which are plainly an offence of Canadians’ personal privacy?

Canada banking info collection: Blah, blah, blah.

Prime Minister Trudeau responded with more of the same. He said again the government will constantly make sure (a warranty?) that the individual information of Canadians is safeguarded. He said that Stats Canada will make use of the anonymized information only for analytical goals. No details will be revealed (does analytical purposes only include analysis by Canada Revenue Agency?).

He repeated that Statistics Canada is proactively involved with the Privacy Commissioner’s workplace on this task and is dealing with it to make certain Canadians’ info continues to be secured and private.

My personal view is that the primary federal government program that would certainly most take advantage of understanding my private financial information is the income tax collection system in Canada!

Canada banking info collection: The law

The Personal Information Protection and Electronic Documents Act (S.C. 2000, c. 5) (PIPEDA), Canada’s federal private sector privacy legislation, was specifically amended on the issue of privacy. Schedule I of Section 5 of PIPEDA states that:

“4.3 Principle 3 – Consent
The knowledge and consent of the individual are required for the collection, use, or disclosure of personal information, except where inappropriate.” (emphasis added).

What is one of the exceptions?

4.3 Principle 3 – Consent
“Note: In certain circumstances personal information can be collected, used, or disclosed without the knowledge and consent of the individual. For example, legal, medical, or security reasons may make it impossible or impractical to seek consent. When information is being collected for the detection and prevention of fraud or for law enforcement, seeking the consent of the individual might defeat the purpose of collecting the information.”

So, looking at the exceptions, this only bolsters my hunch. I am convinced this is not only to evaluate the viability and effectiveness of existing social programs. Rather, it will be used to evaluate and amend the effectiveness of tax investigation programs. This will provide direct new information to the Canada Revenue Agency to bolster current and start new investigations. That is why the information is being collected without Canadians’ consent to invade their privacy.

Canada banking info collection: May I have this dance?

Justin Trudeau just kept dancing and blaming Conservatives. This new invasion of privacy really doesn’t have anything to do directly with insolvency. However, if I am correct in my guess, and the information is going to be used by CRA, then it may well.

People may very well have engaged in tax evasion. I, of course, do not condone it. Criminal charges aside, Canadians who evade taxes and get caught will now have a huge income tax bill to pay. Many won’t be able to.

There will be many high tax debtors who will not be able to afford a voluntary payment with CRA. Such a voluntary payment plan will need you to pay your original income tax debt. You will not get any reduction in all penalties and interest. So you will be paying in full to Her Majesty. For those who will not be able to afford such a voluntary payment plan, bankruptcy is definitely not your first option. You would have to look at a debt settlement restructuring proposal as a first choice. Bankruptcy should be your last option.

Canada banking info collection: What about you?

If you have received legal advice that you don’t really have a case, or you can’t afford to fight it out in Court or pay the income tax debt that renders you insolvent, then you need the help of a professional trustee.

The Ira Smith Team has years of experience of negotiating with CRA on behalf of tax debtors. If you are an individual person and owe CRA and your other creditors, other than for any loans secured by your home, less than $250,000, you can enter into a consumer proposal debt settlement plan. If you owe more or are a corporation, we can still negotiate with CRA and restructure you with a restructuring proposal debt settlement plan.

Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our door. You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life, recover your money and move on to the next investment opportunity.

In conclusion, call us today for your free consultation.canada banking info collection ira smith trustee

Categories
Brandon Blog Post

CANADIAN INTEREST RATE HIKE POSSIBLY SCARIER THAN HALLOWEEN

canadian interest rate hikeCanadian interest rate hike: Introduction

Does Bank of Canada chief Stephen Poloz anticipate good times generally in the Canadian economic climate to continue or is the marketplace an indicator of a problem in advance? The most recent Bank of Canada interest rate announcement was a Canadian interest rate hike boosting its benchmark rate by 25 basis points to 1.75%.

This is the 5th rise given since July 2017. All indicators show the Bank of Canada rate will boost right into 2019.

Canadian interest rate hike: The tale of two economies

There are presently 2 stories about the Canadian economy. The initial one is that the economic climate is doing well. Sufficiently so that we require to be increasing rates of interest. Mr. Poloz thinks there is a requirement to be tightening up that a bit.

At the exact same time, the second one, the other story, points to an economy that isn’t so great. The marketplace has recently made the case for pessimism. That story is that:

  • we’re at the actual end of a long great financial run;
  • a trade battle with China is the precursor of tough times ahead, and
  • investors are frightened that this can be the time that things start to turn down.

Canadian interest rate hike: What does it mean for you?

There’s a great deal of discussion regarding what that indicates specifically for Canadians. It isn’t that the cautions have not been there for a while. The Bank of Canada records that the typical Canadian household debt is around 170 percent of disposable earnings. The ordinary Canadian owes $1.70 for every single dollar of revenue earned each year, after tax.

Twenty years ago, the ratio was at 100%. So as you can see, there has been a steady climb since the 1990’s in Canadians appetite for more debt.

We have among the highest debt proportion of any of the Organisation for Economic Co-operation and Development participant nations. The concern is have we started to learn the message?

Initially, former Bank of Canada Governor Mark Carney and the former Federal Finance Minister, the late Jim Flaherty desired the Canadian consumer to place the economy on their back and march it up this lengthy high hillside. We did and it worked. Nonetheless, this is the result of it.

Currently, we start to see some indicators that the Canadian consumer is thinking of their budgeting. Stats Canada is reporting that retail sales have actually started to see a slowing down. Individuals are thinking of just how their variable priced loans are costing them more.

The sensible people will certainly begin restricting their purchases to just their needs and not give in to their wants. All this to attempt to maintain their debt in check. Rates of interest are rising so debt costs are going up and will set you back even more. Individuals will certainly concentrate on the requirement to bring costs as well as debt under control. This will lead to a cooling off in the Canadian economy.

Canadian interest rate hike: The US situation

I anticipate the very same practices will certainly happen in the United States. President Trump is already disturbed that the United States central banker Jay Powell is currently raising interest rates. However, Trump is disturbed that elevating rates will certainly tinker negatively with the US dollar. It could also slow down the US economy. If that happens, Donald Trump’s fears his worst nightmare. He won’t be able to truthfully boast how well the US economy is doing under his administration. There have been times already where he’s been plainly irritated the economy is refraining from doing what he wants of it. Mind you, to date, he has not let the truth get in the way of a good boast!

So climbing rates of interest will certainly have a result on the North American economic situation and the marketplaces. Whether interest rate hikes will be scarier than Halloween, only time will tell.

Canadian interest rate hike: Are you uneasy about your household debt?

Do you feel rising debt costs will put you and your family in peril? Do you need budgeting help? Are you already experiencing financial difficulties? If you answered yes to just one of these questions, you need a professional trustee. If yes, call the Ira Smith Team. Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our front door.

We always offer a free consultation. We listen to your issues and provide you with a full range of realistic options to help you get out of debt. There have been numerous times where thinking about all the Canadian debt solutions available, we have advised debtors that they do not need an insolvency process. Rather, maybe they can avoid it by implementing an informal process. If that is your case that if fine with us; finding the best solution for YOU is just the right thing to do to help you achieve total debt freedom.

The earlier you contact us, the more options we will have to implement. Whether it is a corporate restructuring or personal debt settlement through a consumer proposal, the goal is to avoid bankruptcy. However, if bankruptcy turns out to be the best option, we can assist there too.

You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life, ending the pain and stress you are feeling forever. Call Ira Smith Trustee & Receiver Inc. today for your free consultation.ira smith trustee

Categories
Brandon Blog Post

CANADIAN INSOLVENCY LAWS: ALIENATION OF ASSETS


Canadian insolvency laws: Introduction

In today’s commercial world, our economy focuses on and requires Canadian insolvency laws. Insolvency is the financial condition where you cannot pay your debts as they come due and if you liquidated all of your assets, there would not be enough cash to pay off all of your debts.

Insolvency laws are required in a mature economy. It reassures investors that there is a way to “recycle” assets. Asset recycling makes them once again valuable and revenue producing, should insolvency set in on a person or company.

Canadian insolvency laws: My goal with this blog

An insolvency process is used as a means of liquidating one’s whole legacy (i.e. the totality of one’s assets) in order to attempt to please all of the creditors that have grown way beyond the ability of the person or company to repay. Emotions always run high in insolvency procedures. We are dealing with the lives of real people that may be losing their jobs, income, homes and other assets.

The purpose of this vlog is not to teach you about insolvency laws. I want to caution anyone considering going into business how important it is to structure things properly. Your aim is to make sure that you are protecting yourself, your business and your family. If your business falters and becomes insolvent you will be glad that you did.

Canadian insolvency laws: Believe it or not, it may be good for you to meet a licensed insolvency trustee

So naturally, as a licensed insolvency trustee (formerly called a bankruptcy trustee) the first focus is on restructuring. Sometimes bad things happen to good people and companies. Bad judgement, bad luck and bad management all contribute to personal and corporate insolvency. Our primary focus is to use various ways to help people and companies recover from insolvency.

The potential ramifications of insolvency procedures can be minimized. A person can no longer afford to keep their assets. A company has too many problems to continue its business. However, those same assets can be used very successfully in a new business or by someone else. So insolvency laws and procedures help to avoid a total loss of asset values.

In many of our cases, this can involve particular minor legal procedures which could eventually conserve a fortune. For financial institutions, this can be especially good news.

Canadian insolvency laws: Why you need to “alienate” your assets


If you are running a company, or are likely to do so in your career, you must minimize your exposure by safeguarding your assets. By doing so, you are protecting yourself and your family for the future, especially if something in business goes wrong. The time to protect yourself is when you are starting out and there are no problems. If you do so when the problems have already arisen, it is too late. Any asset protection steps you take knowing yourself to be insolvent, will not stand up to attack.

By running a company, you will probably become a Director. If your business needs to borrow money from the Bank to operate, you will probably be required to guarantee the bank debt. So, if you anticipate yourself collecting considerable unsecured financial obligations in the coming years, you need to act. Starting out properly protecting yourself, allows you to either avoid or successfully defend, any challenges on the sequestration of your assets.

Canadian insolvency laws: Why you want to be an “alien”

You will make sure that the properties you have “alienated” no longer form part of your estate. The alienation ensures that the possessions from which you will still benefit cannot be gotten by your financial institutions if the business is unsuccessful and they are looking for any assets you may have to honour the financial obligations you accumulate.what does a court appointed receiver do

Canadian insolvency laws: Use your lawyer


When setting up a company, you need a lawyer. Make sure that you choose a lawyer that can also counsel you on how to protect your assets in the event your business venture fails. We are not lawyers, and the general advice I am going to give you is not meant to replace the advice of a lawyer.

Canadian insolvency laws: You may need more than one company to conduct your business

The first thing to think about is incorporating a limited liability company. Depending on the type of business, you may need to incorporate several, within which to house your operations, the leased or owned premises you operate out of and your shareholdings. Conducting your business through a company will require more documentation and therefore cost.

However, it is well worth it. It removes and protects you personally to the greatest extent possible from personal liability. The goal is to minimize or eliminate the destruction of you and your family. If you choose not to go through a corporate body, for whatever reason, protecting your personal assets becomes even more important. There will not be one or more corporate entities to serve as the first line of protection.

Canadian insolvency laws: Examples of multiple corporations in running a business

Examples of how multiple corporations will better insulate you and your business assets are:

Operating company. Your operating company is the one you conduct business through. It is the vehicle which will attract the most liability. There is always a risk in running any business. However, there is no law that requires you to hold all your business assets in your operating company.

Single purpose corporation. You may want to incorporate a second single purpose company to hold valuable assets used to conduct the business of your operating company. Tangible assets such as machinery and equipment are obvious. You are operating out of premises; either leased or owned.

You may wish to have a corporation that holds the tangible assets. Another company that is simply the real estate company. If you also have valuable intangible assets such as copyrights, licenses, trademarks, you may wish a separate company to hold all of the intangible assets.

These single-purpose corporations will then lease the assets to your operating company to conduct its business. Your operating company will pay rental charges, lease payments and licensing fees to the respective sole purpose companies. You need your lawyer to carefully document in writing everything. By now you can probably see the value in separating out the various important and valuable assets from your normal business operations.

Canadian insolvency laws: Alienating your most valuable asset

The most significant and most important property most of us will own is our house. The time to transfer your ownership interest to your partner ideally is before the first day of your going into business. Waiting until there are business problems and you are insolvent, any transfer will be successfully attacked. Obviously, you have to believe that you and your partner have a solid loving relationship before making the transfer as you will no longer have your ownership interest in the house.

Canadian insolvency laws: Does your company have too much debt?

To set up your company and structure your affairs properly, we urge you to use the best lawyer for your needs. This blog cannot replace the advice of your lawyer. However, if your company is experiencing financial difficulties, you need a professional trustee. If yes, call the Ira Smith Team. Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our front door.

The earlier you contact us, the more options we will have to implement. Whether it is a corporate restructuring or personal debt settlement through a consumer proposal, the goal is to avoid bankruptcy. However, if bankruptcy turns out to be the best option, we can assist there too.

You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life, ending the pain and stress you are feeling forever. Call Ira Smith Trustee & Receiver Inc. today for your free consultation.canadian insolvency laws 1

Categories
Brandon Blog Post

CORPORATE BANKRUPTCY IN CANADA: SADLY IN E-COMMERCE TAXLAND

corporate bankruptcy in canadaCorporate bankruptcy in Canada: Introduction

A brand-new report from PwC Canada discloses that in 2018, Canadians anticipate spending an average of $1,563, up 6.7% over last year. Men are expected outspend women by almost $400. That got me to start thinking about what the most complex issue for corporate bankruptcy in Canada is when an online business fails?

The report finds that the majority of Canadians still prefer the in-store experience. Nearly two-thirds consider brick-and-mortar retail for their primary holiday season shopping. The rest is online shopping. Unsurprisingly, most millennials (51%) think of online purchasing first, which is in line with United States consumers overall (50%).

E-commerce, like any other industry, has its startups and more mature companies. There will be winners and losers. The fulfilment of online digital products is done online. The fulfilment of physical goods orders bought online more often than not will be done by a third party. That third party may not necessarily be fulfilling orders from Canada.

Corporate bankruptcy in Canada: The most complex issue for an e-commerce business, IMO

With that said, the retail vendor’s inventory, computer hardware and software value are relatively easy to determine. But to my way of thinking, the #1 issue for corporate online vendors, both solvent and viable or insolvent and not viable, is the area of sales tax.

In attempting to abide by tax laws for your e-business, you might find yourself falling down the rabbit-hole, going through the looking glass, and attending a Mad Tea-Party.

Sound judgment, logic, and fairness never did apply totally to the field of taxation, however, this is specifically true of e-commerce deals.

Corporate bankruptcy in Canada: Canada Customs Welcomes You to Canada!

Considering that I’m situated in Canada, let’s start here. To keep things simpler, but certainly not simple, I will review this issue strictly from a Federal tax collection perspective, i.e. Harmonized Sales Tax (HST).

Canada has what you may call a nationwide sales tax or a value included tax (VAT). This Goods and Services Tax (GST) of seven percent is applicable to lots of Canadian transactions.

Not just is it critical to identify whether a taxable sale was made in Canada or not, but also where in Canada. If it was made (or deemed to be made) in any of the HST provinces, a higher rate applies. This is due to the fact that those provinces have allowed Canada to gather their provincial sales taxes for them, as follows:


ProvinceHST % rate
New Brunswick15
Newfoundland and Labrador15
Nova Scotia15
Ontario13
Prince Edward Island15


Each province and territory has its own guidelines. Ontario charges 8 percent retail sales tax on numerous common internet deals whereas Alberta has no provincial sales tax.

Obviously, this is just scratching the surface. This entire blog by necessity is an oversimplification of an extremely complicated topic. As a licensed insolvency trustee (formerly called a bankruptcy trustee), I would certainly require the advice of a professional tax advisor to help me through e-commerce Taxland.

Since I am not a tax professional, you should also seek the advice of a tax professional. This is merely one bankruptcy trustee’s view of the issues in the insolvency of an e-commerce business.what does a court appointed receiver doCorporate bankruptcy in Canada: When Exports Aren’t Exports!

In Canada, exports are “zero-rated” sales for GST purposes. This means that when you ship a product to someone outside Canada, you don’t charge GST. Yet, you get to claim (or subtract from the GST collected by you) all the “input tax credits” (GST that you spent for business functions) to make that export.

However, if you export items aside from physical products, beware! There are lots of mistakes to look out for.

As one example, think about digitized products that you may offer from Canadian sites, such as e-books, downloadable software application, or subscriptions to a material. You would be considered to be selling “intangible personal property”. Unless your item is also thought about “copyright” (such as software or e-books that you produced or have gotten the rights for), you will need to charge GST. The reason, according to the Canada Revenue Agency, is that it could be utilized inside Canada, even if it isn’t.

Say you sold a subscription for accessing digitized content (from various sources) on your Canadian site to a client in the United States. Given that there are no restrictions regarding where the intangible personal property might be used, and the property is not considered copyright (nor the provision of a service), the American client goes through GST, even if he never comes to Canada.

Strangely, the same logic doesn’t apply when an American buys a routine book (or an automobile) which he could bring into Canada with him and utilize here. It holds true that it is much easier for Canada to assess such products at the border than in the online world. However, I have not heard of any cases of Americans being taxed on the cars and trucks or books they bring with them when they come to reside in Canada for a part of the year.

As a Canadian registrant, one way you might legally avoid this ridiculous March Hare is to clearly mention on your website and invoice that utilize of such intangible personal effects in Canada is restricted (or requires an extra charge and the payment of GST).

Corporate bankruptcy in Canada: When imports Aren’t imports

Goods shipped to Canada are subject to GST on importation. Such tax is often assessed at the border. What if you are a Canadian registered for GST, selling to a Canadian customer but your provider is in a foreign country?

Pretend that your Canadian consumer has bought a book from you from your Canadian website. Your dropship supplier is located in the United States and is signed up for GST. You send your order to the American business, and they, in turn, ship the book for you (total with Customs Declaration and their GST Business Number).

Since they paid the GST, you wouldn’t think you would need to charge it again, would you? “Wrong!”, smiles the Cheshire cat. Since you are a registrant located in Canada, you need to charge and remit the GST. But you are entitled to input tax credits, aren’t you? In many cases, the answer is “No”.

It might be very tough for you to satisfy the documentary and other technical requirements. As an example, it is not uncommon for American providers to absolutely refuse to provide an invoice breaking down the GST or to enable you to be the importer of record. This complicates their life unnecessarily and they just don’t require the aggravation.

There are easing tax provisions covering drop shipping, sales agencies, and other situations. In most cases, sadly, the most practical option is to permit the tax to be paid twice.

Corporate bankruptcy in Canada: When you are subject to tax where you’re not subject to tax

It makes sense that countries impose a tax on sales and earnings made in their own jurisdiction. Does it make sense for Germany to tax sales made in the United States?

Starting July 1, 2003, the European Union actually did just that by enforcing an online sales tax.

This implies that if somebody from England buys an e-book from somebody in the United States, the American should submit this tax. Naturally, If the sale was to someone in Germany, the tax rate would be more complicated.

The reasoning behind this is as follows: Since countries can’t gather sales tax on internet deals at their borders, the only method they can collect it (other than a self-assessment system) is with an online sales tax. Even more, it is claimed that companies in the European Union suffer a significant competitive disadvantage due to the fact that they need to gather Value Added Tax but others don’t.

Corporate bankruptcy in Canada: But that isn’t all


So that is just a “scratching of the surface” description of the issue for Canadian companies selling online when it comes to HST. But if the company is insolvent, and will go into either receivership or bankruptcy, the story gets worse.

For every insolvent company in receivership, an HST liability is a trust claim against the assets of the company. So in a liquidation, the HST liability would have to be paid before a secured creditor, normally a chartered bank, recovers any money. What this means for the owner(s) who guaranteed the bank debt, is that they have additional exposure for any shortfall of the bank debt by the amount of the HST liability.

In a bankruptcy though, the HST liability is not a trust claim, but rather an unsecured claim. So, the good news is that it does not come ahead of the bank debt the owners have probably guaranteed payment for. However, the bad news is that the HST liability is always a Director liability. So in a bankruptcy, there are always insufficient funds to pay off the unsecured creditors 100%. So, the Directors of the bankrupt company will be on the hook for any unremitted HST.

Corporate bankruptcy in Canada: Does your company have too much debt?

Is your company, either a traditional retailer, online retailer or both, experiencing financial difficulties? If yes, call the Ira Smith Team. Our approach for each file is to create an end result where Starting Over, Starting Now takes place. This starts the minute you are at our front door.

The earlier you contact us, the more options we will have to implement. Whether it is a corporate restructuring or personal debt settlement through a consumer proposal, the goal is to avoid bankruptcy. However, if bankruptcy turns out to be the best option, we can assist there too.

You’re simply one phone call away from taking the necessary steps to get back to leading a healthy, balanced hassle-free life, ending the pain and stress you are feeling forever. Call Ira Smith Trustee & Receiver Inc. today for your free consultation.

Call a Trustee Now!