Categories
Brandon Blog Post

BUSINESS DEBT ADVICE CANADA: TROUBLE SHOOTING DEBT STRAPPED COMPANIES

business debt advice canada

2


Business debt advice Canada: Introduction

When it involves money, timing is everything. Your business is getting closer to the top of its banking line and your banker is asking for more information than usual. This is where your heart starts pounding faster and your stress level increases. This is the moment you can seize to right size your business or else it very well may fail. The purpose of my blog is to give you business debt advice Canada.

Business debt advice Canada: Relationships can become strained

Relationships can become strained with your lender and suppliers when business debts are mounting and your company is facing a cash crisis. However, there are actions a borrower can take to prevent calamity. Reassuringly, most of the time, lenders would rather support you if you have a viable business plan to correct the situation going forward, and not putting you out of business.

I hope the suggestions below shows you that you should look at this as an opportunity to fix your business. I have found that in trying times when a company has mounting debts and insufficient cash, there is no replacement for good management.

A solid business plan showing how the company will turn itself around is what your lender wants to see. Communication with your lender and your suppliers is key. Do not hide from the problem. Face it head on. If your business plan shows you can turn things around, you will feel like you are dealing from a sound platform and not just running scared.

Business debt advice Canada: Take emotion out of the equation

These situations generally become more tense before they become better. You, your lender and your unpaid suppliers all want the same thing. You all want the company to be successful and profitable, and to be able to pay all of its bills in full when due. Your lender and suppliers are not out to get you. However, if they do not: (i) know that you have solid business turnaround plan; and (ii) receive ongoing information to show what steps you are taking to fix the problems, they will have no choice but to turn off the tap.

I have unfortunately seen too many companies fail in their business restructuring efforts due to lack of communication. The turnaround plan may have been sound, but nobody knew. This only creates ill will among the stakeholders and a result that nobody wants.

Business debt advice Canada: Informal and formal turnaround options

I must preface this section by saying do not be afraid to consult with a licensed insolvency trustee (LIT) for business debt advisory services. Trustees’ training makes them expert in assessing troubled business situations and implementing turnaround steps. A LIT does a lot more than just bankruptcy.

You will find it helpful to have a professional trustee assist you in developing your turnaround business plan, implementing it and keeping management focussed and accountable. You will also find it very helpful to have a LIT go with you for meetings with your banker; there will be many of those!

Business debt advice Canada: Troubleshooting

Fully understanding the full current status of the company showing signs of financial trouble is key. Things that I focus on early on when looking at troubled companies are:

  • What are all the different assets of the company and where are they located?
  • Are all the assets properly insured?
  • What is the going-concern value and the estimated liquidation value of the assets?
  • What is the full extent of all liabilities and business debt levels? This includes amounts owing to the government for:
  • What is the status of premises lease(s) for both remaining term and cost?
  • Is the cost of the leased premises above or below current market value?
  • Has anyone personally guaranteed bank debt, the landlord or any other creditor that would affect turnaround decisions to be taken?
  • Has a current crisis cash-flow statement and turnaround business plan been developed and tested for reasonableness?
  • What are the causes of the company’s current financial problems and how likely are those causes to recur?

This list is not meant to be exhaustive. No doubt other questions will arise as answers are found for these first questions. However, this is the information I first want to get before embarking on developing a restructuring plan.

Business debt advice Canada: Informal restructuring and turnaround

If the business problems have been identified early and have not been allowed to fester, then an informal restructuring may very well work. Perhaps all that will be needed is some accommodation from the lender both in time and money. Banks are quite willing to enter into a forbearance agreement with their corporate client allowing the time (and sometimes more money) to see if the turnaround plan will work.

The bank would rather have a successful turnaround than shut you down. The bank needs to know that management has the bench strength to pull off the restructuring. If not, they will expect you to have a lawyer experienced in turnarounds and a LIT active on your team.

Companies that have relatively few trade suppliers may also be able to work out a restructuring of their unsecured debt. The fewer people you have to talk to and get onside, the higher the likelihood of success. Of course, the trust developed from earlier dealings is very important. If there is no trust, or if there are just too many suppliers, an informal restructuring will not work with them.

Business debt advice Canada: Formal restructuring

The Bankruptcy and Insolvency Act (R.S.C., 1985, c. B-3) (BIA) and the Companies’ Creditors Arrangement Act (R.S.C., 1985, c. C-36) (CCAA) are the two primary Federal statutes that govern corporate restructuring in Canada. The requirements of each statute and the exact processes themselves are weighty enough to deserve their own blog. However, the takeaways from this blog on formal restructuring are:

  • In a formal restructuring, I still go through the checklist I have identified above of issues to look into.
  • Under the BIA, the restructuring section is Part I Division III of the BIA
  • If a restructuring under the BIA does not receive the necessary creditor AND court approval, the company will automatically be bankrupt
  • In a formal restructuring, the company stays in control of its assets and business operations
  • A formal restructuring invokes a stay of proceedings so no party can begin or continue litigation or enforcement action against the company
  • A company needs to have at least $5 million in debt to restructure under the CCAA
  • A BIA restructuring will be less costly than a CCAA restructuring because the company does not have to go to Court for approval every time it wishes to do something
  • The term “bankruptcy protection” in Canada, refers to a formal restructuring under either the BIA or CCAA.

Business debt advice Canada: What to do if your company has too much debt

Is your business facing financial problems? Perhaps your company is in need of a restructuring. The Ira Smith Team can develop a restructuring plan which may or may not include the need to file for bankruptcy protection.

The Ira Smith Trustee & Receiver Inc. Team understands the pain you are going through trying to keep your company alive while trying to negotiate with potential purchasers. We understand that you are playing beat the clock, and the pain and stress you are feeling thinking that you may just run out of time. The bankruptcy protection process can ease this stress and provide a level playing field so that no potential purchaser takes advantage of you.

The Ira Smith Team has a great deal of experience in running a stalking horse stalking horse asset purchase agreement. The stress placed upon you due to your company’s financial challenges is enormous. We understand your pain points. Call the Ira Smith Team today for your free consultation. We can end your pain and put your company back on a healthy profitable path, Starting Over, Starting Now.
Categories
Brandon Blog Post

INTEREST ON CREDIT CARDS CALCULATOR: WHAT A LOSS OF YOUR INCOME MEANS

interest on credit cards calculator

Interest on credit cards calculator: Introduction

As Benjamin Franklin so wisely stated in 1789, in this world nothing can be said to be certain, except death and taxes. Life is full of surprises – not all of them pleasant. Are you financially prepared in the event that life deals you a low blow – job loss, injury or a health crisis? And, if so, would you turn to credit cards to support your lifestyle? Do you really know how to calculate the interest on your credit card balances? Below I will explain how an interest on credit cards calculator works.

Interest on credit cards calculator: And the survey says

According to a recent survey by Forum Research:

A Manulife Bank survey of Canadian homeowners reports that:

  • 9% have access to $1,000 or less
  • 14% have not put away any funds

Interest on credit cards calculator: An alarming Canadian trend

These two surveys bring to light an alarming trend. With no emergency fund, or any savings to fall back on, many Canadians who find themselves in a crisis with a sudden loss of income turn to living off credit cards. According to Bankruptcy Canada:

  • Only 25% of Canadians pay off their credit card debt in full each month which means that 75% of Canadians carry a balance on our credit cards each month
  • This can result in paying several thousands of dollars each year in interest

Interest on credit cards calculator: How the interest is calculated

The annual interest rate on credit cards ranges from 19% to almost 30%. Credit card companies actually calculate interest on a daily basis. Therefore, if you do not pay the full balance on time by the due date, the interest actually compounds on a daily basis. That is why once balances are overdue, or you are only making the minimum monthly payments, you can never get catch up. The daily compound interest accrues too quickly.

The Financial Consumer Agency of Canada provides a free online credit card payment calculator. Check it out by clicking here.

Interest on credit cards calculator: What to do if you can’t keep up with your credit card payments

In fact, it can take a lifetime to pay off a credit card balance of a few thousand dollars if you’re only making the minimum payments. Living off credit cards is not the answer; getting professional help is. You need a trustee now. Many people fear that bankruptcy is the only option for serious financial problems, but that’s just not true. Although bankruptcy is an option, there are bankruptcy alternatives to consider:

Ira Smith Trustee & Receiver Inc. is here to help. We approach every file with the attitude that your financial problems can be solved given immediate action and the right plan. Give us a call today and Starting Over, Starting Now you can put your financial problems behind you and look forward to living a debt free life.


Categories
Brandon Blog Post

AFTER BANKRUPTCY DISCHARGE CANADA: LIVE WELL AFTER A BANKRUPTCY DISCHARGE

after bankruptcy discharge canada

2

After bankruptcy discharge Canada: Introduction

The purpose of my blog is to provide ideas and suggestions on how a person can fulfill one of the aims of the Canadian insolvency system. That is to carry out successful financial rehabilitation and live profitably and happily after bankruptcy discharge Canada.

After bankruptcy discharge Canada: You are not alone

In 2017, 122,198 Canadians went for either bankruptcy or a restructuring proposal. The split was roughly even. These people and their families underwent significant financial and emotional pain. In January and February 2018 together, 19,082 Canadians went for either bankruptcy or a restructuring proposal. The split favoured restructuring proposals slightly.

After bankruptcy discharge Canada: Your financial slate is now clean

Your financial slate is wiped clean. However, your credit score has taken a beating. Now is the time to not squander the opportunity you have for financial rehabilitation. Notation of your bankruptcy stays on your credit report for 7 years after your bankruptcy discharge. In the case of a restructuring proposal, the notation remains on your credit report for 3 years after successful completion of your financial restructuring.

After bankruptcy discharge Canada: My 10 step program to live profitably after a bankruptcy discharge

So how can a discharged bankrupt hop on a rapid course to a bankruptcy rebound? Here are my suggestions:

  1. Use your bankruptcy experience to improve your financial education. Take a course on practical money management.
  2. You won’t have any credit cards so you have to rely more on cash. Use an envelope system so that every payday you segregate your cash into envelopes, each marked with an essential family expense. Make sure the cash is used only for those essential purposes and no cheating. No borrowing from the envelopes!
  3. Points 1 and 2 above lead naturally into the next point. Sit down with the entire family and work out a monthly budget. Your total expenses cannot be more than your total income, after income tax, for the month. If everyone is involved in setting it up, then they will all understand if you just can’t afford something in a certain month. Also, they will all be helping you stay on budget.
  4. You do need to find a way to start rebuilding credit. Obtain a secured credit card. Not the drug store variety, but the kind issued by a real credit card company. You have to deposit funds with the credit card issuer and then you get a credit limit equal to the funds deposited. Use that credit card each month, but pay off the FULL balance each month. The credit card company then reports to the credit reporting agencies that you are using credit wisely. Over time, this will improve your credit score.
  5. Always remember the behaviours that got you into financial trouble in the first place and don’t repeat them. If it was an event outside of your control like job loss or a medical emergency, it was not your behaviour that was the cause of your financial problems.
  6. Establish SMART goals. Specific, Measurable, Achievable, Realistic and Timely goals. Setting and reaching your goals will certainly make you an economic success.
  7. Begin building up savings. You need to be financially prepared for a life emergency. As a bare minimum, begin setting up a reserve so that you can withstand a 6 to 9 month emergency that increases your expenses or reduces your income.
  8. Start investing in an RRSP using an RRSP loan. Take out a small RRSP loan. Use your tax savings to pay it down, and work into your budget repaying the rest of the loan, with interest, during the year. Do the same thing the following years. Not only will you build up RRSP savings, the reported loan repayments will improve your credit rating because you are using credit wisely again.
  9. Purchase based only on your needs that are in your budget; never on your “wants”.
  10. Do not purchase anything on impulse. Research, research and research to make sure that you are getting the best deal possible.

After bankruptcy discharge Canada: The takeaway

The takeaway? It is not easy to recover after bankruptcy discharge Canada. It is a series of small steps using modified behaviour and healthy money management skills. But it is possible. I have seen many of my past clients do it. There is not a magic pill you can take. It is a matter of concentrating and working on moving on and learning from your past mistakes. Working at it one day at a time, you will regain your self-respect and feeling of self-worth by restoring your financial and credit report health and wellness.

After bankruptcy discharge Canada: What if you have too much debt?

I hope that you have found this information helpful. Bankruptcy is the last thing we try to do for a person in financial difficulty. If caught early enough, we can get involved in a debt settlement restructuring program for you.

The Ira Smith Team knows that you are worried because you are facing significant financial challenges. The stress placed upon you is enormous. We understand your pain points.

Contact the Ira Smith Team today. We know how to solve your financial challenges, remove your pain and put things back on a healthy path. Contact us today for your free consultation so that we can save your life, Starting Over Starting Now.

Categories
Brandon Blog Post

MONEY MANAGEMENT MISTAKES: AVOID MONEY MISTAKES – MISTAKES COST MONEY

money management mistakes

Money management mistakes: introduction

No matter how much money you have, you can still get into financial trouble by making money management mistakes. Just follow the news and on a regular basis you’ll hear about a celebrity who you thought was worth millions and is now filing for bankruptcy. We have also all heard about retired athletes money errors.

Money management mistakes: Good income means nothing

It’s not enough to make a good wage; it’s what you do with it that matters. I recently read a story of a woman who worked as a secretary her whole life and passed away leaving a multi-million dollar estate.

Money management mistakes: 5 money mistakes to avoid

Here are 5 financial mistakes that can really hurt your future:

  1. Live on your money; not on credit: It’s so easy to make purchases that you can’t afford when you use plastic instead of money. It’s really important that you don’t spend what you don’t have.
  2. Make a budget and stick to it: Everyone should have a budget. It’s the only way you’ll really understand how much money is coming in and what’s going out. I think you’ll be quite surprised at what you’re actually spending and what you’re spending it on. Without a budget to rein you in, it’s easy to lose control.
  3. Have a rainy day fund: Everyone at some time in their life is going to have a rainy day. It could be a job loss, health issue, major repair to the house or car or another unforeseen circumstance that will need a large amount of money. Unless you plan for the unexpected, you could be significantly impaired financially.
  4. Keeping up with the Jones: Are you worried about keeping up with the neighbours and living in a house beyond your means, driving cars that are too expensive and spending way too much money to give the impression of having money? This is a recipe for financial disaster.
  5. Indulging adult children: Are you going into debt supporting adult children? Borrowing money or dipping into your retirement savings so your kids can buy a house? Love your children, but don’t go into debt for them.

Money management mistakes: We can correct your worst money mistakes

If you’ve already fallen victim to any of these money mistakes, it’s time for professional help now. Ira Smith Trustee & Receiver Inc. has helped people just like you in the Greater Toronto Area (GTA) for many years. Starting Over, Starting Now, we can help you overcome your financially difficulties. Contact us today.

Categories
Brandon Blog Post

PONZI SCHEME CRIMINALS: CANADIAN PONZI SCHEME GUY WHO RUINED LIVES SENTENCED TO 7 YEARS FOR MASSIVE PONZI SCHEME

2

Ponzi scheme criminals: Introduction

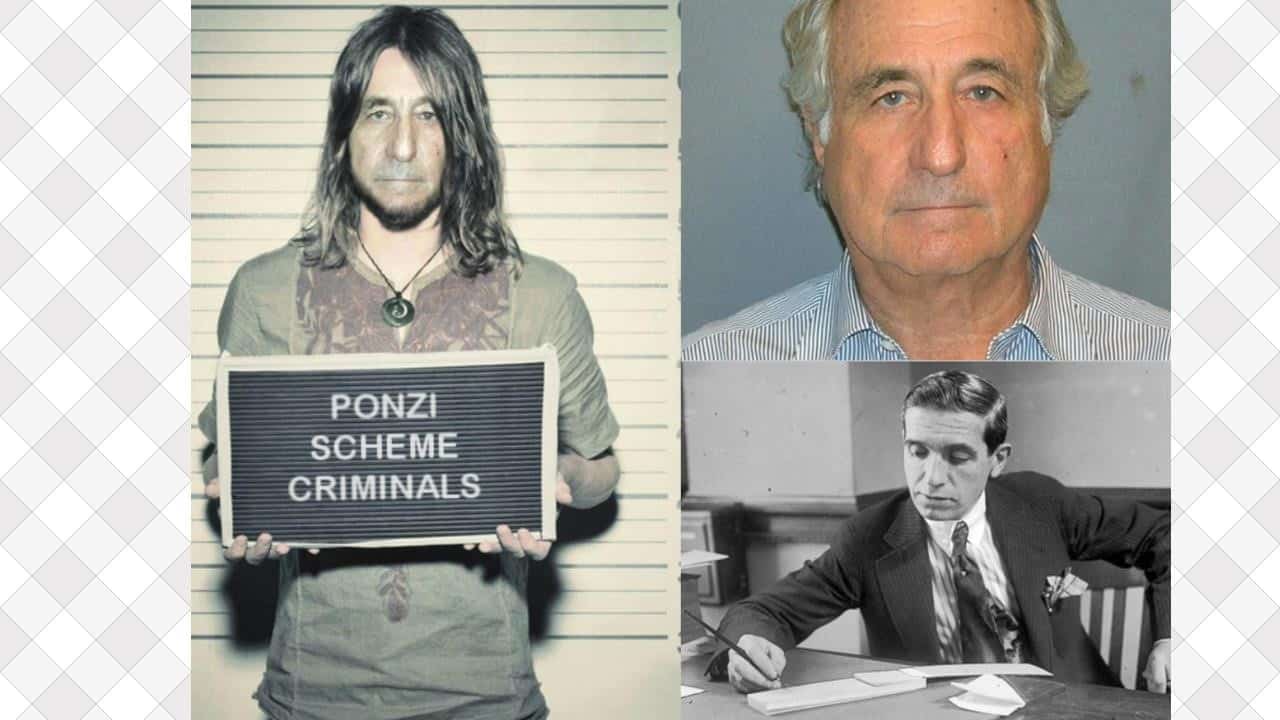
We now have a Canadian to add to the long list of Ponzi scheme criminals. A Ponzi scheme is a fraud perpetrated on unsuspecting parties in which belief in the success of a non-existent enterprise through the payment of quick returns to the first investors from money invested by later investors.

Ponzi scheme criminals: What is a Ponzi scheme?

The name comes from the swindling ways of an Italian born con man in the late 1890’s and early 1900’s – Carlo Pietro Giovanni Guglielmo Tebaldo Ponzi – known in North America as Charles Ponzi. The most famous of the modern-day Ponzi scheme criminals is Bernard (Bernie) Madoff, who is serving 150 years in prison for his multi-billion dollar Ponzi scheme.

Ponzi scheme criminals: Canadian Wade Robert Closson, Ponzi scheme criminal

Canadian Wade Robert Closson, a 48-year-old Sturgeon County, Alberta resident was recently sentenced to seven years in jail for executing a Ponzi scheme. He was originally charged in over 80 counts of fraud. Mr. Closson plead guilty to 53 counts. Most of the fraudulent activities encompassed more than one victim, typically a husband and wife pair. Several of them were present in Court and read their victim impact statements. Others were read on behalf of the victims.

Ponzi scheme criminals: His swindle has caused financial devastation

Many of the victims were discussing feelings of shame. They have experienced overall financial devastation. Some are now still working at the ages of 83, not being able to retire. As a result of the fraud perpetrated upon them by Mr. Closson, they cannot afford to take a vacation or go out for a dinner.

Ponzi scheme criminals: With friends like Mr. Closson……….

Mr. Closson was actually friends and even related to many of the victims. Most of them are talking about the loss of trust in their friend, in humanity and their ability now to relate to other human beings.

He preyed on his friends and relatives, who recruited from their social circles to invest with Closson. A number who lost money in the scam lost more than $100,000 with one suffering a loss of over $600,000. This included cash from a credit line and their RRSP. Closson took $80,000 of that amount out of the couple’s accounts without their authorization.

Ponzi scheme criminals: Essentially, it was a mortgage scam

The overall size of the fraud itself was $11 million dollars that ran through the Ponzi scheme. The Crown was able to prove losses of about $6 million dollars. That is what was in the agreed statement of facts.

The Court heard how Mr. Closson ran the Ponzi between 2006 and 2013. He operated two firms, Optam Holdings Inc. (Optam) and Infinivest Mortgage Investment Corporation (Infinivest), which both entered into bankruptcy in 2013. Closson would take the cash invested in Infinivest to pay off the investors in Optam.

When Optam applied for bankruptcy it detailed about $10 million in liabilities spread out among 69 creditors. The biggest one was Infinivest, which Optam owed $4 million.

ISI 4
ponzi scheme criminals

Ponzi scheme criminals: He recruited friends and family to be on his sales team

Closson made use of the cash to pay himself around $1.185 million throughout the period of the fraud. He used an unspecified amount of money for at least one vehicle, credit cards and golf club. Mortgage payments for his mother-in-law and father-in-law too.

He incentivized people to bring in others into his scheme by paying a commission to his buddies and family members. He invested in various other companies, including a financial investment in a firm that operated a lumber mill in Nicaragua. This investment did not work out well either.

Ponzi scheme criminals: The sentencing

In Court, Closson apologized for his activities and requested the forgiveness of the 20 victims who attended Court for the sentencing!

Justice Belzil ordered Closson to pay restitution of $5.8 million he lost in the Ponzi plan together with a fine of $10,600. He is banned for life from trading in securities.

The Ponzi plan spurred an examination by the Alberta Securities Commission which fined Closson $1 million and banned him from trading in the Province of Alberta in 2015. Up until now Closson has made no payments.

“It is one thing to be taken advantage of by a stranger but this was a trusted friend,” Justice Paul Belzil said when sentencing Mr. Closson.

Ponzi scheme criminals: Wade Closson, the undischarged bankrupt

Closson and his spouse have both filed for bankruptcy on March 27, 2013. He remains an undischarged bankrupt with a hearing set for his discharge from bankruptcy. No doubt that hearing was adjourned until the outcome of the criminal trial was known. Even if Mr. Closson does one day receive a discharge from bankruptcy, the Court fine and the restitution Order, because the restitution is a liability arising out of fraud, will follow him for the rest of his life.

How the bankruptcy discharge process works has been a topic of several of my blogs in the past, including, BANKRUPTCY DISCHARGE: THE TOP 8 THINGS THE BANKRUPTCY COURT WILL CONSIDER ON ANYONE’S BANKRUPTCY DISCHARGE APPLICATION.

Ponzi scheme criminals: Do you have too much debt?

Have you taken on debt that you cannot repay as a result of being swindled from a Ponzi scheme? Have you been swindled and now don’t have enough cash to meet all your debts? Are you facing financial problems for any other reason? The Ira Smith Team can develop a restructuring plan for you.

Debt problems are stressful and confusing. The Ira Smith Trustee & Receiver Inc. Team understands the pain you are going through trying to stay alive and trying to support yourself and your family. We understand the pain and stress you are feeling thinking that you may just soon hit the wall.

Our debt settlement plan process can ease this stress. The Ira Smith Team has a great deal of experience in helping people avoid bankruptcy while resolving their debt problems. We understand your pain points. Call the Ira Smith Team today for your free consultation. We can end your pain and put you back on a healthy profitable path, Starting Over, Starting Now.

ponzi scheme criminals 0
Ponzi scheme criminals
Categories
Brandon Blog Post

PERSONAL FINANCIAL RESPONSIBILITY: WHAT TO DO ABOUT GROWN CHILDREN WHO EXPECT MONEY

2

Personal financial responsibility: Introduction

A few weeks ago, my blog was about PARENTS HELPING CHILDREN BUY A HOUSE: THE SECRET TO KNOWING WHAT TO DO – ASSUMING YOU REALLY HAVE THE MONEY. In that blog I looked the factors parents should consider and possible ways they could help, if proper. I assumed in writing the blog that the adult children were being financially responsible. It reminded me about a recent consultation I performed on a 30ish year old woman who had no personal financial responsibility.

Personal financial responsibility: The referral

An accountant we know referred his client, the father of this woman, to us. I spoke with the father briefly on the telephone and invited his daughter to contact me. As we do with people referred to us, I provided the daughter with a free first consultation where I obtained information about her assets, liabilities, income and expenses.

Personal financial responsibility: The first free consultation

We discussed potential options. At the end of the consultation, my process is to provide the person with our standard intake sheet called the Debt Relief Worksheet (DRW). I asked her to fully complete it with supporting documentation where requested. I also told her that not making another trip to our office, she could scan and email it to me. That way she would not have to take time off work.

Personal financial responsibility: The issues

So far so good. However, things did not stay that way for long. The purpose of the DRW is to give me all the information I need to properly advise someone and to be able to create a solution as unique as that person. It is also designed to allow for financial rehabilitation, by creating a balanced budget for the person to be able to live within their means. There is no point putting someone through an insolvency process, if they don’t come out at the end having learned why financial responsibility is important.

When I received the more or less completed DRW, several things jumped out at me:

  1. The woman graduated from university with a social work degree. However, instead of going into social work, she became a yoga instructor. I found out that yoga instructors, or at least this one, don’t make much money for all the hours worked.
  2. She was one of those people living way beyond your means. On social media, she regularly posted weekend party pictures at bars and clubs.
  3. She could barely pay the rent on her apartment.
  4. She was supplementing her income with credit cards and only paying the minimum monthly payments.
  5. She would soon not be able to borrow any more money from her credit cards and that is why she called for help from her father.

Personal financial responsibility: The father talk

To say the least, I was alarmed. This woman was out of control. Her father was looking to me to tell him if he should lend her (more) money. I called up her father to have a private discussion. I couldn’t disclose the details of the daughter’s financial mess, but I did want to send him a very strong message. The father was already aware of most of her debts, so there really wasn’t any information he was missing.

I told the father the following:

  1. Under no circumstances should he ever lend her money. I doubted she would ever have the capacity to pay him back. This yoga instructor had credit card and income tax debt totalling about $82,000 so a few thousand was not going to cut it.
  2. His daughter should undergo an insolvency proceeding. If he wanted to help, he could fund her consumer proposal as a lump sum, so that this would not be hanging over her head for a long time.
  3. Either a consumer proposal or bankruptcy would create the required debt settlement.
  4. More importantly, whichever insolvency process was chosen, I would make sure that financial rehabilitation would be an outcome. She would learn how to budget, how to not spend more than she earns, net of income tax, and she would gain personal financial responsibility.

Her father was extremely appreciative.

ISI 4
personal financial responsibility

Personal financial responsibility: Consumer proposal vs. bankruptcy

I then met with the adult child again. I explained to her the process of both a consumer proposal and bankruptcy and how each differed. I also explained that her consumer proposal has to be a better offer to her creditors than they could expect in her bankruptcy. I also told her that I spoke with her father, and he was prepared to fund a consumer proposal. I assured her that through a consumer proposal, we could get full debt settlement and she could avoid bankruptcy.

Personal financial responsibility: The yoga instructor had not yet fully grasped the concept of aparigraha

We then got to the budget discussion. In that discussion, she quickly realized that in an insolvency proceeding, she would have to live on what she earned. Her credit cards would be cut off by the lenders and she would not be able to supplement her income with credit card purchases and advances. She stared at me for what seemed to be the longest time. I didn’t know if it was her drishti or she was gearing up to lash out at me.

She then began her mantra “that is not fair, that is not fair, that is not fair”. I asked what isn’t fair? She said she would not have money to party every weekend! Together we each had our aha moment. I quickly learned that her parents never learned how to stop enabling this grown child. She quickly learned that she was not prepared to alter her behaviour and become financially responsible. She thanked me, got up and left. It was pleasant, but not exactly namaste.

A few days later she sent me an email to say that she would not be going through with an insolvency process. I wished her shanti. My understanding is that she did has not filed with another licensed insolvency trustee. So, the only thing left is that Daddy is doing what he originally asked me about – lending or giving her money.

Personal financial responsibility: What to do about grown children who expect money

This is a very sad case. I know I could have helped this woman, but she didn’t want to be helped. She is very happy being one of those adults financially dependent on parents. She is one of those children who has never learned personal financial responsibility.

When your grown child makes bad financial decisions and comes to you for help, what will you do? If you can afford to, will you just enable them or will you seek out a real solution. I am always honoured when a professional believes that I can help someone, especially if it is their child or family member. That is the greatest compliment which has happened several times.

If your child or relative is experiencing financial problems, or if you are as a result of helping your kids, or for any reason, contact a professional trustee as soon as possible. Ira Smith Trustee & Receiver Inc. has helped people just like you throughout the Greater Toronto Area (GTA) facing financial crisis or bankruptcy that need a plan for Starting Over, Starting Now.

Give us a call today and book your free, no obligation consultation. We can help give you back peace of mind and set you on a path to debt free living.

personal financial responsibility 0
personal financial responsibility
Categories
Brandon Blog Post

PAYDAY LOANS AROUND ME: DO PAYDAY LOANS CAUSE A BANKRUPTCY?

payday loans

Introduction

We’ve been sounding the alarm bells about payday loans long and loud, but it seems that many Canadians are still unaware of their dangers. According to the Financial Consumer Agency of Canada (FCAC), many loan users are unaware of the high costs of these loans compared to their alternatives. This includes all such loans around me and you. This just goes to confirm what we already knew – there’s a great need to continue to raise consumer awareness about the costs of, and alternatives to, payday loans.

What the FCAC survey shows

The FCAC recently conducted a survey on payday loans and the results were quite insightful and at times quite surprising:

  • They are an expensive way for consumers to borrow money. The annual percentage rate (APR) is typically 546%.
  • Fewer than 43% of respondents understood that this kind of loan is more expensive than available alternatives. This suggests that many do not have enough knowledge to consistently make the borrowing decisions that best serve their financial well-being.
  • The use of these loans has more than doubled in Canada recently to 4% of Canadian households.
  • 45% of respondents reported typically using such loans for unexpected, necessary expenses.
  • 41% used them for expected, necessary expenses.
  • Users are primarily those with low-to-moderate incomes (more than half lived in households with annual incomes under $55,000).
  • 20% of respondents who used this kind of loans reported household incomes exceeding $80,000.
  • 7% of respondents who used them reported household incomes over $120,000.
  • Many of the users surveyed indicated that they rarely sought financial advice even when they felt it was necessary.

Why not go to a bank or credit union?

Why didn’t respondents access credit from a bank or credit union?

  • 90% said payday lending was the fastest or most convenient option.
  • 74% said payday lending was the best option available to them.
  • 55% said payday lending offered the best customer service.
  • 27% said a bank or credit union would not lend them money.
  • 15% said they did not have time to get a loan from a bank or credit union.
  • 13% said they did not want to get money from a bank or credit union.

Can payday loans lead to bankruptcy?

Payday loans are a huge problem. In fact, the Canadian Payday Loan Association reports that nearly 2 million Canadians use payday loans each year. And many borrowers often find it very difficult to repay the full loan amount with the interest and fees. Now they’re trapped. They take out another payday loan to pay off the first payday loan and then take out another and another. It’s not difficult to imagine payday loans causing bankruptcy.

Are you caught in a payday loan trap?

If you’re caught in the payday loan trap, borrowing more money is not the answer – professional help is. Seek the advice of a professional trustee. Contact Ira Smith Trustee & Receiver Inc. today. You need answers, options and realistic plan for recovery and you need help now.

We’ll evaluate your situation and help you to arrive at the best possible solution for your problems, whether that solution is a bankruptcy alternative like credit counselling, debt consolidation or a consumer proposal or bankruptcy. Starting Over, Starting Now we can help you become debt-free.

payday loans

Categories
Brandon Blog Post

STALKING HORSE ASSET PURCHASE AGREEMENT: THE WEINSTEIN COMPANY GALLOPS INTO A COURT SUPERVISED SALES PROCESS

Stalking horse asset purchase agreement: Introduction

In my July 2015 blog, “STALKING HORSE BID: DO YOU REALLY WANT TO STALK YOUR HORSE ANYWAY?”, I defined and described the stalking horse bid process in the Canadian insolvency context. In my November 2017 vlog, “FILING FOR BANKRUPTCY PROTECTION: THE WEINSTEIN COMPANY RETAINS ATTORNEYS FOR POSSIBLE BANKRUPTCY PROTECTION FILING”, I described the (then) financial condition of The Weinstein Company (TWC) and correctly predicted that it would have no choice but to ultimately file for bankruptcy protection. The purpose of today’s vlog is to provide an update on TWC’s bankruptcy protection filing. My expectation that on April 6, 2018, the US Bankruptcy Court will approve a stalking horse asset purchase agreement.

Stalking horse asset purchase agreement: Stalking horse agreement definition

As a refresher, the stalking horse bid process is, an effort by a company to look at the marketplace ahead of an auction. The intent is to make the most of the value of its assets. This is done as part of normally what is a court supervised public auction sale. It is common to being used in a bankruptcy case.stalking horse bidder

Stalking horse asset purchase agreement: How a stalking horse bid works

The insolvent company in bankruptcy protection, canvasses the marketplace. It comes up with what it determines to be, under the circumstances, the best possible offer. The insolvent company and the potential purchaser, enter into a stalking horse asset purchase agreement. The potential purchaser allows its stalking horse bid to go public.

While entering a stalking horse asset purchase agreement, the company can use bidding process protections. An example is breakup charges. This protects the stalking horse bidder prior to the public auction sale. These incentives improve the worth of the offering for the stalking horse buyer. This process may bring about a far better offer before the public auction starts. This greater deal is currently the beginning deal for the public auction. The aim is to produce the best possible offer.

Stalking horse asset purchase agreement: How did the stalking horse offer process get its name?

This type of bidding process gets its name from the use of a stalking horse in hunting. The hunter uses a horse, or a screen made in the shape of a horse. The hunter stays concealed when stalking prey.

The stalking horse bid becomes “the stalking horse”; the “animal” used to attract the “prey”, being other bidders.

The terms of the sales process would show by what minimum amount any other bid must beat the stalking horse bid. That minimum amount would have to be at least the amount of the break fee. The break fee is compensation for stalking horse bidder. It attempts to compensate for due diligence time and costs if they don’t win the deal.stalking horse bidder

Stalking horse asset purchase agreement: TWC bankruptcy case

In the evening of March 19, 2018, TWC filed for bankruptcy protection in a Delaware Bankruptcy Court. The reasons for the filing were twofold: (i) TWC had canvassed the marketplace and had obtained an offer to purchase its assets by a stalking horse buyer, Lantern Capital; and (ii) to have a Court supervised forum so that both a sale and transfer of the assets can take place and all claimants can make a claim against the resulting cash. TWC announced that anyone subject to a non-disclosure agreement (NDA) was now released. No doubt this will lead to more allegations and claims.

ISI 4
stalking horse asset purchase agreement

Stalking horse asset purchase agreement: The stalking horse purchase agreement

Variety reported that Lantern Capital, a Dallas based private equity firm, entered into the stalking horse asset purchase agreement with TWC. Variety stated Lantern’s bid offers $310 million in cash, plus assuming up to $114.5 million in liabilities connected with TV and film projects, for a total stalking horse bid of $424.5 million.

If approved by the Delaware Bankruptcy Court, this will serve as the floor for other bidders. There is a hearing scheduled for April 6 in Delaware, at which time the Bankruptcy Court is expected to approve this stalking horse bid and the entire stalking horse process. As currently drafted, all other bids must be submitted by April 30. The bids will then be vetted, discussions will take place and TWC will then appear again in Bankruptcy Court to recommend which offer is deemed to be the best and be approved and completed. No further information is available at this time.

Stalking horse asset purchase agreement: Does your company have a buyer but might need a Court-supervised process to finish a sale?

In next week’s vlog, I will provide a case study of how we used a stalking horse asset purchase agreement Bankruptcy Court supervised process to sell the assets of an insolvent company. The successful sale also continued employment for many people.

Is your company facing financial hardship, yet its assets are attractive to multiple potential purchasers? Perhaps you need to be thinking of using bankruptcy protection to maximize the value of the company’s assets through a sale. This process can also continue employment for both you the entrepreneur owner and for many of your current employees.

The Ira Smith Trustee & Receiver Inc. Team understands the pain you are going through trying to keep your company alive while trying to negotiate with potential purchasers. We understand that you are playing beat the clock, and the pain and stress you are feeling thinking that you may just run out of time. The bankruptcy protection process can ease this stress and provide a level playing field so that no potential purchaser takes advantage of you.

The Ira Smith Team has a great deal of experience in running a stalking horse stalking horse asset purchase agreement. The stress placed upon you due to your company’s financial challenges is enormous. We understand your pain points. Call the Ira Smith Team today for your free consultation. We can end your pain and put your company back on a healthy profitable path, Starting Over, Starting Now.stalking horse bidder

Categories
Brandon Blog Post

PARENTS HELPING CHILDREN BUY A HOUSE: THE SECRET TO KNOWING WHAT TO DO – ASSUMING YOU REALLY HAVE THE MONEY

parents helping kids buy a home 0
parents helping children

Parents helping children buy a house: Introduction

Your kids are ready to buy their first house, but the financial realities of buying in cities like Toronto and Vancouver have all but dashed their hopes. Like the kind and caring parents you are, your first reaction is to jump in and save the day. You want to be one of those parents helping children buy a house.

This is not the same as sponsoring a child in need. You have provided for your kids throughout and you want to help your kids become home owners; but, is that really a good idea? I know that buying a house for a child to live in is an emotionally charged issue, but there is a practicality to financial matters that should not be ignored.

Parents helping children buy a house: New mortgage rules stress test

The Office of the Superintendent of Financial Institutions’ (OSFI) new mortgage rules include a tougher need for buyers to be stress tested to see whether they can handle higher interest rates. Some may not qualify for the mortgage amount they want and may not be able to buy a house without parental help. In addition, parents are often asked to help with a down-payment. According to a 2017 national survey conducted by Leger on behalf of the Financial Planning Standards Council, 37% of Canadian parents intend to help their children with the purchase of their first home. Whether or not they can or should help financially is another issue.

Parents helping children buy a house: The secret to knowing what to do

Some parents gift the money and others look at it as a loan. Either way, there are some important issues you should consider before helping your kids buy their first home. It really isn’t a secret – just 4 simple questions to answer:

  1. Can you really afford to help your kids buy their first home? Some parents put themselves in financial jeopardy or risk their retirement savings. This is never a good idea. Will helping your kids buy a home impact your style of living? It shouldn’t. It doesn’t mean you love your kids less if you can’t help financially with the purchase of a home.
  2. Establish limits. If you can afford to help, sit down with your financial advisor/planner and establish the amount of money that you can comfortably help out with and stick to that amount. Don’t allow yourselves to be pressured into giving more than you can afford.
  3. Can your kids realistically afford to own a home? Home ownership is so much more than making a mortgage payment. There are property taxes, insurance, maintenance, utilities, unexpected repairs, etc. And what would happen if there was a health crisis or job loss? Can they afford to be home owners?
  4. Are your kids responsible with money? Or are they living above their means with maxed out credit cards? Have you had to bail them out of a financial jam before?

Parents helping children buy a house: Don’t put yourself in financial jeopardy!

Whatever you do, don’t put yourself in financial jeopardy! If you’re now experiencing financial problems as a result of helping your kids buy their first house, or for any reason, contact a professional trustee as soon as possible. Ira Smith Trustee & Receiver Inc. has helped people just like you throughout the Greater Toronto Area (GTA) facing financial crisis or bankruptcy that need a plan for Starting Over, Starting Now. Give us a call today and book your free, no obligation consultation. We can help give you back peace of mind and set you on a path to debt free living.
ISI 4
parents helping children
Categories
Brandon Blog Post

CLAIM BANKRUPTCY IN ONTARIO CASE STUDY: SHE REALLY WANTED TO BUT WE STOPPED HER AND SOLVED HER PROBLEMS

2

Claim bankruptcy in Ontario: Case study introduction

For today, and the next few weeks, I want to give you some interesting case studies direct from our files. I will not mention any real names of course. Hopefully from these case studies, you will see that we do a lot more than just allow people or companies to claim bankruptcy in Ontario.

Claim bankruptcy in Ontario: A variety of problems

Today’s case study deals with our client who is a specialist medical doctor and surgeon. We will call her Dr. X. She had an ongoing successful career and then opened up a specialty high-end clinic to offer services not paid for by OHIP, the provincial medical plan. Unfortunately, Dr. X did not get the best advice from her professional advisers when she established the new business venture.

She set up her clinic in a separate building that she purchased. Dr. X then had it renovated extensively to meet the business’ needs, leased or purchased equipment and hired staff.

This new venture was financed entirely by debt:

  • personal debt such as mortgage financing against the matrimonial home;

  • equipment loans or leases in her personal name; and

  • Equipment and mortgage debt in the new business venture corporation for which Dr. X personally guaranteed it.

Therefore one way or the other, her personal responsibility was for 100% of the debt to get the business started. Her husband was responsible jointly with her for the mortgage raised against the matrimonial home.

The cash flow of the business was insufficient to pay the operating costs and debt financing. She had to keep borrowing money personally to keep the new business alive. The stress this caused affected her previously stellar activities as a surgeon and hurt her marriage. By the time Dr. X was came to us, she and her husband were separated and divorce proceedings were underway.

Claim bankruptcy in Ontario: And then it got even worse

To make matters worse, she could not attempt to liquidate assets to pay down debt and ease the burden. Like most equipment, the clinic’s equipment was not worth more than its original cost. There was no excess equipment either.

The building could not be sold and leased back for a very bad reason. There was a large environmental problem associated with the building which was not discovered through due diligence prior to purchasing it. The issue arose when she tried to refinance.

The potential lender performed a Phase 1 Environmental Study, which indicated that a earlier use in the building produced contaminants which were buried in the ground. The contaminants were leaching into the neighbours’ respective properties. So now there was further personal liability exposure as the sole Director of the company that owned the real estate!

Claim bankruptcy in Ontario: Filing bankruptcy in Canada would give Dr. X more headaches

Dr. X came to us convinced that she had to go bankrupt. The stress of her failing business was taking a huge toll on her normal duties as a surgeon and her marriage was over. She had previously seen a different licensed insolvency trustee and was convinced from that meeting that bankruptcy was her only answer.

Dr. X considered herself a total failure, in spite of she was still a sought after as a brilliant medical doctor and surgeon. We considered her assets and liabilities, income and expenses and her overall situation.

Claim bankruptcy in Ontario: More complications

To further complicate matters:

  1. The matrimonial home was listed at the amount required to clear all mortgages which was well above market value.

  2. Once Dr. X inevitably stopped making the first mortgage payments on the matrimonial home, the Bank holding the mortgage would begin power of sale proceedings. The first mortgagee would probably suffer a shortfall on the sale and Dr. X and her estranged spouse would be responsible for the shortfall on the first mortgage and the entire balance of the second mortgage.

  3. Dr. X had a life insurance policy with a cash surrender value (“CSV”). The CSV was not exempt from seizure by a bankruptcy trustee because the beneficiary was her Estate. In a bankruptcy, the CSV would go to the Trustee for the benefit of her creditors.

  4. Dr. X did not know if she could get replacement insurance coverage at all and if so, at a reasonable cost.

  5. There were many creditors who currently had a contingent claim against Dr. X with a very high dollar volume. These claims would ultimately be crystallized. In a bankruptcy, we anticipated that a lot of angry ordinary unsecured creditors, many of whom were sophisticated, such as banks and equipment lenders/lessors, would oppose her discharge from bankruptcy.

  6. In a bankruptcy, Dr. X would have to pay about $82,000 in surplus income payments to us as her bankruptcy trustee over a 21 month period for a monthly payment of $3,905. Dr. X could not afford to pay that much each month and keep her normal medical practice afloat.

Bankruptcy was not a good answer for Dr. X. Notwithstanding she earned a high income, the irony was that she could not afford to claim bankruptcy in Ontario!

Claim bankruptcy in Ontario: Our assessment

We had to deal with two problems; one financial and one emotional. Dr. X was an emotional wreck as a result of the failed business venture with all of its problems. We actually had to deal with that first. It is normal for a licensed insolvency trustee to take a holistic approach. The debtor facing financial problems always needs two outcomes: (i) a solution that will allow them to shed their debts and get piece of mind; and (ii) become rehabilitated.

We advised Dr. X that a personal bankruptcy was not the answer for her. We told her that she first had to shut down her clinic. She had to deal with the employees to make sure that they were paid up to the last date work their normal wages and vacation pay. They also needed to get their Record of Employment and T4 Statements as quickly as possible. Unfortunately there was no money for pay in lieu of notice.

Claim bankruptcy in Ontario: How to deal with the failed business venture

We then advised Dr. X that she should not bankrupt the corporation carrying on this new business. Rather, she should call up the first mortgagee and tell that she is abandoning the business premises and is sending the keys over. Then call up the equipment lessors and the lender that did some equipment financing to tell them the business has shut down and they should contact the first mortgagee to gain access to retrieve their property.

Next we advised Dr. X to safeguard the business books and records, so that she could have her accountant file final tax returns. She would also have the records for when Canada Revenue Agency wished to do an audit on the business activities.

The final piece of advice for Dr. X with respect to her new business venture was this. After performing the above steps, walk away. This would end the stress of operating a failing business.

Claim bankruptcy in Ontario: Our assessment and his personal financial fix

All of the contingent debts from the failed business venture had not yet crystallized. They were still contingent. We worked out a cash flow plan with Dr. X that she could keep current with, now that she had abandoned and stopped funding the debt incurred because of the failed business. She also stopped paying the first mortgage on the matrimonial home as the value of the home was now less than the total of the mortgage debt against it.. We worked with Dr. X on a plan to avoid bankruptcy, by filing a formal restructuring proposal under the Bankruptcy and Insolvency Act (Canada) (“BIA”).

Claim bankruptcy in Ontario: The advantages of our strategy

The advantages of this strategy, if the restructuring proposal could be fully performed, are:

  • Dr. X would not give up her assets to a bankruptcy trustee;

  • She would not lose her life insurance coverage or CSV;

  • All of her debts could be eliminated through the restructuring proposal;

  • Although the total of her restructuring proposal payments had to be more than her creditors would get in her bankruptcy, we could term those payments out to a maximum of 5 years;

  • Her estimated monthly payment would be less than the monthly surplus income payment in a bankruptcy; and

  • Dr. X would avoid bankruptcy and an opposed discharge process entirely.

    ISI 4
    claim bankruptcy in ontario

Claim bankruptcy in Ontario: The result

Dr. X followed our advice. Her restructuring proposal was accepted by her creditors qualified to vote at the meeting of creditors held 21 days after the filing of the restructuring proposal. The contingent claims had not yet crystallized. Although eventually those creditors were allowed to file their proper respective claims and take part in the dividends paid out to the unsecured creditors, we made it successfully through the voting process. The proposal was then approved by the Court.

Dr. X not only maintained her regular monthly proposal payments to us, she was able to pay off the proposal early. The reason for this was that now that she had a clear head and no longer felt she was a failure, she could focus on her medical practice and surgery, which once again flourished. Her income and savings rose. These are some of the benefits that financial rehabilitation brings. Dr. X also avoided going bankrupt.

Claim bankruptcy in Ontario: Does Dr. X’s financial problems sound familiar to you?

I present this case study to show how, as a licensed insolvency trustee in the GTA, we look at the entire story of each person or company that comes to us for help. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we stopped Dr. X from going bankrupt and devised an alternate plan for her, allowed her to solve her financial problems and get her life back.

We know that people facing financial problems need a realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team. If any of this sounds familiar to you and you are serious in finding a solution, contact the Ira Smith Team today.

Call us now for a free consultation. We will get you back on the road to a healthy stress free life and your recovery will be as pain-free as possible. We may be able to stop you to claim bankruptcy in Ontario!

claim bankruptcy in ontario 0
claim bankruptcy in ontario


Call a Trustee Now!