Categories
Brandon Blog Post

SOMETIMES EVEN A BONA FIDE SHARK NEEDS BANKRUPTCY AND INSOLVENCY HELP

bankruptcy and insolvency

If you would prefer to listen to the audio version of this bankruptcy and insolvency Brandon’s Blog, please scroll to the bottom and click on the podcast.

Bankruptcy and insolvency: Introduction

Not every innovation that is seen on The Shark Tank is bound to be one of the very best. Among the winners, Fizzics is a machine that makes use of sound waves that improve the taste and quality of a beer. Not even a Shark can stop its company from being driven to bankruptcy and insolvency Chapter 11 bankruptcy protection. This proves that often an ingenious and fantastic invention being marketed with the assistance of a Shark might not truly interest people.

bankruptcy and insolvency

Fizzics was seen on the season 8 première of The Shark Tank. The judges, in spite of the early skepticism, accepted this pitch. It currently seems to be backfiring in a huge way. The idea of making a bottle of beer taste better, just like a draft beer from the tap, isn’t a silly way to invest your time. But a better tasting beer is a big luxury. Many people may check out is the brand-new shiny plaything on the block. It is something wacky and cute but not completely effective or needed.

What is difference between bankruptcy and insolvency in Canada?

What is insolvency? – Individuals are considered to be insolvent when they are not able to pay the financial debts they owe their creditors on their respective due dates. If you become insolvent, you might choose to declare bankruptcy, or you could handle your financial debts with other options such as a consolidation loan or a debt settlement consumer proposal.

Insolvency and bankruptcy are 2 terms that are often very closely associated when discussing debt. However, they have very different meanings. Insolvency describes an economic state. It is when you cannot afford to pay your debts when due. If you liquidated all of your assets, there would not be enough money to pay off all your debts in full.

What is bankruptcy? – Bankruptcy is a legal process. It means that a creditor has gone to court and obtained a Bankruptcy Order to place a person or company into the legal status of bankruptcy. Or, the person or company has filed an Assignment in Bankruptcy. The Bankruptcy and Insolvency Act (BIA) is the Canadian bankruptcy law legislation regulating all administrations of the BIA in Canada.

The various kinds of insolvency proceedings under the BIA are:

  • corporate bankruptcy;
  • personal bankruptcy; either a summary administration bankruptcy or an ordinary administration.
  • consumer proposals;
  • Part III Division I Proposal; and
  • receiverships.

Canadian BIA insolvency proceedings and bankruptcy proceedings can only be administered by licensed insolvency trustees (formerly called trustees in bankruptcy). The short form for a trustee in bankruptcy is now LIT, licensed insolvency trustee (Trustee). Trustees are licensed and supervised by the Office of the Superintendent of Bankruptcy (Canada) (OSB) which is part of Industry Canada. The OSB is responsible for the administration of bankruptcies in Canada.

Bankruptcy and Insolvency: Does the consumer really need it?

Eventually, these types of ideas are those that often tend to seem like the most effective thing since sliced bread. Their shiny brand-new finish tends to subside promptly given the expense of creating them. Even tougher, is finding a large enough market of people who truly intend to quit the dependable and old ways to carry out something. The uniqueness will swiftly wear away. The equipment will then come to be a chunk of scrap that is most likely to rest on the counter and seldom gets used. That might seem unkind, however, usefulness and need to at some point seem to divide the wheat (or barley) from the chaff!

So Fizzics, for all that it is able to do, turned out to be not the sort of device that has the ability to make a great deal of sense in a business setting. It is just for home-usage. In a bar, people go to consume alcohol and socialize. They are not there to wait on a number of sound waves to make their drink preference taste and look better. If they want a draft beer, they will order from the tap. If they want a bottled beer, that is what they will order.

For home usage, it is an excellent novelty. Everyone has their favourite beer. People anticipate it to taste the way they know it too – straight out of the bottle or can.

The Fizzics Business: The Sharks bit and invested money

Philip Petracca and his partner, David McDonald, made it to ABC’s “Shark Tank” in 2016, offering beer to a hesitant panel. They eventually turned most of the judges into followers. Lori Greiner and fellow Shark Mark Cuban agreed to spend $2 million into Fizzics for a consolidated 16.67 percent equity. Fizzics attained its objective of expanding its selling networks.

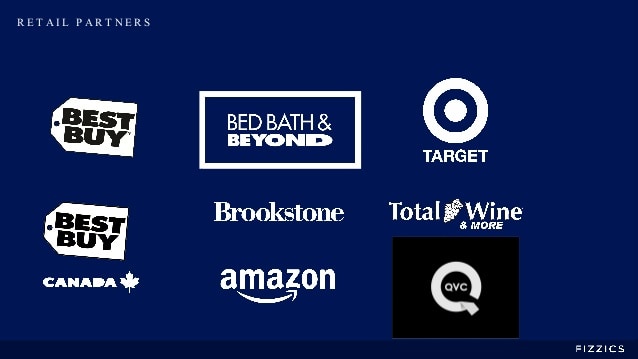
With the help of the Sharks, Fizzics entered Target, Best Buy, Brookstone, on Amazon, and several other areas– including Bed, Bath & Beyond. They have been reviewed in many renowned publications, and on several websites such as Yahoo! Tech as well as CNet. The Fizzics beer-making device was called absolutely nothing short of a wonder.

bankruptcy and insolvency

They increased their patented modern technology and generated a much more portable item called the Fizzics Waytap. Beer fanatics were still going crazy about the original dispenser in magazines.

On March 12, 2019, Fizzics Group, Inc. applied for Chapter 11 bankruptcy in Delaware under the United States insolvency and bankruptcy code. It reported assets of between $100,000 as well as $500,000 and debts of between $1 million and $10 million (based on contingencies and disputed claims). Time will tell if the business can be reorganized and saved, or if the remaining product inventory will end up in the clearance area!

Bankruptcy and insolvency: Do you need help?

I hope you enjoyed this Fizzics Shark Tank bankruptcy and insolvency blog. Do you or your business have excessive debt? Are you having an issue making your month-to-month expenses? Is your company handling its financial obstacles something you simply can’t figure the way out of? Are you looking for a business restructuring plan or an individual debt negotiation plan?

If so, call the Ira Smith Team today. We have years and generations of experience helping people and companies seeking financial restructuring or a debt settlement strategy. As a licensed insolvency trustee, we are the only specialists recognized, accredited and supervised by the Federal government to give insolvency advice and remedies to assist you and to prevent bankruptcy.

Call the Ira Smith Team today so you can end the stress and anxiety financial problems create. With the special roadmap, we will develop with and special to you, we will promptly return you right into a healthy, balanced hassle-free life.

You can have a no-cost appointment to assist you so we can fix your debt troubles. Call the Ira Smith Team today. This will certainly allow you to make a fresh start, Starting Over Starting Now.


Categories
Brandon Blog Post

WHAT IS A GOOD CREDIT SCORE IN CANADA? THE UNTOLD CREDIT SCORE SECRETS

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20479″]

What is a good credit score in Canada: Introduction

I have previously written reviews of the two main companies that can give you your credit score for free in Canada. The two are Credit Karma Canada and Borrowell. It is one thing to know what your credit score is. But what does that number mean? Do you have control over how to increase your credit score? To answer those questions, you must know the topic I am writing about in this Brandon’s Blog. What is a good credit score in Canada?

Your credit rating

There are three main points you need to learn about your credit rating. In Canada, your credit score is a number between 300 and 900. Lenders use this to forecast just how likely you are to be responsible with the money they are considering providing you. Will you pay back the cash you are asking they fund you?

The greater your score number, the more probable you are to be an excellent wager to be able to pay back what you owe. Your credit history is composed of five elements:

  1. Your payment history composes 35%.
  2. How much debt you owe comprises 30%.
  3. The length of your history makes up 15%.
  4. 10% comes from the sorts of loans or credit cards you have.
  5. Just how often you typically apply to borrow has a 10% effect.

A better understanding

Let’s drill down on this a little more. The greatest chunk is your repayment history. This checks out whether you’re making your payments on time. If you’re late on repayments, exactly how often are you late or are there financial obligations in the enforcement and collection process. How much debt you owe takes into account how much debt is owed and how much borrowing room is still available to you.

The length of your borrowing history considers how long you’ve had your loan products for. The longer you’ve had them the better it is for your history. Types of credit look at the range of items you have. A brand-new application is when you ask for a new loan. New loan applications stay on your report for three years. Applying many times decreases your score.

The theory is that if you keep applying, you are having 2 problems. The first is that you keep needing new loans for some reason. The second problem is that you must keep being turned down in order for you to need to keep applying.

Hard and soft hits

When you apply for a new loan, the potential lender performs a check on you. This produces what is known as a hard hit which can negatively impact your score. When you pull your own reports, such as through Credit Karma Canada or Borrowell, this makes what they call a soft hit. This won’t negatively impact your score.

How often should I check my score?

You might be wondering do you need to look at your own score monthly? I am here to tell you that you don’t. Your rating adjusts throughout the month based on the five items I spoke of above. So your rating can look different from month to month.

If you’re exercising excellent credit rating behaviour a new report will certainly show that. Likewise, if you are not acting responsibly, your report and your score will show that. What I do recommend you do is check your rating by pulling an annual credit report. You do this to ensure that your record is exact and there are no errors in it.

The most effective time to check the accuracy of your report would certainly be prior to you making a huge purchase for something like a home or vehicle. You recognize that your lender will certainly perform a check. It is to your benefit to make sure everything on your rating profile looks good and is error free.

In that situation, where a lot is riding on the precision and completeness of your report, you would go directly to the two main score rating companies in Canada; Equifax Canada and TransUnion Canada. You will certainly have to pay for them to generate an Equifax or TransUnion score and history report for you. What you pay them to understand that your record is precise and totally error-free is worth that peace of mind.

4 things you must know about your score

To summarize, the 4 things you must know about your score are:

  1. Your credit score in Canada is a number between 300 and 900.
  2. Lenders use your credit score to forecast just how likely you are to be responsible with the credit they are considering providing you.
  3. The greater your credit score number, the more probable you are to be an excellent wager to be able to pay back what you owe.
  4. Your credit history is composed of five elements:
    1. your payment history composes 35%;
    2. how much debt you owe comprises 30%;
    3. the length of your credit history makes up 15%;
    4. 10% comes from the sorts of credit you have;
    5. just how often you typically apply for new credit has a 10% effect; and
    6. lastly, you don’t need to check the credit score all the time.

You might have a concern about, and ask yourself, is Credit Karma Canada safe? Is Borrowell safe? The answer is yes, but you still may have a concern. You are providing each of them with very personal information about yourself when you first sign up for their respective services. Then they do on a regular basis perform a credit score check on you. These are soft hits, so it won’t affect your score. However, they are updating your private personal information which stays on their database. Anytime such sensitive information is on a computer server, there is, of course, a danger from hackers.

The reason they regularly check your credit situation is so they can then send you an email about any change to your credit score – good or bad. They do this for two reasons. The first is to alert you about their latest finding of your credit report. The second reason is to give you a reason to go to their website. Their hope, of course, is while you are on their site seeing the change to your credit score, perhaps you will stay and look at some of the products they offer to produce revenue for themselves.

What is a good credit score in Canada: What about you?

I hope this what is a good credit score in Canada blog has helped you gain a better understanding. Question: Have you lost the ability to borrow because of a bad credit score? Are you having trouble making your monthly payments? Is your business dealing with financial challenges that require to be addressed immediately?

Call the Ira Smith Team today if so. We have years along with generations of experience aiding people and companies looking for financial restructuring or a debt settlement plan. As a licensed insolvency trustee, we are the only professionals recognized, licensed and supervised by the Federal government to provide insolvency advice and services to assist you to stay clear of bankruptcy.

Call the Ira Smith Team today so you can end your stress, anxiety and pain today. With the roadmap we develop unique to your situation, we will swiftly return you right into a balanced, healthy and carefree life.

You can have a no-cost assessment to assist you to repair your credit and debt troubles. With you, we will uncover your financial discomfort points and use a method to rid them from your life. This will absolutely allow you to begin a fresh start, Starting Over Starting Now.what is a good credit score in canada


Categories
Brandon Blog Post

RETAIL STORE CLOSINGS 2019 USA

retail store

If you would prefer to listen to the audio version of the retail store closings 2019 USA Brandon’s Blog, please scroll to the bottom and click on the podcast

Retail store: Introduction

The retail apocalypse in 2019 is continuing. We hear almost daily about US chains filing for bankruptcy protection and retail store closings. We are seeing stores closing in America more often than stores are being opened. I am talking about brick and mortar stores closing down. Is it strictly because of Amazon and other online sellers? We will discuss that in a bit.

Retail store: Victoria’s Secret

Victoria’s Secret’s parent company, L Brands, in its most recent earnings report earnings announced that they would be closing 53 stores this year. That follows up from 30 in 2018. Victoria’s Secret has been accused of not fitting into the #MeToo era and not adapting to change.

Critics say that the runway show is outdated and that the images in stores are inappropriate. Other brands like American Eagle’s Aerie are launching more body-positive campaigns. They also said that they would never use airbrushed photos. So while Aerie has had explosive success over the last few years, Victoria’s Secret slowly has seen its sales slide.

In the most recent runway show, which took place in November, Victoria’s Secret came under fire. Before the runway show aired publicly, Ed Razek, the chief marketing officer, was interviewed by Vogue. He made some controversial comments about plus-size and transsexual models being featured in the show or rather not being featured in the show. This caused a big outrage online and so, whether it’s a result of this, their ratings. The viewership ratings actually fell this year versus the year before.

So increasingly, new brands are cropping up. People are seeing that more body-positive brands like American Eagle’s Aerie are achieving a lot of success. So new brands like ThirdLove, Lively and Rihanna even has her own line of lingerie. They are trying to fill the void that Victoria’s Secret has created of creating more body-positive clothing by having extended sizes and more body-positive and inclusive marketing.

Store closures are trying to deal with a more urgent problem, slipping sales. There has also been talking of quality concerns in Victoria Secret’s garments. It would seem that they have their work cut out for them.

Retail store: Michaels

Dallasnews.com reports that the arts and crafts retailer Michaels is closing 36 of their Ohio based Pat Catan stores they purchased. They are citing it as consumer volatility. Chuck Rubin, CEO of Michaels, stated in January 2019 that they have seen more volatility in consumer shopping behaviour than they initially expected. He also went on to say that Michaels is lowering its 2018 fourth-quarter outlook for same-store sales and profit.

Retail store: Things Remembered

Next up is Things Remembered. They have announced that they are going to be filing for Chapter 11 bankruptcy protection. As part of their reorganization plan, they will be closing most of their 400 stores in shopping malls. They will keep their strong performing stores. Things Remembered sells customizable gifts including jewelry and decorative items. You can have engraved your personalized message on a necklace or other jewelry or item. They were founded 40 years ago. As recently as June 2018 Things Remembered had 450 stores open. That dwindled down to 400 stores and now the bankruptcy filing. Time will tell if they can really survive.

Retail store: Department stores

Sears, Kmart, JC Penney, Macy’s, Kohl’s and Nordstrom have all announced store closures. The Motley Fool reports that over the past decade Nordstrom has closed an average of about two stores a year. So more department store closures, especially Sears closing down, is really not a new story.

Last January, Kohl’s announced four store closures. With all store closures, people lose their jobs. Kohl’s stock has fallen because same-store sales growth slowed. It has also been reported that Kohl’s is going to offer voluntary retirement programs to hourly associates who are age 55 years or older and who have at least 15 years of service.

The Wall Street Journal reported that owners of retail buildings, including malls, are reducing rents now for some stores that are seeing struggling sales. This includes JC Penney and some of the Sears locations that are still open. They are doing that because they fear that there may not be other anchor stores that are going to be able to come in and replace them.

Moneywise.com reported that Target Stores may be closing some stores. However, they have also announced new store openings. So with Target Stores, it seems to be more of a rebalancing shutting down underperforming locations.

Lord and Taylor, owned by Hudson’s Bay Company, announced certain store closures also. They reported that weak holiday sales led to the decision at the end of 2018. Lord and Taylor closed one of their more iconic locations on Fifth Avenue in New York City.

Retail store: Other

Upscale accessories store Henri Bendel will be closing 19 23 stores in 2019. That also includes their store on Fifth Avenue in New York. They have been in business for more than one hundred years. Christopher & Banks sell women’s and especially petite clothing. They say they are going to close between 30 and 40 of their over 400 stores.

Gap and the Banana Republic. A lot of clothing stores are on the chopping block. Between Gap and the Banana Republic, there is going to be over 200 stores shutting down. Clothing retailer Chico’s announced they will be closing 250 stores in the United States. The Gymboree bankruptcy resulted in the sale of certain assets, but not store locations. About 900 stores closed.

Retail store: Is it only because of Amazon?

The U.S. Fed reports that the consumer savings rate is at 6%. It has not been that low since March 2013. The Fed also reported that Americans’ savings are dwindling combined with rising debt levels. There is a similar story in Canada.

No doubt that online shopping, including Amazon, takes up a big chunk of who normally would have shopped at these brick-and-mortar retailers. But we know that low savings and high debt can’t go on forever. You can’t see savings continue to decline and debt continuing to increase. As I have previously written in many blogs, there has to hit a limit at some point and that’s called insolvency.

Retail store: How about you?

Do you have too much debt? Are you having a problem making your month-to-month bill payments? Is your company dealing with financial obstacles that you just can’t figure the way out of?

If so, call the Ira Smith Team today. We have years and generations of experience aiding individuals and businesses looking for financial restructuring or a debt settlement plan. As a licensed insolvency trustee, we are the only experts recognized, licensed and supervised by the Federal government (the OSB) to provide insolvency recommendations and solutions to help you prevent the B word.

Call the Ira Smith Team today so you can end the stress and anxiety financial problems create. With the special roadmap, we develop unique to you, we will promptly return you right into a healthy and balanced stress-free life.

You can have a no-cost consultation to aid you so we can repair your debt problems. Call the Ira Smith Team today. This will definitely enable you to make a fresh start, Starting Over Starting Now.

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20503″]

Categories
Brandon Blog Post

BANKRUPTCY IN ONTARIO CANADA SECRETS REVEALED

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20475″]

Bankruptcy in Ontario Canada: Introduction

Most people are afraid of filing for bankruptcy in Ontario Canada and rightly so. It should be a last resort. There are many options available to people in financial trouble. All of them should be canvassed before deciding to declare bankruptcy.

In my professional practice, during the first free consultation appointment, we look at all options with the person to avoid bankruptcy. We naturally have a discussion about what it is and how it will affect the person. That way, the potential client is aware of all the options and can make an educated decision.

In this Brandon’s Blog, I discuss the questions that I am most often asked about the process. Hopefully, by the end of this blog, I will have demystified the process for you and helped in aiding your understanding.

The secrets we will show

Bankruptcy in Ontario Canada is definitely something nobody wants to talk about. So, therefore, it makes it seem very mysterious and secretive. It is also very scary. Therefore, from now on in this blog, so as not to scare you unnecessarily, I will try to refer to it only as “the B word”. I will only use the B word if the context requires it. This Brandon’s Blog will hopefully pull back the curtain in answering the most often asked questions thereby reducing the mystique and hopefully, your anxiety about this topic.

Where do I begin?

The first step is recognizing that you have financial problems and that bankruptcy in Ontario Canada might be your new reality. If you are having difficulty meeting all of your financial responsibilities or have actually quit paying all of your bills on time, you have a financial problem. As a licensed insolvency trustee (Trustee) we are the only professional licensed and supervised by the Federal government – Industry Canada (OSB).

If you are having financial problems, you must contact a Trustee as soon as possible, to have a free consultation to check your situation and to understand all the options available to you, including the B word. In that free appointment, you will learn that the B word may not be your only alternative to leave your debt behind. There are a number of choices that include, however, are not restricted to:

Should I declare the B word and what happens immediately if I do?

Declaring the B word is obviously a very serious step and a difficult personal choice. If the Trustee has properly explained all the realistic options available to you, it will make your choice much less scary. The first question is do you even qualify to file for the B word. You must be insolvent, owe more than $1,000 in unsecured debt to qualify for it in Canada.

As far as filing for the B word in Premier Doug Ford’s province, you must have:

  1. carried on business in the province during the year immediately preceding your B word; or
  2. lived in the province during the year before your B word; or
  3. where 1 or 2 above don’t apply, the majority of your property is in the province.

Note that the first test is that you are actually insolvent. Insolvent or insolvency is a financial condition. It means that you are:

  1. Unable to meet your obligations generally as they become due.
  2. You have ceased paying your current debts as they come due.
  3. The fair value of all of your assets is less than the total amount of your debts.

The B word is a legal state. Insolvency is a financial condition.

If I go for the B word, will I lose everything?

If you declare the B word, no, you will certainly not lose everything. There is a listing of things that are excluded from seizure in Ontario. The list is:

  • Necessary clothing for you and your dependants.
  • Home furnishings and appliances that are of a worth not more than $13,150.
  • Tools and various other personal effects not worth more than $11,300, made use to earn revenue from your business. If you are an Ontario farmer, this amount increases to $29,100 for everything, including your livestock.
  • One car or truck that is worth not more than $6,600.
  • The cash surrender value of life insurance if your beneficiary is what is called a “Designated Beneficiary”.
  • Your Registered Retirement Savings Plan (RRSP), Registered Retirement Income Fund (RRIF) or Deferred Profit Sharing Plan (DPSP) other than for any amounts contributed in the 12 months immediately preceding your date of bankruptcy.
  • $10,000 of equity in your home but only if your share of the equity is less than $10,000 in total.

So if you go the way of the B word, based on this listing, you won’t lose everything. However, as you can see, if your share of the equity in your home is significant, the B word very likely is not for you. One of the other options is probably more suitable and you should pursue one of them.

What happens to the money I owe?

Once you go with the B word, all of your unsecured debts are frozen. Creditors cannot begin or continue any legal action against you. Any garnishee on either your wages or your bank account must come off. Normally if you owe money to Canada Revenue Agency (CRA) and have not kept up with a payment plan to them, they will garnishee your bank account which stops you from using it. The B word stops a CRA garnishee against your bank account or salary or wages also.

Similarly, a creditor who sues you and gets a judgement against you cannot continue any execution against your assets.

Once you are in the B word, the Trustee sends a notice to all of your creditors, along with a proof of claim form and instructions. With certain limited exceptions, the only remedy your unsecured creditors have is to file a proof of claim with the Trustee.

This does not apply to any of your debts owed to lenders who hold valid security against a specific asset. Examples would be a bank holding a mortgage against your home in return for the mortgage money or a lender who has security against your car for an auto loan.

What takes place to my salary or wages once I file?

Your income is not impacted by the B word process. You will continue to receive your normal salary or wages as you always have. You will need to complete Income and Expense Forms throughout detailing your and your spouse’s earnings and expenses. This is part of your budgeting procedure to meet one of the aims of the B word process; financial rehabilitation.

If your family income goes beyond specific requirements developed by the OSB, you will need to pay a part to the Trustee. This is called a surplus income payment requirement. In the first free consultation, I always tell potential clients whether they will have such a requirement. We also then look at that requirement, if any, to see if a consumer proposal would be more beneficial to the person than the B word.

Will the B word process get rid of my student loans?

If the B word date is within 7 years of when you stopped being a full-time or part-time student, your student loan debt will not be released by the B word process. Nevertheless, in particular situations, you might have the ability to make an application to the court for a discharge of your student loan financial obligations under the “hardship provision.” It is almost impossible to get that court-ordered discharge, but the slim possibility is there.

Will I still owe money after I file?

Only for a limited amount of debts. A discharge from the B word process does not cover:

  • secured loans – home mortgage or vehicle loan;
  • certain student loans (remember the 7-year rule I just mentioned?);
  • penalties or fines enforced by the court;
  • spousal support and alimony you have to make in your separation agreement or divorce proceedings; and
  • any debts from a fraud.

What length of time will I be in the B word system?

The length of time you will be in the B word system depends on whether this is an initial or 2nd time and whether you have surplus income. The minimum length of time is 9 months. That is if you don’t have any surplus income, none of your creditors oppose your discharge and it is your first time.

If it is your first time, none of your creditors oppose your discharge and you do have surplus income, then the 9 months increases to 21 months.

If it will not be your first time, the length of time before you can get a discharge will depend on many factors. We certainly discuss it during your first free consultation.

Who will find out that I have filed?

As soon as you declare the B word your Trustee will tell your creditors, the CRA, the credit bureaus and the OSB. The filing is public information and it will show up in your credit history.

Where your non-exempt assets given to the Trustee are worth more than $15,000, there must be a legal notice of your B word filing in the local paper.

Exactly how will it impact my credit score?

A person who files drops down to the least favourable credit rating (R9) immediately. After you declare the B word, you must start to work on improving your credit score. Once you are discharged, you will have more options to improve on your credit score and rebuild your credit.

Notice of the B word process will stay on your credit record for 7 years after you get your discharge.

How is my partner or spouse affected by my filing?

Your spouse or partner is not directly impacted by your filing. Your spouse or partner will have to show his or her income as part of your surplus income calculation. The partner or spouse will be liable to repay any loan they have co-signed or guaranteed for you. They will also have to repay any credit card balance on your account for which they have and used a supplementary card to make purchases.

Will my bankruptcy impact my ongoing divorce case?

In Canada, the B word rules do not conflict with most of the family law system and process. So the Trustee will not get involved in your family law proceedings, with two main exceptions.

There is an aspect of your divorce in Ontario that will be affected because Ontario is an equalization province. There are generally only 2 parts of your divorce proceedings your Trustee will certainly get involved in. One is when it pertains to the person who filed legal rights to entitlement to an equalization payment. Second is when the debtor owns property (either jointly with the spouse or alone) and such property has not already been dealt with in the family law proceedings.

How do I choose the right Trustee for me?

Sometimes people just say that “I want to go to the closest Trustee near me”. If travelling or time is an issue for you then that approach is quite legitimate.

The better way is making an appointment for a cost-free no commitment first consultation with a Trustee. If you can, it is best to get a referral from someone you trust. Otherwise, perform an online search and see which Trustee’s website resonates best with you. Ask any kind of questions you might have about your particular situation and the options you may have.

If after that appointment you feel comfortable with the knowledge and demeanour of the Trustee, and you felt confident that you received proper answers to your questions, then great. If not, make an appointment for a free first consultation with a different Trustee. Use that experience to compare both to see who you would like to put your trust in. At the end of the day, you have to know who you will be dealing with and feel comfortable with them. You have to know that your Trustee gets you!

Do you have too much debt? Are you having a problem making your month-to-month bill payments? Is your company dealing with financial obstacles that you just can’t figure the way out of?

If so, call the Ira Smith Team today. We have years and generations of experience aiding individuals and businesses looking for financial restructuring or a debt settlement plan. As a licensed insolvency trustee, we are the only experts recognized, licensed and supervised by the Federal government (the OSB) to provide insolvency recommendations and solutions to help you prevent the B word.

Call the Ira Smith Team today so you can end the stress and anxiety financial problems create. With the special roadmap, we develop unique to you, we will promptly return you right into a healthy and balanced stress-free life.

You can have a no-cost consultation to aid you so we can repair your debt problems. Call the Ira Smith Team today. This will definitely enable you to make a fresh start, Starting Over Starting Now.

bankruptcy in ontario toronto

Categories
Brandon Blog Post

MY BILLS ARE HIGH: 6 THINGS TO IMMEDIATELY DO

my bills are too high

If you would prefer to listen to the audio version of this my bills Brandon’s Blog, please scroll to the bottom and click on the podcast

My bills are high: Introduction

It is very common when I sit down with a person who has come to my office for a free consultation to hear them say “my bills are high”. As a licensed insolvency trustee, my role is to first understand the person’s entire situation. It is quite possible that I can recommend a few alternatives to avoid bankruptcy.

The purpose of this Brandon’s Blog is to talk about the importance of budgeting and more things a person with financial problems can do before even considering the “B” word.

First thing – household budget

I will show you how to catch up when you are behind on your financial obligations by using a proper household budget plan process. I must warn you that there is no magic wand to wave to make things right. You will have to learn the budgeting technique and be willing to invest a great deal of effort, time and personal and family sacrifices. But it will be worth it. When you are back on track and living within your means, you will have a new stress-free outlook on life.

To start the monthly budget plan process, it does not matter if you use an electronic spreadsheet, a paper listing of income and expenses or a clean calendar. Whatever you are most comfortable using. The process will be the same.

The starting point is for you to list all your bills with their due dates. Don’t forget to make note of any special expenditures during any specific month, such as a spouse or child’s birthday present. Make sure you list all of your expenses regardless if you pay them by cheque, cash, credit card or online payment.

Next, list your monthly income by the date(s) during the month your wages or salary end up in your bank account. Make sure that you are listing your net take-home pay, net of income tax. That is the actual amount of income that you have to spend in any given month.

The 4 corners

Now that you know exactly how much money is coming in every month available for you to pay your expenses, you have to organize your expenses. You first need to know what I call your four corner expenses. These are the expenses that you will have to pay before anything else. This is true whether you continue working at the same place or you lose your job and are looking for new work. The expenses that I call the four corners are:

  • Rent or mortgage payment.
  • Food costs.
  • Heat and electric bills.
  • Clothing expenses.

These are your essentials. Nothing else can be considered before them. So fill in your regular monthly amount for each one. Total up the amount of your four corners expenses and deduct it from your take-home pay. The difference is what you have left over each month to spend on other expenses.

Now go down the list of the rest of your expenses. Car payments, gas and vehicle maintenance, insurance, cable, internet, credit card payments and anything else that you have listed. See what all those expenses total. If the total of those is more than you have leftover cash from the four corners exercise above, then you have to make adjustments. You either have to reduce your other expenses or you have to increase your income. Perhaps it may even be a combination of the two.

If you are behind on any of your payments, because your bills are too high right now, you are going to have to work into your budget increasing the amount of the monthly expenses that you are behind on. However, there is an exception. The exception is that you start with your four corners payments you are behind on.

It won’t help you to bring your credit cards current if the gas company is about to shut off your ability to heat your home. Bringing a life insurance payment current won’t help you if you are behind on your rent or mortgage payments. So again, your four corners payments have to be brought current first. Then you can focus on your other expenses.

Do not worry about anything else. You put it on hold due to the fact that at the end of the day, if you were to have lost your job, the four corners is what you require to make it through, not a credit card payment. You don’t need to fret about your credit rating decreasing since if you are starting this trip you are not looking to borrow more money that needs your credit score to be spot-on. That will come over time after you have your financial house in order.

You worry about taking care of your four corners first. That is a good mind trick to getting yourself out of the loop of being addicted to letting your bills go late. imagine if you would have lost your job you would have no other choice but to not pay the credit cards.

Balance the rest of your expenses

Now, normally when you’re behind on payments that mean that you don’t have enough money to cover all your bills and that is totally fine. I need to emphasize that is totally fine. You will be able to catch up eventually. Most people find ways to catch up by either:

  • Further reducing expenses.
  • Selling stuff.
  • Using an annual bonus.
  • Increasing income with overtime, a part-time job or side hustle.

You need to take care of business. That way you are treading water, not sinking in it!

Now, what about the non-four corners monthly payments that you are deferring. Yes, eventually the credit card company, such as, is going to start hounding you. You will have to explain your temporary problems, tell them what you are doing to correct things, and when you think you will really begin to resume payment. It doesn’t matter who the creditor is. The process of explaining the issues and getting a deferment or grace period is the same. Do not hide from your creditors. Explain the situation and show them that you have a solution for your common problem.

For additional ways to pay down your debt, take a look at my blog DEBT HELP NEAR ME: OUR TORONTO DEBT REPAYMENT CALCULATOR STRATEGY. In it I explain the two most common methods of paying down bills you are behind on; the debt snowball method and the debt avalanche technique.

If you budget properly and stick to your budget, you will get caught up and your credit will recover with time. Now that you actually have control over your expenses and you know to the day of every month what you earn and what you pay, you can then look at some alternatives if you cannot get current before a creditor stops waiting and is beginning to take action against you.

Once you have the budget process mastered and you are following your budget, you won’t have to say “my bills are high”.

Second thing – rebuilding credit

Rebuilding credit is essential. There are many points beyond your control that could have contributed to you’re getting behind on your bills and your resulting bad credit ranking – losing your job, an illness or a divorce. The most vital thing is to recognize what is within your control that got you into difficulty and ensure that you don’t repeat the same mistakes twice.

There are many strategies that you can use to restore your credit score. Here are a few suggestions:

  • Continue with the budget plan I showed you above and continue to pay down your debt.
  • Pay your expenses in a timely manner
  • Contact a creditor instantly if you are having a problem making payments to advise them and work out a payment plan that you can honour.

If you do not qualify for any type of loan, apply for a secured credit card and stop using the normal credit cards that got you into trouble.

Third thing – credit counselling

The first two things I have mentioned are for those who can do it on their own. If you discover yourself experiencing money problems and feel that you need the help of an expert, credit counselling is a great place to start.

A certified credit counsellor professional, can look at your current situation and offer you many alternatives for taking care of the debt.

Credit counselling can solve debt problems. It will also give you the skills to properly budget, pay down your debt and then go on to live debt free. Credit counselling solutions consist of the budgeting process and credit repair that I have already talked about. It also will include lessons on how to use debt wisely. It may also include a proper debt administration program.

Debt administration programs are made to aid you to repay debt. You enlist willingly in a debt administration program; it is not court mandated. When you enlist, a debt counsellor will contact your creditors and ask for their participation in lowering your debt. Your lenders might agree to decrease the amount of debt owing or eliminating or reducing the interest owing. Not all financial debts are covered under a debt monitoring program. Secured debts are generally not included. This is because the creditor can repossess the house or car if you do not make your payments.

One word of caution. We have had cases where certain debt administration firms failed to provide any type of purposeful solution for the people. They charged costs and didn’t give any kind of results. We suggest that you contact what you believe to be a reputable credit counselling firm, you do not retain them until after getting and vetting a couple of references of people who have gone through the program you are considering and you receive positive reviews.

Fourth thing – debt consolidation

Debt consolidation is a loan that allows you to settle all your financial obligations to several or all of your lenders simultaneously, leaving you with just one loan payment. Your debt consolidation loan interest rate must be less than the average interest rate of the debts you are settling.

Not all debts can be included in a debt loan consolidation financing. Secured financial debts like your home mortgage or car loan cannot be included; however unsecured debt like credit card debt and other regular monthly bills that you are now behind on can be.

In order to qualify for a debt loan consolidation, you will require to have an acceptable credit score and sufficient income to show to the lender that you can make your new month-to-month payment in addition to your other regular monthly expenses. Debt consolidation is something you ought to consider before you are in more significant financial troubles. If you have a poor credit score you will certainly not qualify.

There are many benefits to a debt loan consolidation financing that include yet are not limited to:

  • Interest rates are less than the rates of interest on credit cards
  • Your unsecured creditors will be paid in full
  • You will have the benefit of making only one monthly payment
  • You ought to be able to keep a good credit report rating

Fifth thing – consumer proposal

Your financial problems may have gotten to the point where you just don’t have enough time to get current using one or a combination of the 4 things I have already explained. Worse, you may have gotten breathing room and accommodation from your creditors. However, you were not able to keep current on your new payment plan. If this is the case, do not fret because there is a solution.

By using a licensed insolvency trustee (formerly called a bankruptcy trustee) (Trustee), you can reach a binding deal with your creditors to settle your debts at less than the amount you owe in total. The process for this debt settlement plan is called a consumer proposal.

Consumer proposals are options to avoid bankruptcy. A consumer proposal is available to people whose total financial debts do not go beyond $250,000. This limit is not including financial obligations for mortgage or line of credit loans registered against your principal home.

Consumer proposals have formal rules governed by the Bankruptcy and Insolvency Act (BIA). Dealing with a Trustee you make a proposal to:

  • Pay your creditors a percentage of what you owe them over a specific time period (not more than 5 years).
  • Extend the time you need to pay off the debt.
  • It could be a combination of both.

Payments are made to the Trustee who is the administrator of your consumer proposal. The Trustee then uses that money to pay each of your creditors their part of the payments.

The advantages of a consumer proposal are:

  • You maintain all of your possessions
  • Collection actions against you by unsecured creditors, such as garnishments are stopped
  • Unlike informal debt settlement, the consumer proposal is a legal process where every one of your creditors must heed your restructuring
  • You do not have to claim bankruptcy

Sixth thing – bankruptcy

If you have left things too late, or other reasons why none of the 5 things I have already described will work for your situation, then the sixth thing is bankruptcy. Personal bankruptcy is meant to allow the honest but unfortunate person shed themselves of their debt. That way you can start over fresh and new.

Our goal as a Trustee is to ensure that you understand the bankruptcy process and how it can be used to get your life back on track.

We will first help you understand the 5 things I have already described that might be available to you to avoid bankruptcy. If bankruptcy is the only solution, we will guide you back on the roadway to financial health and wellness. We design solutions to ease the stress you meet and bring you:

  • Relief from bothering calls from debt collectors.
  • Freedom by extricating you from garnishments.
  • Provide you the ability to live better than just hanging on one paycheque to the next.
  • Improve your credit scores.
  • Give you an improved and enhanced wellness and well-being.

My bills are high: Do you have too much debt and need help?

If so, call the Ira Smith Team today. We have years as well as generations of experience aiding individuals and companies needing financial restructuring. As a licensed insolvency trustee, we are the only professionals accredited and followed by the Federal government to provide debt restructuring options.

You can have a no-cost appointment for us to gather the necessary information to advise you on how to fix your debt difficulties. We can end your pain so that you will begin your clean fresh start, Starting Over Starting Now.

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20444″]

Categories
Brandon Blog Post

USEFUL TIPS FOR SAVING MONEY CANADA: THIS PRO ATHLETE TEACHES US

tips for saving money canada

If you would prefer to listen to an audio version of this tips for saving money Canada Brandon’s Blog, please scroll down to the bottom of this page and click on the podcast.

Tips for saving money Canada: Introduction

I have written a few blogs about professional athletes who have made a lot of money in their athletic careers, but who have nothing to show for it after retiring from sports. Worse, they have run into financial trouble. I am very happy to be able to write a blog about a financially savvy NFL player.

Some of the blogs I have written about very rich people’s financial disasters are:

Tips for saving money Canada: Saving vs. savings

The word saving is different from the word savings. The former describes the act of boosting one’s assets, where the latter describes one part of one’s assets. Savings are generally invested in interest-bearing accounts, stocks, bonds and/or real estate.

Saving describes a task happening gradually, from your salary or wages, where financial savings describes something that exists at any given time. Reducing your expenses is also a part of savings. There are many blogs on money saving tips for families and money saving tips for students.

Tips for saving money Canada: Brandon Copeland

I understand that debt and a lack of savings is a big problem for many people. There are many Canadians living paycheque to paycheque Yet it is entirely repairable if the money saving tips Canada information is taught, learned and then followed. That is why I was so impressed by New York Jets linebacker Brandon Copeland. I’m not a Jets football fan, however, he really inspires me.

Twenty-seven-year-old Brandon Copeland knows all about saving and savings. He recognizes that his football profession has an expiration time. It is a certainty that football is going to be over one day, the NFL star informed ESPN in 2017. That’s why Copeland is thinking about his future all the time. The Wharton School graduate spent two summertimes interning at an investment bank while in college. He took an offseason job on Wall Street.

He also has experience flipping homes and opened a property firm with his better half in 2015.

Tips for saving money Canada: Tips for saving money Canada: What he teaches

Brandon Copeland grew up in an extremely modest family. Therefore he really did not recognize a great deal about financial matters when he became a young adult. He studied and learned about it on his own. He really did not simply quit there.

Every Monday evening in the offseason he instructs a university course on financial literacy. His objective is to educate a lot of people about finances. He wants to shorten the gap between the rich and the poor. He understands that’s a huge objective yet if you think of it, he has already accomplished a goal that most can’t; making it into the NFL!

He is teaching a financial literacy seminar called “Life 101,” at his alma mater, University of Pennsylvania. The program covers the realities of life all of us need to deal with like:

Tips for saving money Canada: How it all started

He and a previous teammate were speaking on cash mistakes and what they want. They had actually recognized it in their early 20’s. That is how he came up with the suggestion for a course. “I don’t care if you’re an engineering student, a nursing student or if you’re going to build rockets when you grow up or if you’re going to sweep floors,” he said.“You’re going to have to use something in this class”.

While Copeland is the very first to admit he is not an expert in financial proficiency, on the first day of the class he tells the class that he is NOT a financial professional in all of this, but no person really is. He told the Wall Street Journal he’s cautious with his money. “I’ve literally hoarded money,” he said.

He is saving nearly 60% of his post-tax salary. It goes towards safe long-term investments. Another 30% goes towards savings. He lives off the remaining amount. Brandon Copeland said anything he can go into savings and he invests it. He feels that he has to a point where he has enough where if football is over today, he has more than enough to take care of himself and his family.

You don’t have to be a millionaire to pay yourself first

Copeland admits that his income is well above that of the average American. He says that you don’t have to be rich to pay yourself first. He strongly believes that the more you can set aside, the better off you will be. It ends up paying large dividends thanks to compound interest.

Many experts recommend following the rule of personal finance that says 50% of income goes to necessities like rent and groceries, 30% towards discretionary spending and 20% towards saving.

If you can set aside 90% like Copeland is more power to you. Interesting fact. Bill Belichick got his first job in the NFL at age 23. It paid $25 a week.

Do you have too much debt and not enough savings?

Do you have extreme debt? Are you stressed out because you are living paycheque to paycheque and have no savings? Is the tension, stress, anxiety, and pain of your debt adversely affecting your health and wellness? Do you require a fresh kick-start but don’t understand where to begin?

If so, call the Ira Smith Team today. We have years as well as generations of experience assisting people and businesses needing financial restructuring. As a licensed insolvency trustee, we are the only experts certified and supervised by the Federal government to provide financial restructuring and debt settlement options.

Call the Ira Smith Team today to see to it that we can begin helping you. We will swiftly return you into a healthy and balanced worry-free life. We can develop a debt negotiation strategy built simply for you to avoid bankruptcy.

You can have a no-cost consultation to assist you to repair your debt problems. We find your pain points and give you the plan to end them in your life. This will definitely permit you to start a new beginning, Starting Over Starting Now.

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20409″]


Categories
Brandon Blog Post

DO BANK OF CANADA INTEREST RATE HIKE DATES AFFECT YOUR MONETARY POLICY?

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20400″]

Bank of Canada interest rate hike dates: Introduction

I have recently written blogs on debt help and signs you need bankruptcy help. I have ended recent blogs with a question: “Are you worried that the future interest rate hikes will make presently affordable commitments entirely unmanageable?”. So, I thought I would write this blog on Canada interest rate hike dates and what it all might mean in 2019.

Bank of Canada interest rate hike dates

The Bank of Canada (BoC) scheduled dates for the interest rate announcements for 2019 are as follows:

  • January 9
  • March 6
  • April 24
  • May 29
  • July 10
  • September 4
  • October 30
  • December 4

Bank of Canada interest rate hike dates: 2018

In 2018, it was expected that the BoC would raise interest rates slowly towards the end of 2018 and into 2019. The BoC has actually hiked its trendsetting rate of interest, which affects borrowing expenses across the economic climate, five times since the mid-2017, up from a reduced amount of 0.5 percent. The BoC interest rate stands at 1.75%. It was raised to that level in October 2018 and has not risen since.

Bank of Canada interest rate hike dates: 2019 issues

So the BoC on March 6, 2019, decided to keep its target for the overnight rate of 1.75%. Let me explain the main reasons why.

First, there is a slowdown in the worldwide economic climate. It has actually been extra obvious and more widespread than what they were preparing for. It is much more obvious and a lot more widespread than what the BoC was projecting as recently as January 2019! The higher adverse impact on the global economic situation affected their choice.

Second, global trade stress and unpredictability are weighing heavily on self-confidence and economic activity. There is tension worldwide on the trade front between several different scenarios, including Brexit and nations. This results in weakened consumer self-confidence and the confidence of the total worldwide economy. If the China/USA trade war is settled, the world economic scene might improve a bit.

Domestically in Canada, there are reasons they required to keep the BoC rate where it was:

  1. Exports fell short of expectations.
  2. Business investment did not reach the anticipated level.
  3. Consumer spending was weak.
  4. The housing market was soft.

Consumer spending is a big part of GDP and the cost of living in Canada. As well it has a huge influence on the Canadian economy. The Canadian real estate market is a high ticket item and there are plenty of industries that are affected by and depend upon a vibrant housing market. Each of those measures was either short of expectations or soft on its performance.

Based on both these worldwide and made in Canada influences that I have pointed out, the BoC determined they were going to keep their interest rate and not hike it. As recently as October 2018 the financial press was reporting that rates will gradually be climbing throughout 2019. Increased unpredictability is now introduced on the timing of future rate increases.

What about the rest of 2019

We might now go all of 2019 without any price rise. It depends on future occasions. I believe that there are four main variables to watch:

Core inflation continues to be near 2 percent. The Canadian consumer price index reduced to 1.4 percent in January, greatly as a result of lower oil prices. The BoC expects the cost of living index to be somewhat below the 2 percent target for the majority of 2019, reflecting the influence of short-lived variables, including the drag from reduced energy prices and a bigger output gap.

We will certainly see exactly how some of these variables may transform between now and the spring. For the July and succeeding rate statement dates, we will certainly have to see what the spring real estate market looks like. As I stated above, the real estate market is a large driver of both housing spending as well as consumer spending.

What it means for you

The reality is that the BoC overnight rate holding firm is great information if you were going to be buying a house this year. Five year fixed mortgage rates have actually declined somewhat in 2019.

If you have a variable rate home mortgage or line of credit/home equity credit line, the rate hold is likewise excellent news for you.

What about you?

Is the tension, stress, anxiety, and pain of your debt negatively influencing your health and wellness?

If so, call the Ira Smith Team today. We have years as well as generations of experience aiding individuals and companies needing financial restructuring. As a licensed insolvency trustee, we are the only professionals accredited and followed by the Federal government to provide debt restructuring options.

Call the Ira Smith Team today to make certain that we can begin aiding you. We will rapidly return you right into a healthy and balanced worry-free life. We can develop a debt settlement strategy simply for you to prevent bankruptcy, where we can also make the interest clock stop ticking away at you. By doing this, all your payments go only against the principal balance owing.

You can have a no-cost appointment for us to gather the necessary information to advise you on how to fix your debt difficulties. We can end your pain so that you will begin your clean fresh start, Starting Over Starting Now.

bank of canada interest rate hike dates

Categories
Brandon Blog Post

TWO INCOME TRAP OF SEN. WARREN

two income trap

If you would rather listen to the two income trap blog audio file, please scroll down to the end for the podcast.

Two income trap: Introduction

In the last 50 years, women have entered the labour force in real numbers. This did not result in families having a much easier time of it economically. A great number of people thought it would because a family now had two full-time income earners. Financial troubles might if anything be much more extensive among two income households today. This is called a two income trap.

Two income trap: Senator Elizabeth Warren

I recently read an article on the United States Senator Elizabeth Warren. I had not been actually familiar with her history prior to reviewing the write-up. Turns out that she was a lawyer who focussed on bankruptcy legislation. She was a professor at the Harvard Law School.

Senator Warren’s daughter, Amelia Warren Tyagi, is an entrepreneur and management consultant. They co-authored a book “The Two-Income Trap: Why Middle-Class Mothers and Fathers Are Going Broke“. It was first released in 2003 and an updated version was released in 2016. The book is a sociological review of exactly how American households and life have developed from the 1960s to contemporary times. Although it is a testimonial of American life, I think the same concepts and conclusions can be related to Canada’s middle class too.

Two income trap: The rise in middle-class insolvencies

One reality that bothered the writers was that by the early 2000s, bankruptcies in the middle class became greater than in any other American socio-economic group. To put it simply, when considering the family members that are declaring bankruptcy, it’s not the extremely poorest or the really wealthiest. It actually has to do with the middle class and the kind of financial difficulties they meet.

The writers wished to attempt to clarify why much more middle-class households, making even more than ever previously, saw a 500% rise in individual bankruptcy filings from the very early 1980s to the very early 2000s. The writers likewise keep in mind that along with personal bankruptcies, home mortgage foreclosures were up greater than 3.5 times than in the very early 1980s. This is prior to the 2008 economic disaster mess!

Two income trap: The financial disintegration of the middle-class household

Their study began with a solitary reality. The possibility that a family with youngsters would wind up in bankruptcy is more than families without children. They uncovered that households that have youngsters in the family are almost 3 times more likely to wind up declaring bankruptcy than households that do not have children.

The writers think it is really vital to comprehend the problems triggering middle-class economic issues. This is due to the fact that they discovered that 2 out of every 3 households that applied for bankruptcy have actually had a real job loss or loss of income prior to their declaring bankruptcy.

Someone’s lost a job; a person’s had a major downturn when it comes to households where both the husband and wife work. Sometimes both of them have actually lost their job before bankruptcy. So we’re actually talking about individuals that are not just way down on the earnings side. They had no financial savings or emergency money fund to draw on when the unanticipated calamity struck. Stating it a different way, households were damaged attempting to have a middle class lifestyle!

This concern fascinated the writers. We can comprehend the young and careless declaring bankruptcy. We can also recognize a tale about seniors in debt that states decreasing health, limited revenue, no potential to make extra in the future and insufficient funds for retired life will certainly have financial issues. Nevertheless, in the case of seniors in debt, the reasons for their financial difficulties probably began a very long time ago. With restricted earnings and no financial savings to draw on, revealed the concerns which already existed.

Two income trap: The newer generation middle class

Insolvency stories about women and men working and raising children are normal today, but this was not so in the very early 1980s and earlier.

In those days, middle-class stories were not about creating debt to purchase consumable or lifestyle items they cannot afford. Stories about the current middle class in financial trouble inevitably show similar primary factors why these family members wind up bankrupt. They are attempting to spend on not only food and clothing but other costs that have become family fixed costs, such as:

Middle-class families need to have 2 automobiles when both mother and father are in the labour force. The spread of suburban life families have out of necessity opted to get more space for the dollar and overall affordability, also demands being a 2 car family. By the time they make all their fixed cost payments, those two income households think about what was supposed to be their financial success tale.

They have much less cash left over than their one-income dads’ or grandfathers’ households had. It appears that as our society modernizes and allows people to do a lot more, the ambitions of middle-class families do not always come to fruition. The middle class has been and continues to shift. The middle-class size has reduced compared to the 1970s. Families have been either moving up or down. On a net basis, the middle class has not been growing.

This actually does not amaze me. When you have children your expenditures jump astronomically. As lately as the very early 1970s, a Canadian household had buying power on one income. It certainly gave a middle-class way of living. What took place in the 1960s and 1970s, is one income sufficed to sustain a household in what was a typical and comfortable middle-class life.

It absolutely was middle class; it was right in the centre. You may have needed to clip coupons to save money, yet you were buying your food at grocery stores, not going to a food bank. Your home could have been small, yet it was your own and you had the want and ability to hive off savings from your regular employment income to pay off your only mortgage quicker.

Two income trap: So what has changed?

That generation recognized exactly how to stick to a spending plan. They were more successful than their parents’ generation. They learned lessons from their parents about: (i) money; (ii) budgeting; (iii) saving for an objective; and (iv) understanding and being OK with if you cannot pay cash now for something, you simply do not buy it.

Now with both parents in the labour force, expenditures for dining in a restaurant more often, more expensive clothing, gas for the two cars are instances of regular expenditures the modern family has. One or two generations ago families did not have the same level of those kinds of expenses. Modern families spend a lot more than simply for what was the core fundamentals. We constantly recognize that having children is costly. Yet something has taken place in a single generation. The expense of living for a family with kids has actually made what once was a common middle-class life out of reach for the ordinary typical income earner.

Nowadays, the level of a household’s fixed costs is not how an economist would look at costs as compared to the income level. Rather, it is how people today understand what a two income family’s costs realistically are at the same income level. In modern-day culture, people are dining in restaurants a lot more, have home appliances and communication devices that did not exist 1 or 2 generations earlier. Housing expenses have boosted considerably. This is the brand-new facts of life for the contemporary culture household.

Two income trap: So here is the key to release you from the trap

Canadians have a financial literacy problem. Lots of people assume that some are born rich while others are not. The fact is that in most cases, those that are well off simply have a much more reasonable understanding on costs and how to live within one’s means. They also have willpower. In the past, people thought first if they could actually afford something before they spent their money on it. They don’t just look at the interest rate and monthly payment incurring that new debt will have.

I have written several blog posts alerting Canadians about the need to budget and plan thoroughly to make sure that expenses do not surpass income. A spending plan requires to consist of savings; both for an emergency reserve and for retired life. Those that do not do so are more likely to be in financial trouble when an unforeseen occasion happens. It is because they have absolutely nothing to draw on in lean times.

There are many ways to start early in life to avoid financial disaster. If it sounds familiar, that’s due to the fact that they are. Nonetheless, yet few people value them. That’s partly due to the fact that they weren’t taught in either the home or in the schools.

Financial proficiency, like civics education and learning, requires to be a demand in all primary school, secondary school as well as university curricula.

So the key to being released from this trap is twofold:

  • behaviour modification; and
  • financial literacy being taught at all education levels

Two income trap: Are you caught in the two-income trap?

Are you caught in the two income trap? Worried that future interest rate hikes will make presently affordable debt entirely out of reach? Is the discomfort, stress, and anxiety too much debt brings on negatively affecting your health and wellness?

If so, call the Ira Smith Team today. We have decades and generations of experience helping people and companies needing financial restructuring. As a licensed insolvency trustee, we are the only professionals licensed and supervised by the Federal government to supply financial restructuring services.

Call the Ira Smith Team today to make sure that we can begin aiding you to return right into a healthy and balanced and well-balanced, worry-free life.

We will provide a no-cost consultation to aid you to resolve your money troubles. We understand the pain debts and financial distress triggers. We can end it from your life. This will certainly allow you to begin a clean slate, Starting Over Starting Now.

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20141″]

Categories
Brandon Blog Post

3 RECENT DEBT HEADLINES

[monkeytools msnip=”http://monkeyplayr.com/playr.php?u=5173&p=20127″]

Debt headlines: Introduction

There have been three recent debt headlines that have attracted a lot of people’s attention. In this Brandon’s Blog, I discuss all three.

Debt headlines: Bankruptcy statistics

On January 4, 2019, the Office of the Superintendent of Bankruptcy Canada issued its bankruptcy statistics report “Insolvency Statistics in Canada—November 2018”. In my blog, BANKRUPTCY STATISTICS CANADA 2018: SCARED OF INSOLVENCIES IN CANADA OR DEBT?, I described the statistics. Many financial writers started to forecast doom and gloom. However, in my blog, I comment that I don’t see it that way. Insolvency filings in November 2018 were down from October 2018. The business writers quoted the statistic that there was a 5.2% increase in November 2018, compared to November 2017. However, insolvency filings have been unusually low for close to 10 years. So the increase really is not a big deal.

The actual problem is not these stats. Instead, it is the historically high degree of Canadian house debt collected when rates of interest went to near almost 0%. Since we stay in a slowly boosting rates of interest environment for the near future, not every person or business will be able to carry their high debt. This will lead to more insolvency filings.

Debt headlines: 46% of Canadians on the verge of bankruptcy as rates increase: Study

I have written before about Canadians and their debt load. Personal debt loads are of some worry. There’s brand-new information that casts a brand-new alarming light on the state of Canadians’ personal balance sheets.

A current study reveals that 46% of Canadians are on the verge of bankruptcy as interest rates increase. I begin by stating a word of caution. The survey size was a small pool so I don’t want to generalize. Canadians have a great deal of debt. What does that tell us about what these people are saying?

This really did not occur overnight. These are long-lasting financial obligations that have been gathered over a long time. The weight of them is actually having an influence. These are individuals that live paycheque to paycheque.

Well, these people are claiming that 46% who answered the survey would not have enough cash or are within $200 or much less to manage their debts and expenses at the end of the month. If something shows up that can interfere with that whether its rates of interest going higher, they might lose their job, or they might have unanticipated emergency costs. So what this informs us is that practically half of Canadians that were surveyed are truly living really near to the margin.

Numerous people do live in this way. Having debt repayments that stay in the mix since that is something that is non-negotiable, will certainly increase in time if you do not resolve it. Rates of interest will certainly increase. Do we understand what percentage of these individuals is facing that? I’m going say a fair number.

The reason I say this is due to the fact that if you return to the start of the monetary crisis in 2008, the Bank of Canada decreased rates of interest in an initiative to boost the economic climate. Ten years actually. I recognize rates of interest have actually begun to go higher however when you’re in this low-interest atmosphere you can carry a lot of debt.

People have. I’m not speaking about the tiny expenses placed on a charge card. I am speaking about paying an astronomically high price for a house in a rising real estate market, not having the ability to manage those home mortgage repayments, tackling that costly debt using your charge card.

43% of those surveyed stated they are sorry for some of the debt that they incurred. They would certainly enjoy a getaway today however if you cannot pay for it that vacation credit card debt is still there.

Just how concerned do you get when you hear that rates of interest are increasing? You are most likely to need to be getting ready to get your affairs in order.

Debt headlines: Canadian financial institutions might drop by ‘a minimum of’ 50% says a US Hedge Fund


Canadians following our markets look to see what’s happening with the Canadian financial institutions. There is one short seller following the Canadian banks. Denver-based Crest Capital believes the Canadian real estate market will lead Canada into an economic downturn. Nonetheless, the huge 6 financial institutions have actually taken care of proving the cynics incorrect in the past.

Kevin Smith is the founder and CEO of Crest Capital, a hedge fund with $53 million in assets under administration. Crest Capital also has an excellent track record. He is shorting the Canadian financial institutions and thinks now is the moment. He thinks it actually boils down to China.

Kevin Smith thinks that:

  • there is a real estate bubble in Canada;
  • housing debt to GDP has been blown up and been trouble for a time;
  • house prices have increased for a very long time; and
  • the cash streaming in from China that has actually pushed up housing prices and
  • compelled Canadians themselves to extend to purchase real estate.

He believes the China credit bubble is ultimately going to break. China has this credit bubble which has actually been taking place for years. The cash has actually been spilling around the globe yet he believes the funding streams currently from China are truly beginning to run out and perhaps also turn around. There has actually been a lot of cash leaving China right into Canada. This is what has aided the Canadian real estate market and the economic climate.

He said that we are 10 years right into a worldwide financial cycle. He thinks Canada’s personal high debt to GDP ratio will leave the financial institutions holding the bag on this debt trouble. I do not know if he is right, yet that is what he is banking on.

Debt headlines: Can you afford your debt payments with a higher interest rate?

Do you have too much debt? Are you worried that the future interest rate hikes will make presently affordable commitments entirely unmanageable? Is the discomfort, tension and anxiousness presently detrimentally affecting your health and wellness as well as health?

If so, speak to the Ira Smith Team today. We have decades and generations of helping people and companies looking for financial restructuring. As a licensed insolvency trustee (formerly called a bankruptcy trustee), we are the only experts licensed and supervised by the Federal government to provide insolvency services.

Call the Ira Smith Team today for your free consultation and to make sure that we can begin assisting you to return right into a healthy, balanced, hassle-free life.debt headlines

Categories
Brandon Blog Post

BANKRUPTCY STATISTICS CANADA 2018: SCARED OF INSOLVENCIES IN CANADA OR DEBT?

bankruptcy statistics

If you would rather listen to the Bankruptcy statistics Canada 2018 blog audio file, please scroll down to the end for the podcast.

Bankruptcy statistics: Introduction

On January 4, 2019, the Office of the Superintendent of Bankruptcy Canada issued its bankruptcy statistics report “Insolvency Statistics in Canada—November 2018”. Most of the headlines on this report quoted that Canadian insolvencies rose 5.2% in November 2018. While true, that headline alone could create the impression that we now have runaway bankruptcies in Canada. Nothing could be further from the truth. Let me explain.

Bankruptcy statistics: The latest numbers

Total insolvencies in November 2018 was 5.2% higher than total insolvencies in November 2017. That is what the press has quoted. However, that statistic by itself is meaningless. The complete number of insolvency filings (proposals and bankruptcies) in Canada lowered by 2.5% in November 2018 contrasted to the previous month.

For the 12-months ending November 30, 2018, total insolvencies boosted by 2.0% compared with the 12-month period ending November 30, 2017. This is a fairly modest total increase. Keep in mind that insolvencies in Canada have been at historically low levels for the last 9 years! A total annual increase of 2% from a historic low number is hardly an epidemic.

Consumer insolvencies for the 12-months ending November 30, 2018, increased by 2.0% compared to the 12-months ending November 30, 2017. Consumer personal bankruptcies were down by 5.0%, while consumer proposals were up by 8.4%. The percentage of proposals in consumer insolvencies increased to 55.7% during the 12-month period finishing November 30, 2018, up from 52.4% throughout the 12-months ending November 30, 2017. This means that over half of those Canadians who made an insolvency filing in this time period avoided bankruptcy. This is a good thing.

Business insolvencies for the 12-month period ending November 30, 2018, decreased by 0.6% compared to the 12-month period ending November 30, 2017. The industries with the largest decrease in insolvencies were mining and oil and gas. The industries with the largest increase in insolvencies were building and construction and retail.

Bankruptcy statistics: What is the real issue

The real issue is not these statistics. Rather, it is the historic high level of Canadian household debt amassed when interest rates were at near zero percent levels. Now that we are in a gradually increasing interest rate environment for the foreseeable future, not every person or company carrying high debt will be able to continue meeting their obligations and will have to resort to an insolvency proceeding.

I have written about the dangers of carrying too much debt for many years now. We are now entering the period where the rubber meets the road. Stephen Poloz, Governor of the Bank of Canada, feels the Canadian economy is doing sufficiently well to slowly boost rates of interest. Mr. Poloz believes to be tightening up that a bit. At the exact very same time, the latest insolvency statistics show that the marketplace now tells a story that there may be room for some actual pessimism about the Canadian economy.

Previous Bank of Canada Governor Mark Carney and the former Finance Minister, the late Jim Flaherty, warned the Canadian consumer to place the economy on their back and march it up a high hill. We did and it worked. This is now the outcome of it.

Bankruptcy statistics: Canadian household debt

There’s a good deal of conversation on what that suggests specifically for Canadians. It isn’t that the warnings have actually not been there for a while. The most recent statistics show that Canadian household debt is around 170 percent of disposable income. The regular Canadian owes $1.70 for every single buck of revenue made each year, after tax.

Twenty years ago, the proportion was 100%. So as you can see, there has been a stable climb in Canadians’ cravings for more financial debt. We have among the greatest financial obligation percentage of any of the Organisation for Economic Co-operation and Development participant nations. For those carrying high debt, it is now time to buckle your seat belts as interest rates will continue to rise.

There were indications that the Canadian consumer was thinking of their budgeting. Statistics Canada previously reported that retail sales were slowing down. Now in the latest insolvency statistics, we see that retail is one of the industry sectors that had an increase in corporate insolvency filings.

With rates of interest increasing, so does the cost of borrowing and the cost of maintaining variable rate loans. Fixed rate loans that mature will need to be refinanced at higher interest rates if the loan cannot be repaid in full.

Bankruptcy statistics: Debt in a rising interest rate environment

Do you have too much debt? Does your company have too much debt and is in danger of shutting down? Are you concerned that future interest rate hikes will make currently manageable debt totally unmanageable? Are the pain and stress now negatively affecting your health?

If so, contact the Ira Smith Team today. We have decades and generations of helping people and companies in need of financial restructuring and counselling. As a licensed insolvency trustee (formerly known as a bankruptcy trustee), we are the only professionals licensed and supervised by the Federal government to provide debt settlement and financial restructuring services.

We offer a free consultation to help you solve your problems. We understand your pain that debt causes. We can also end it right away from your life. This will allow you to begin a fresh start, Starting Over Starting Now. Call the Ira Smith Team today so that we can begin helping you and get you back into a healthy, stress-free life.

[monkeytools msnip=”http://memochimp.com/memo.php?u=4931&p=3613″]

Call a Trustee Now!