Categories
Brandon Blog Post

The Debtor Loses The Driver’s Seat: The Rise of Creditor-Launched CCAA Proceedings

Corporate steering wheel symbolizing control in CCAA proceedings of the debtor company.

The Debtor Introduction

At Ira Smith Trustee & Receiver Inc., we hope you are doing well and staying safe in these rapidly changing economic times. We know that the weight of corporate financial distress doesn’t just sit on a balance sheet; it sits on the shoulders of the people, the directors of the debtor company, investors, and creditors, who make these businesses run. We are here to help you navigate these complex waters with clarity and compassion.

The Debtor Key Takeaways

  • The Power Shift: 2026 has seen a definitive shift toward creditor-led and investor-led CCAA proceedings, moving away from the traditional model where the debtor company calls all the shots.
  • The Angus A2A GP Inc v Alvarez & Marsal Canada Inc, 2026 ABCA 156 (CanLII) Decision: A landmark Alberta Court of Appeal ruling in May 2026 has officially cleared the way for equity investors to qualify as “interested persons” under the Companies’ Creditors Arrangement Act (CCAA) to initiate restructuring proceedings, fundamentally changing the “who” and “how” of corporate rescue.
  • Super-Monitors: Courts are increasingly granting Monitors enhanced operational powers, creating a “Super-Monitor” role that provides receivership-level control within a CCAA framework.
  • Reverse Vesting Orders (RVOs): While under higher judicial scrutiny, RVOs remain the “surgical tool” of choice for preserving tax attributes and regulatory licences.
  • Restructuring at Scale: Speed is the new currency. The use of “SISPs-on-steroids” ensures that businesses are moved through the market in weeks rather than months.

For decades, the CCAA was seen as the debtor-in-possession regime. The company in trouble would realize it was sinking, seek court protection, and then propose a plan to its creditors. But as we move through the middle of 2026, that landscape has shifted. We are now seeing creditors, and even equity investors, seizing the wheel.

Whether you are a secured lender in the GTA or an investor looking to protect a failing portfolio company, understanding this “Creditor-Led” era is essential. It’s no longer just about waiting for a proposal; it’s about taking proactive steps to preserve value.


The Debtor Highlights

  • The Angus Manor Decision: A Game Changer
  • The Rise of the “Super-Monitor”
  • RVOs: Surgical Precision or Extraordinary Relief?
  • SISPs-on-Steroids: The Need for Speed in 2026
  • BIA vs. CCAA: A Strategic Comparison for Creditors

The Angus Manor Decision: Why Equity Investors are Now at the Table

In May 2026, the Alberta Court of Appeal released its decision in Angus Manor, a case that has sent ripples through the Canadian insolvency community. Historically, the right to file for CCAA protection was largely the domain of the debtor company itself or its creditors. Equity investors were often sidelined until a plan was actually on the table.

The Angus Manor ruling changed that. The court determined that, in specific circumstances, where management is deadlocked or the board is failing to act in the face of imminent insolvency, equity investors can have the standing to initiate CCAA proceedings.

As a Licensed Insolvency Trustee Toronto, we see this as a vital evolution. It prevents a “burn-down” scenario in which a debtor company’s value evaporates while its leadership is paralyzed. For GTA business owners and stakeholders, this means you have a new lever to pull if your investment is at risk.


The Rise of the “Super-Monitor” Overseeing The Debtor

Professional trustee overseeing complex business restructuring of the debtor company.

Traditionally, a Monitor in a CCAA proceeding is a court-appointed officer (a Licensed Insolvency Trustee) who watches over the debtor company’s finances, assists in formulating the restructuring plan, interfaces with creditors and reports to the court. They are the “eyes and ears” of the judge.

However, in 2026, we are seeing the rise of the Super-Monitor. In many creditor-led filings, the court is granting the Monitor “enhanced powers.” This means the Monitor isn’t just watching; they are often:

  • Approving all major expenditures.
  • Directing the sale process (the SISP).
  • Even overriding the management of the debtor company on key strategic decisions.

This creates a hybrid between a CCAA and a corporate receivership process for GTA creditors. It provides the legal “stay of proceedings” (the freeze on lawsuits) that CCAA offers, but with the tight, professional control of a receiver. If you are a creditor who has lost faith in a company’s management, the Super-Monitor is your best friend.


The Debtor and RVOs: The Surgical Tool under Fire

A corporate shell being cleaned of liabilities through an RVO of the debtor company.

One of the most powerful tools in our 2026 toolkit is the Reverse Vesting Order (RVO). If a regular sale is like selling a car and leaving the debt behind, an RVO is like keeping the car’s registration and history but magically removing the debt from the title.

In an RVO, the purchaser buys the shares of the company. The “bad” parts, the debts and unwanted contracts, are “vested out” into a separate, temporary company that eventually goes bankrupt. This is incredibly useful for companies with complex regulatory licences or tax attributes (like losses that can be carried forward) that would be lost in a traditional asset sale.

However, the courts are becoming more cautious. In 2026, judges are demanding clear evidence that an RVO is necessary and not just a “convenient shortcut” to avoid taxes or environmental liabilities. At Ira Smith Trustee & Receiver Inc., we ensure that any RVO proposal is backed by a rock-solid evidentiary record to stand up to judicial scrutiny.


SISPs-on-Steroids: The Need for Speed

A stopwatch on legal documents symbolizing the urgency of modern SISPs in reorganizing the debtor company.

The days of long, drawn-out restructuring processes are largely over. In 2026, we utilize what we call “SISPs-on-steroids.” A Sale and Investment Solicitation Process (SISP) is the formal way we market the assets of the debtor company, either in pieces or en masse, representing the operating business for sale during insolvency.

Why the rush? Because in a high-interest, volatile market, “time is the enemy of value.” The longer a company stays in CCAA, the more “professional fees” it burns and the more customers it loses. We are now seeing SISPs that launch, market, and close a sale in as little as 45 days. This requires a team that can move fast, with a deep network in the Toronto and Canadian investment communities.


BIA vs. CCAA: A Strategic Comparison for Creditors

When deciding how to handle a distressed company in the GTA, creditors often weigh the Bankruptcy and Insolvency Act (BIA) against the CCAA. Here is how they compare in the current 2026 environment:

FeatureBIA (Receivership/Proposal)CCAA (Restructuring)
Primary GoalLiquidation or debt settlement.Going-concern restructuring or sale.
ControlHigh (Receiver takes over).Traditionally low, but high with “Super-Monitor.”
ComplexityLower; rules-based.Higher; flexible and court-driven.
CostGenerally more affordable for SMEs.Significant; usually for debts over $5 million.
SpeedCan be very fast (liquidation).Fast in 2026 (SISPs-on-steroids).
Shareholder RightsMinimal.Emerging rights (see Angus Manor).

The Debtor Frequently Asked Questions (FAQ)

1. Can a creditor force a company into CCAA in Ontario?

Yes. While it is more common for the company to file voluntarily, a creditor with a significant claim (over $5 million) can apply to the court to have the debtor company placed into CCAA protection if the company is insolvent.

2. What is the difference between a Receiver and a Super-Monitor?

A Receiver generally takes full possession and control of the assets to sell them. A Super-Monitor works alongside or over management within the CCAA process, often allowing the debtor company to keep operating while a sale is finalized.

RVOs are popular because they preserve “intangible” value. If a company has a specific licence to operate in a regulated industry (like cannabis, pharma, or energy), an RVO allows that licence to stay with the corporate entity while the debt is stripped away.

4. How does the Angus Manor decision affect me as a business owner?

It means your investors have a new “safety valve.” If your board is deadlocked and the business is failing, a shareholder investor might be able to go to court to start a restructuring, even if the board doesn’t agree.


Why This Matters to You and The Debtor Company

Understanding these shifts isn’t just for lawyers and bankers. It’s for the business owner who is worried about their legacy, the investor trying to save a portfolio, and the creditor trying to recover what they are owed.

At Ira Smith Trustee & Receiver Inc., we don’t just see numbers; we see the “Starting Over, Starting Now” potential in every crisis. By staying at the cutting edge of BIA vs CCAA proceedings Toronto, we give our clients the best possible chance to emerge from financial distress with their dignity and their future intact.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future. Call us now.

Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

, , , , , , , , , , , , , , , , , , , , , , , , , , –

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Brandon Smith is a Senior Vice-President at Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving clients across Ontario. His experience includes consumer insolvency and complex court-ordered receivership and corporate bankruptcy administration, giving him practical insight into navigating challenging financial situations to achieve optimal outcomes for businesses, creditors, and professionals. Brandon stays current with landmark developments in Canadian insolvency law, ensuring his clients benefit from a cutting-edge understanding of their rights and options.
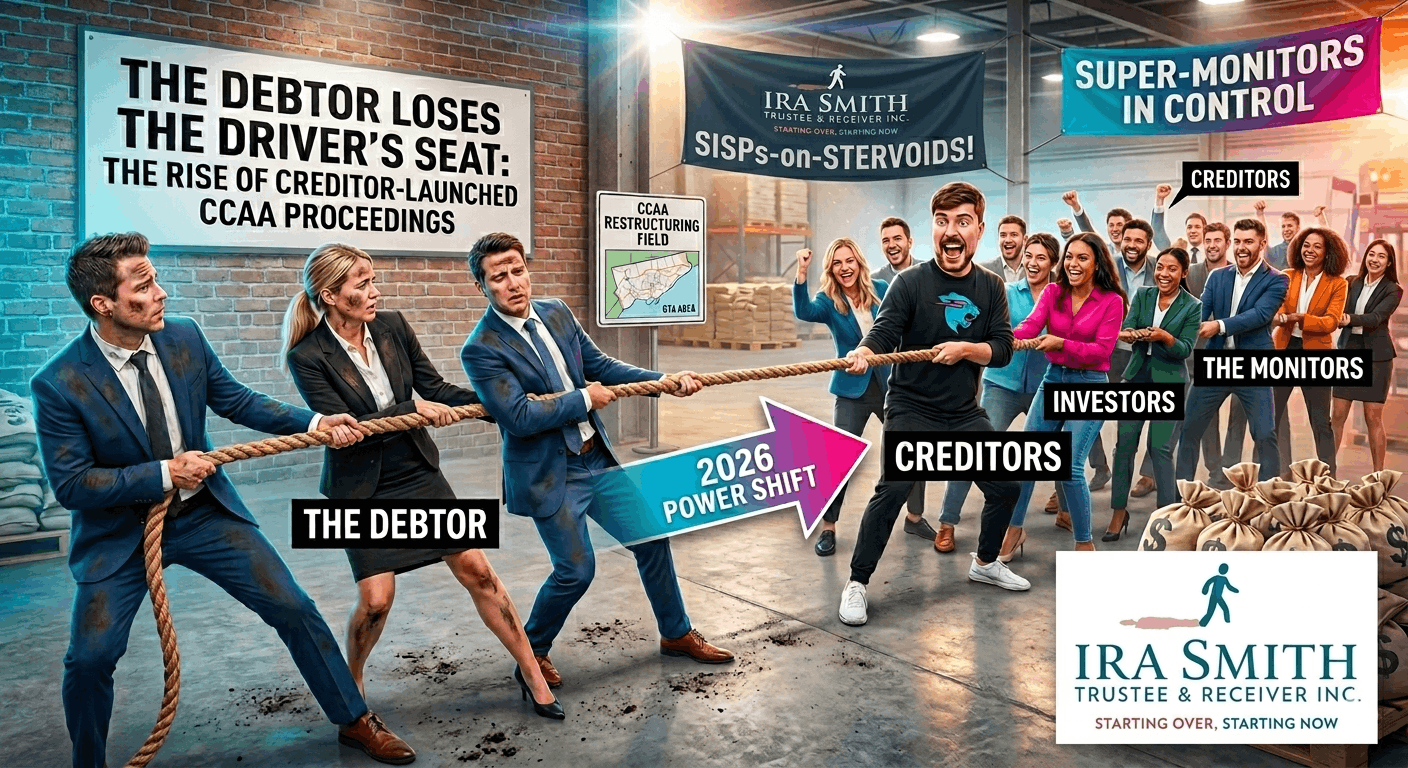
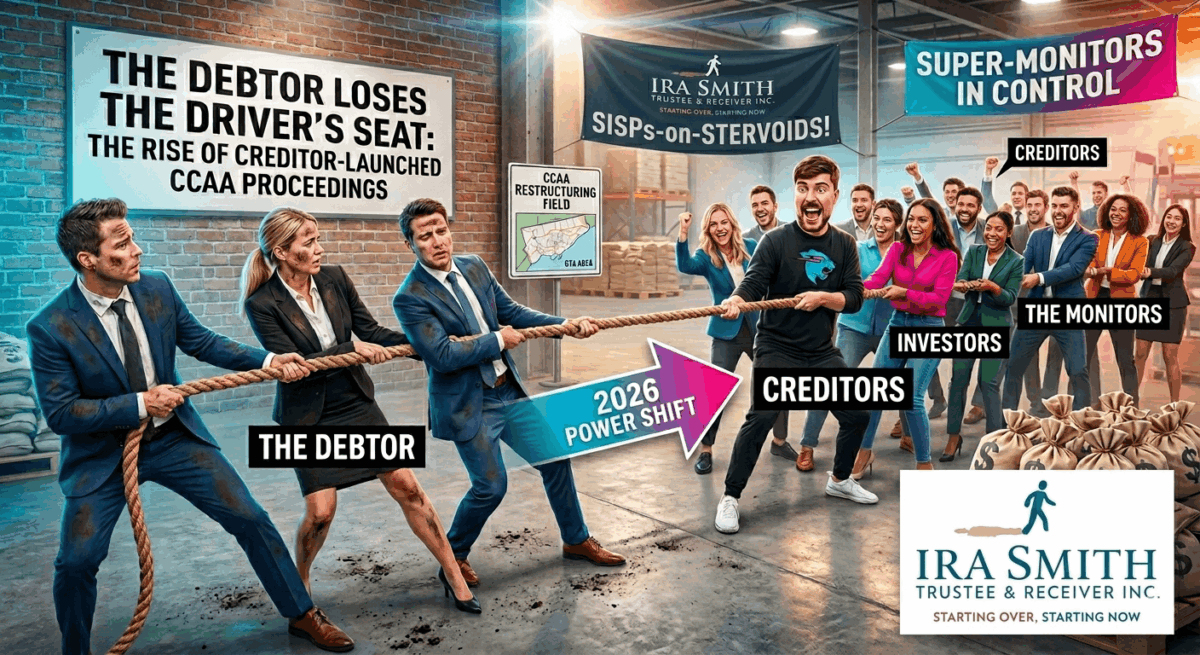
An image of a tug of war between the debtor company, creditors and shareholders on a CCAA reorganizataion administered by the Monitor Ira Smith Trustee & Receiver Inc.

#CorporateRestructuring #CCAA #TorontoBusiness #InsolvencyLaw #DebtRelief #CreditorRights #thedebtor #BIA #IraSmithTrustee #Companies’CreditorsArrangementAct #AngusManorDecisionAlberta

Categories
Brandon Blog Post

CONSTRUCTION LIEN ACT: CAN YOU TRUST AN INSOLVENCY PROCEEDING?

The Ira Smith Team is absolutely operational and both Ira, as well as Brandon Smith, are right here for a telephone appointment, conference calls and also virtual meetings.

Stay healthy and safe everybody.

Introduction

Matters involving the Construction Act, R.S.O. 1990, c. C.30 ( formerly known as the Construction Lien Act) is very complex. In this Brandon’s Blog, I will use the term that laypeople are most familiar with, being the former name of the provincial legislation.

Construction law is a specialty unto itself. It gets even more complex when a company involved in construction enters insolvency proceedings. There is normally a conflict in these kinds of files between:

In this Brandon’s Blog, I describe a recent 5 member panel decision of the Court of Appeal for Ontario who had to decide whether a trust created under section 9(1) of the provincial Construction Lien Act survives a sale by the Monitor in an insolvency proceeding under the federal Companies’ Creditors Arrangement Act (CCAA).

The case is Urbancorp Cumberland 2 GP Inc. (Re), 2020 ONCA 197 (Urbancorp). The matter was heard on October 3, 2019. The unanimous decision was recently released on March 11, 2020.

Some background matters

Before getting into the actual case, there are two background matters that I should first explain. When I thought of these concepts and then the decision this way, it made it easier for me to understand.

The first issue is the types of insolvency proceedings. There are essentially four types of insolvency proceedings. Some are not mutually exclusive. Each one of them can be used for the assets of the insolvent debtor to be sold. I break down the insolvency proceedings list in this way:

  1. Using the restructuring provisions of either the Bankruptcy and Insolvency Act (Canada) (BIA) or CCAA.
  2. A bankruptcy administration under the BIA.
  3. A secured creditor taking enforcement proceedings on the assets subject to its security through the security itself by privately appointing a Receiver or Receiver and Manager.
  4. A secured creditor making an application to the Court that it is just or convenient for the Court to appoint a Receiver to act on behalf of all creditors in stabilizing an insolvent debtor situation and to come back to Court with recommendations on how to proceed, including the sale of assets.

The second issue has to do with trust claims under the Construction Lien Act. There are several sections in the legislation dealing with trust claims. As I stated above, it is a very complex topic. So, I am going to only focus on the one that is the subject matter of this case. That is section 9(1) of the Act. That section deals with a trust claim against the vendor of the construction assets. It states:

“9 (1) Where the owner’s interest in a premises is sold by the owner, an amount equal to,

(a) the value of the consideration received by the owner as a result of the sale,

less,

(b) the reasonable expenses arising from the sale and the amount, if any, paid by the vendor to discharge any existing mortgage indebtedness on the premises,

constitutes a trust fund for the benefit of the contractor. R.S.O. 1990, c. C.30, s. 9 (1); 2017, c. 24, s. 9, 70.

Obligations as trustee

(2) The former owner is the trustee of the trust created by subsection (1), and shall not appropriate or convert any part of the trust property to the former owner’s own use or to any use inconsistent with the trust until the contractor is paid all amounts owed to the contractor that relate to the improvement. R.S.O. 1990, c. C.30, s. 9 (2).”

The distinction here that I want you to keep in mind is the words in the very first line “Where the owner’s interest in a premises is sold by the owner…”(emphasis added).

Now for the case.

The Urbancorp Construction Lien Act case

This case deals with Urbancorp and related companies that developed and was building a residential condominium project. Urbancorp was insolvent and filed first a Notice of Intention to Make A Proposal under the BIA. The proceedings were later converted by the Court into proceedings under the CCAA. The insolvency proceeding was in both cases under a Federal restructuring statue. The Court appointed a Monitor to oversee the insolvency administration. Through various Court applications and court orders, the Monitor was given the authority to market and sell the condominium assets. The Monitor did so.

Now the cash the Monitor received from the sale stood in place of the original condominium assets. Subcontractors brought an application before the lower Court claiming they had a valid trust claim under the Construction Lien Act. The lower court judge carefully reviewed the evidence and prior decided cases and came to the conclusion that the subcontractors did not have a valid trust claim against the assets. The subcontractors appealed the lower court’s decision.

In addition to appealing the lower court’s decision, they also raised with the Court of Appeal a constitutional question that comes up many times. The constitutional question is, does federal law always take priority, or trump (with a small “t”!!) provincial law. This is otherwise known as the concept of paramountcy. Stated slightly differently, the issue can be stated as does section 9 of the Construction Lien Act remain to have application after a bankruptcy or initial order under the CCAA? The Attorney General of Ontario also stepped in on that part of the case.

The Court of Appeal accepted this constitutional question to be decided so there were now two issues before the Court of Appeal; the issue of paramountcy and the trust claim issue.

The constitutional question

The Court of Appeal went through a very thoughtful and careful analysis. It confined the constitutional question to the facts of this case. The court concluded in this case:

  1. The trust created under section 9(1) of the Construction Lien Act is a valid trust under provincial law.
  2. The BIA excludes from property available to the creditors any property held in trust.
  3. Therefore, this provincial trust can be effective when there is an insolvency proceeding under the BIA.
  4. Similarly, with the CCAA legislation, it follows that a section 9(1) provincially created trust might be effective when the insolvency administration is subject to the CCAA.

Now for the actual appeal

The Appeal Court now turned to the lower court judge’s decision that a section 9(1) of the Construction Lien Act trust did not apply in this matter. The five-member panel again went through a careful analysis of the statute and the case law. They spent a lot of time reviewing an earlier Court of Appeal for Ontario decision which the lower court judge relied upon in his decision.

The Court of Appeal highlighted that in that decision the lower court relied upon, the owner, being the insolvent debtor, had no interest in the asset that the subcontractors were claiming a trust claim against. The reasons were:

  1. The asset was part of a package of assets sold.
  2. There was a secured creditor who had security over all of the assets of the developer.
  3. The proceeds less the expenses to produce the sale were less than what was owed to the secured creditor.
  4. The court allowed the cash from the sale to stand in place of the assets.

Using this framework, the Court of Appeal stated that a s.9( 1) trust only arises if the value of the consideration received by the owner from the sale of assets, which have actually been enhanced by the work or materials of the contractor, surpasses the amount of the mortgage debt. A trust will not occur if the value is zero, or if the mortgage debt is equal to or above any kind of sale proceeds.

Therefore, the decision that the lower court relied upon in disallowing the trust claim does not stand for the suggestion that control by a CCAA Monitor of a sales process, or the receipt by the Monitor of the proceeds of the sale by itself, avoids a s.9( 1) trust against the proceeds of the sale of the enhancement are shown to have a positive worth that surpasses the mortgage debt on the asset. That fact pattern was absent from the case relied upon.

The decision

Now, you remember at the beginning of this blog I went through the essentially four types of insolvency proceedings. The Court of Appeal also considered the various types. The court drew a distinction in them as it relates to section 9(1) of the Construction Lien Act. Also remember that from my quotation above of this section, it starts with “Where the owner’s interest in a premises is sold by the owner…”(emphasis added).

In a receivership or bankruptcy, the owner loses control of the assets. The vendor in a sale is either the receiver/receiver and manager or the trustee in bankruptcy, respectively. In those examples, it is not the owner selling its own assets. It is the licensed insolvency trustee (formerly known as a bankruptcy trustee) selling its right, title and interest, if any, in the assets of the debtor. So the vendor is the licensed insolvency trustee in its specific capacity.

The Urbancorp matter started out as a restructuring under the Proposal provisions of the BIA and was then converted by the Court and continued under a different restructuring statute, the CCAA. In an insolvency administration under the restructuring provisions/statue, the owner does not lose control of its assets. True that the Monitor is given court authority to make decisions, market and then sell the assets. However, one of the cornerstones of the appointment of a Monitor is that the owner does not lose control of the assets and the Monitor does not become the owner of the assets.

Rather, the Monitor gets its powers from the court. The Monitor is actually selling the insolvent company’s assets as the company’s representative or agent. So even though it is the Monitor doing the selling, it is doing so on behalf of the owner. This is very different than a sale by a receiver/receiver and manager or trustee in bankruptcy.

In the Urbancorp situation, the value of the consideration received by the owner from the sale of assets, which have actually been enhanced by the work or materials of the contractor, surpasses the amount of the mortgage debt.

Highlighting these distinctions, the Court of Appeal for Ontario overturned the lower court decision and upheld the subcontractors’ trust claim. It substituted the lower court decision with an order that a s.9( 1) trust under the Construction Lien Act applies for the sum of $3,864,429 held in the accounts of the Monitor on account of the Urbancorp companies, for the benefit of the subcontractors, pro-rata in accordance with the amount owing to each of them.

Summary

I hope you found this case review helpful. It should be of particular interest to contractors, developers and builders in Ontario.

The Ira Smith Team family hopes that you and your family members are remaining secure, healthy and well-balanced. Our hearts go out to every person that has been affected either via misfortune or inconvenience.

We all must help each other to stop the spread of the coronavirus. Social distancing and self-quarantining are sacrifices that are not optional. Families are literally separated from each other. We look forward to the time when life can return to something near to typical and we can all be together once again.

Ira Smith Trustee & Receiver Inc. has constantly used clean, safe and secure ways in our professional firm and we continue to do so.

Revenue and cash flow shortages are critical issues facing entrepreneurs and their companies and businesses. This is especially true these days.

If anyone needs our assistance, or you just need some answers for questions that are bothering you, feel confident that Ira or Brandon can still assist you. Telephone consultations and/or virtual conferences are readily available for anyone feeling the need to discuss their personal or company situation.

Are you now worried just how you or your business are going to survive? Those concerns are obviously on your mind. This pandemic situation has made everyone scared.

The Ira Smith Team understands these concerns. More significantly, we know the requirements of the business owner or the individual that has way too much financial debt. You are trying to manage these difficult financial problems and you are understandably anxious.

It is not your fault you can’t fix this problem on your own. The pandemic has thrown everyone a curveball. We have not been trained to deal with this. You have only been taught the old ways. The old ways do not work anymore. The Ira Smith Team makes use of new contemporary ways to get you out of your debt problems while avoiding bankruptcy. We can get you debt relief now.

We look at your whole circumstance and design a strategy that is as distinct as you are. We take the load off of your shoulders as part of the debt settlement strategy we will draft just for you.

We understand that people facing money problems require a lifeline. That is why we can establish a restructuring procedure for you and end the discomfort you feel.

Call us now for a no-cost consultation. We will listen to the unique issues facing you and provide you with practical and actionable ideas you can implement right away to end the pain points in your life, Starting Over, Starting Now.

The Ira Smith Team is absolutely operational and both Ira, as well as Brandon Smith, are right here for a telephone appointment, conference calls and also virtual meetings.

Stay healthy and safe everybody.construction lien act

Categories
Brandon Blog Post

TOYS R US BANKRUPTCY PROTECTION IN CANADA: COURT AGREES WITH TOYS R US BANKRUPTCY COUNSEL NEGATIVE = POSITIVE

2 1920x1080 1

Toys R Us bankruptcy protection in Canada: Introduction

I want to tell you about a recent Ontario Court decision about the claims process approved in the Toys “R” Us (Canada) Ltd. and Toys “R” Us (Canada) Ltee (Toys R Us) bankruptcy protection proceedings. The Toys R Us bankruptcy protection in Canada began with the Court making the Initial Order on September 19, 2017. This Initial Order was made under the Companies’ Creditors Arrangement Act, R.S.C. 1985, c. C-36, as amended (CCAA).

On January 25, 2018, the Toys R Us bankruptcy lawyers attended in Court. There was a motion before the Court to extend the time that Toys “R” Us remains under bankruptcy protection to try to restructure. The motion was also for the Court to approve a draft claims process to quantify the outstanding creditor claims.

Toys R Us bankruptcy protection in Canada: The normal claims process

It is the claims procedure which while not novel, is also not regularly seen. That is what I want to talk about.

In a bankruptcy regulated by the provisions of the Bankruptcy and Insolvency Act, RSC 1985, c.B-3 (BIA), creditors are required to prove their claims independently. They do so by providing to the trustee in bankruptcy sworn proof of claim forms that are accompanied by supporting invoices and other pertinent documents. The detailed treatment for creditor claims to be proven and counted is not set out in the CCAA like it is in the BIA.

The Court routinely grants claims procedure orders under the Court’s general powers under ss. 11 and 12 of the CCAA. Claims process orders generally involve developing a technique to interact with all the creditors. This is so they can file their claims. It normally creates a process to communicate to (potential) creditors. It tells them that there is a process they must follow to prove their claims by a specific date.

Toys R Us bankruptcy protection in Canada: Why do we even need a claims process?

The claims process includes an opportunity for the company under restructuring proceedings, or its representative, to check all claims. The Monitor, or its representative, can disallow creditors’ claims, either in whole or in part. The claims procedure establishes an adjudication mechanism. If claims are not agreed upon and cannot be settled by negotiation, then the adjudication process begins. This could be either in court or first by arbitration. Decisions on the claims of creditors are then subject to an appeal to the Court.

Claims procedure orders will usually also set a claims bar date. Claims will not be accepted after this date. it is necessary to have a cut off to give the right numbers for voting and distribution purposes. Late claims won’t be allowed. In this way the Monitor achieves finality.

Toys R Us bankruptcy protection in Canada: Who has the most up to date books and records?

Most large businesses, including Toys R Us, have readily ascertainable payables outstanding. Sophisticated electronic systems carefully track these amounts, supervised and reviewed by the company’s senior financial staff. The electronic systems not only track purchases and payments, but also the many vendor allowances which are offsets to the accounts payable.

Such offsets include:

  • guaranteed sale provisions, which means if the product does not sell within a specific period, Toys R Us can either return the unsold items to the vendor, or take massive discounts against amounts owing for such products;
  • early payment discounts, promotional allowances, warranty fees, co-op/marketing fees and defect fees; and
  • shipping and warehousing fees

So for large companies like Toys R Us, the vendor will most likely be reconciling their books to what the company shows on its books net of the various offsets.

The recommendation to the Court was for a different type of claims process. As indicated above, the process required by the BIA is a positive one. It requires each creditor to prove the state of its outstanding claims by submitting a sworn proof of claim backed up by invoices.

The draft form of claims process submitted to the Court in the Toys R Us bankruptcy protection in Canada proceedings was a different one. It proposed to list creditor claims from the company’s books and records and to provide each known creditor with a simple claim statement. The statement would set out the amount of the respective creditor’s claim recognized by the company. If a creditor agrees with the amount that the company says it owes, the creditor need do nothing and the listed claim will become the final proven claim at the claims bar date. I call this a negative claims process.

Creditors who disagree with the amounts set out in their claims statement can file a dispute notice with the Monitor by the claims bar date to begin a review process.

ISI 4
toys r us bankruptcy protection in canada

Toys R Us bankruptcy protection in Canada: Advantages of the negative option

This negative option has certain advantages in companies such as Toys R Us. These advantages include:

  • eliminating the need for filing proofs of claim and supporting evidence in the majority of cases;
  • guarantees that known claims won’t lose out if a certain percentage of creditors to fail to file their claims on a timely basis; and
  • making the claims process streamlined; and
  • making the process easier for recognizing and counting all known creditor claims

Toys R Us bankruptcy protection in Canada: The negative option approved by the Court

The proposed claims process met the needs of the Court to ensure that any claims procedure is both fair and reasonable. The negative option claims process proposed in the Toys R Us case met the needs of the Court. The Court approved the negative claims process in the Order dated January 25, 2018.

Toys R Us bankruptcy protection in Canada: Does your company require restructuring?

Your company may not be as large as Toys R US, but it is the most important one to you. Your company may be facing financial challenges, and you have tried everything you can think of to solve the problems. But the red ink still flows. Many families rely on you and your company to continue for their survival. You have invested your money, your blood, sweat and tears in your company, and want to do everything possible to save it.

If you find your company in this situation, then you need the help of a professional trustee immediately. Call Ira Smith Trustee & Receiver Inc. If we consult with you early, we could develop a restructuring and turnaround strategy. By doing this your business will once again thrive. It may not be as complex as the Toys R Us bankruptcy protection process in Canada, but it is the most significant one for you.

Our approach for every person and company is to develop an outcome where Starting Over, Starting Now takes place. You’re just one telephone call away from taking the important actions to return to leading a healthy, balanced, and stress free life.

Contact the Ira Smith Team today.

TOYS R US BANKRUPTCY IN CANADA 0
toys r us bankruptcy protection in canada
Categories
Brandon Blog Post

STALKING HORSE BID: DO YOU REALLY WANT 2 STALK YOUR ADORABLE HORSE?

stalking horse bid
stalking horse bid

This blog was originally published on July 21, 2015. It was updated on March 22, 2021.

Bankruptcy Sales: What Is a Stalking-Horse Bid?

A stalking horse bid, in the Canadian insolvency context, is an attempt by a company (and/or its Monitor, Receiver or Trustee ) in a Court supervised insolvency proceeding, to set what will be the baseline that must be met and beaten by any other bids for the assets. The intent is to maximize the value of its assets as part of a Court supervised sales process and to discourage any bid below a certain value.

A stalking horse is a process that allows a potential buyer (the stalking horse bidder) to make a public bid for a company’s assets in order to set a floor price for the amount of money to be received by the company’s creditors in a (bankruptcy) sale. The stalking horse bidder will get to purchase the company’s assets if no other bidder comes forward. The stalking horse provision allows for the bidding process terms and conditions to be set in a court-supervised sale.

In this Brandon Blog, I describe the stalking horse bid process and how it works

What’s a stalking horse bid? Example of a stalking horse bid

According to Wikipedia:

“The term stalking horse originally derived from the practice of hunting, particularly of wildfowl. Hunters noticed that many birds would flee immediately on the approach of humans, but would tolerate the close presence of animals such as horses and cattle. Hunters would therefore slowly approach their quarry by walking alongside their horses, keeping their upper bodies out of sight until the flock was within firing range. Animals trained for this purpose were called stalking horses.”

In an insolvency context, a stalking horse bid stands to test the market to see how the market values the assets for sale. If the market values the assets less than the amount of the stalking horse bid, then no one will bid higher and the party who made the stalking horse bid will be successful in acquiring the assets.

If the market values the assets more than the amount of the stalking horse bid, the higher offers will be made for the assets and for the Court to consider for approval. Presumably, a higher offer will be approved, the purchaser will purchase the assets and the stalking horse bid will not prevail.

stalking horse bid
stalking horse bid

How a Stalking-Horse Bid Works

The stalking-horse bid method allows a distressed company to avoid receiving low ball bids as its assets are being sold. Once the stalking-horse bidder has made its offer and it has been negotiated and court-approved, other potential buyers may submit competing bids for the company’s assets.

By setting the low end of the bidding range, the insolvent company hopes to realize a higher price on its assets. Insolvency proceedings are public. The public nature allows for the disclosure of more information about the deal and the buyer than what would be available in a private deal.

Stalking-horse bidders can generally negotiate which particular assets and liabilities it hopes to acquire. After the stalking horse bid is negotiated resulting in an asset purchase agreement, it will be necessary for the company, Receiver or Trustee to obtain Court approval of not only the stalking horse bid but also for the entire sales process to be implemented.

If the company is attempting to restructure and requires “bankruptcy protection”, then those corporate proceedings would be either under the Companies’ Creditors Arrangement Act (“CCAA”) or the Proposal provisions of the Bankruptcy and Insolvency Act (Canada) (the “BIA”). In that situation, it is the company making an application to the Court with the support and assistance of the monitor or proposal trustee.

If it is a corporate receivership or bankruptcy proceeding, then it is either the receiver or bankruptcy trustee making the application. In the case of bankrupt corporations, then it is the bankruptcy court that needs to approve the stalking horse bid, the entire sales process and approve the sale.

What does it take to get bankruptcy court approval?

When applying to the Court, approval for an entire sales process is being sought, a component of which is the stalking horse agreement. The Court has various considerations in determining if a stalking horse sale process should be approved. They are:

  • Is a sale transaction warranted at this time?
  • Will the sale benefit the whole “economic community”?
  • Do any of the debtors’ creditors have a bona fide reason to object to a sale process of the business?
  • Is there a better viable alternative?”

In the event the stalking horse bid is not the successful winner because of the other potential bidders at least one made a better offer, it is normal for the stalking horse purchaser to receive some form of compensation. The compensation is for the time, cost and resources invested to perform its due diligence, to make its offer which was found to be reasonable in the circumstances and to expose that offer to the marketplace to stand as a stalking horse bid, and for that bidder to not end up as the successful purchaser.

Our Firm has been involved in situations where the stalking horse bid has been both the successful bid unsuccessful bid. If the compensation, commonly known as break-up fees, is fair and reasonable, it will not dissuade other purchasers from coming forward in the sales process, and it will also be fair to the stalking horse bidder if they are unsuccessful. It is fair to the stalking horse bidder to have these bid protections incorporated into their offer.

The Court in considering the approval of a stalking horse bid also considers if the breakup fee, and the entire stalking horse bid, has been negotiated between arms’-length parties and has the support of the stakeholders involved in the insolvency proceeding.

stalking horse bid
stalking horse bid

The Pros and Cons of Being A Stalking Horse Bidder for Assets In Bankruptcy

There are various pros and cons to being a stalking horse bidder and making the stalking horse bid. First the advantages:

  • First to tie up the company’s management, perform due diligence thereby dealing exclusively with the company for the proposed purchase of its assets.
  • Gaining the advantage of time and access to the company’s financial information.
  • Having the time to be able to understand the company’s problems and challenges.
  • Getting under contract for the assets the purchaser wants to acquire.

The cons of making the stalking horse bid are:

  • Making sure that you set the break fee high enough to fully compensate the stalking horse bidder.
  • Not having too long a time period between approval of the stalking horse bid and the time when other bids must be submitted to avoid the assets or the company’s operations worsening through the process.
  • Would it have been better not to have been the stalking horse bidder and see how the company and its assets fare before having to submit a bid?
  • If the stalking horse bidder is not a secured lender, is there a likelihood the secured lenders will bid their security which will outbid yours?
  • If there is more than one acceptable bid, then an auction process is required to determine the successful bidder. The stalking horse bidder may not wish to participate in such an auction and will end up losing out.

Can a secured creditor credit bid? Cirque du Soleil agrees to ‘stalking horse’ takeover bid from lenders worth $375M

One of the most recent high-profile successful stalking horse bids was the Cirque du Soleil insolvency proceeding under the CCAA. In that case, a takeover proposal from the Cirque du Soleil’s secured creditors has been approved as the benchmark bid for a court-supervised auction of the insolvent entertainment company.

That is called a credit bid. When the secured creditor bids all or a portion of its outstanding loan. This will be done in situations where the secured creditor believes that the value of the assets to be sold is less than the amount owed, yet the company’s assets can be used to run a viable business. In that situation, the secured creditor would rather bid its security with the company debt to take over the assets.

By making a credit bid, the secured creditor potential purchaser does not need to come up with cash for the purchase price. However, cash will be required to make certain payments to parties the company business cannot operate without and to have working capital going forward.

If they bid the full amount of their loan and get outbid in other purchase agreements, it means they get fully paid out. Otherwise, they get the assets to run the company, bring it back to financial good health and profitability. Eventually, then they will sell the healthy company to recoup their money plus make a profit.

Stalking horse bid summary

If your company is experiencing financial difficulties, don’t waste your time stalking horses or any other animal. Seek the advice of your professional advisers. The earlier you seek financial help the more options will be open to you. Contact Ira Smith Trustee & Receiver Inc. today. We’ll review your corporate issues and come up with a sound plan so that Starting Over, Starting Now you can enjoy financial peace of mind.

stalking horse bid
stalking horse bid
Call a Trustee Now!