Categories
Brandon Blog Post

Facing an Agonizing 2027 Mortgage Loan Renewal in Toronto? Do You Really Need to Sell, or Is There Another Way?

I hope you and your family are safe and well. If your Toronto or GTA mortgage loan is renewing in 2027, it is understandable to feel anxious, especially if your home has lost value, your mortgage loan balance remains high, or your income and other debts have changed. But such a renewal situation does not automatically mean that you must sell. We can look at the situation calmly, understand what is actually happening, and identify the least damaging path forward.

Key Takeaways

  • A straight mortgage loan renewal with your existing lender generally does not require you to requalify under the mortgage stress test if you remain in good standing.
  • The more serious problem usually arises when you need to refinance, switch lenders, add a second mortgage, or borrow more money.
  • Bank of Canada analysis reported in June 2026 suggested that roughly 9% to 10% of GTA borrowers renewing in 2027 may not qualify to refinance or switch lenders at current prices, compared with about 4% nationally. This does not mean that all of those homeowners will lose their homes.
  • Your realistic choices may include renewing, renegotiating, extending amortization, refinancing, using alternative financing temporarily, selling voluntarily, or addressing unsecured debt through a consumer proposal or bankruptcy.
  • If you are already behind on payments, acting before a Notice of Sale gives you more control and more choices.
  • A consumer proposal may allow you to keep your home if you can maintain the mortgage and address the proposal payments. Both a consumer proposal and personal bankruptcy require a careful review of your home equity and other assets.

Highlights

Why is the 2027 Toronto mortgage loan renewal wave causing concern?

Homeowners who bought or refinanced during 2022 and 2023 may have less equity than expected. Some also have variable-rate mortgages, extended amortizations, HELOCs, credit cards, or personal loans layered onto their housing costs.

The Bank of Canada’s June 2026 analysis, as reported by Canadian Mortgage Trends and CTV News, estimated that approximately 9% to 10% of GTA borrowers renewing in 2027 may not qualify to refinance at current home prices. The comparable national estimate was about 4%.

That statistic is often misunderstood. It concerns the ability to obtain a new or larger mortgage, not necessarily the ability to renew the existing mortgage loan with the same lender.

CMHC’s Spring 2026 Residential Mortgage Industry Report identified Ontario and Toronto as areas where mortgage arrears were increasing, while also describing the broader system as structurally stable. CMHC reported Toronto’s 90-plus-day mortgage delinquency rate rising from 0.20% to 0.29% year over year, an increase of approximately 45%.

Meanwhile, TD Economics estimated that average renewal payment increases were approximately 10% in 2025 and about 6% in 2026. The pressure is real, but it is not a reason to assume that every homeowner must sell immediately.

What actually happens when a mortgage loan renews?

A mortgage term is the period covered by your current mortgage contract. At the end of that term, you must either pay the mortgage loan off in full, renew it, or arrange another form of financing.

A straight renewal usually means:

  • You remain with your existing lender.
  • You do not increase the principal balance.
  • You do not materially change the mortgage structure.
  • You sign a new term at the lender’s offered rate.

If you are current on payments, a straight renewal with your existing lender generally does not require you to pass the mortgage stress test again. The Financial Consumer Agency of Canada recommends contacting your lender several months before renewal, negotiating the rate, and comparing available options.

A refinance is different. It generally involves increasing the mortgage loan, extending the amortization, consolidating other debts, adding a second charge, or changing lenders. The lender will assess your income, debts, property value, credit history, and debt-service ratios. The proportion of your income required to pay housing and other debts.

This is where thin equity, negative equity, arrears, or reduced income can become serious obstacles.

What are your realistic options if you cannot requalify?

1. Renew and stay put.
If the mortgage is affordable and you are current, a simple renewal may be the least disruptive option. Ask for the best available rate rather than accepting the first renewal offer.

2. Renegotiate or extend the amortization with your current lender.
A longer amortization can reduce the monthly payment. However, it also increases total interest and may keep you in debt for much longer. Use this as a measured affordability tool, not as a way to hide an unsustainable budget.

3. Refinance with a different lender.
A broker or another financial institution may offer a solution, particularly if your income and equity support it. A lender switch may involve appraisal, legal, registration, discharge, and administrative costs. Approval is not automatic.

4. Use a private or alternative lender as a stopgap.
Alternative lenders may consider borrowers who do not fit conventional bank criteria. The cost can be substantially higher, and fees, interest-only payments, short terms, and renewal charges can make the problem worse. This should be a temporary bridge supported by a credible exit plan.

5. Sell on your own terms.
Selling is not necessarily failure. If the mortgage loan is no longer affordable, an orderly sale may protect more of your equity, credit standing, and decision-making power than waiting for enforcement. Obtain a current market valuation and calculate the likely net proceeds after mortgages, commissions, legal costs, taxes, and other charges.

6. Address unsecured debt separately.
If the mortgage loan itself is manageable but credit cards, lines of credit, tax debt, or personal loans are consuming your income, a consumer proposal or bankruptcy may be a more responsible lifeline than placing more debt against your home.

Which mortgage loan renewal path may fit your situation?

PathWhat it isWho it may suitWhat happens to the home?Typical costHow long it takesMain risk
Stay and renewRenew the existing mortgage without increasing the balanceHomeowners current on payments with manageable housing costsUsually remains in the homeRate and ordinary lender chargesOften days to weeksAccepting an uncompetitive rate or payment
Renegotiate or extend amortizationChange payment structure or lengthen repayment periodOwners needing lower payments but with a viable long-term budgetUsually retainedMore total interest; possible lender or legal feesWeeksPaying more interest and postponing the underlying problem
Refinance elsewhereReplace or transfer the mortgage to another lenderOwners with sufficient equity, income, and creditUsually retainedAppraisal, legal, discharge, registration, and lender feesSeveral weeks or longerFailing approval or incurring new secured debt
Private or alternative lenderShort-term financing outside conventional bank lendingOwners with a temporary financing gap and credible exit planUsually retained temporarilyHigher interest, lender fees, broker fees, and legal costsOften weeksThe bridge becomes unaffordable or cannot be renewed
Sell on your own termsVoluntary listing and sale before forced enforcementOwners whose mortgage is no longer sustainableHome is sold voluntarilyCommission, legal costs, moving costs, and mortgage payout costsOften several weeks to monthsMarket conditions and a possible shortfall
Consumer proposalFormal settlement of eligible unsecured debts through a Licensed Insolvency TrusteeOwners whose mortgage is manageable but unsecured debt is notMay be retained if mortgage payments continue; equity affects the proposalTrustee and proposal administration costsUsually several weeks to file; payments may continue up to five yearsMortgage arrears remain outside the proposal
Personal bankruptcyFormal liquidation process for eligible unsecured debtsOwners who cannot reasonably repay debts and need a fresh startHome equity above applicable exemptions may be exposedAdministration costs and possible equity or income obligationsDepends on the circumstancesLoss or required buyout of non-exempt equity

The right answer depends on your cash flow, mortgage loan balance, home value, arrears, equity, your credit score and your other debts. It is not your hope or your worth that is being measured. It is the sustainability of the financial structure.

Toronto homeowner considering several calm, practical mortgage loan and debt-relief paths

How does power of sale work in Ontario?

A power of sale is a mortgage enforcement remedy that can allow the lender to sell the property after default without first obtaining a full court order for sale.

Under Ontario’s Mortgages Act:

  1. The lender must generally wait for the required period of default before proceeding.
  2. The lender serves a Notice of Sale setting out the default, amounts claimed, and deadline.
  3. A redemption period follows. For many mortgages with a contractual power-of-sale clause, the sale cannot occur for at least 35 days after notice. A statutory power of sale may involve 45 days’ notice.
  4. If the default is not cured, the lender may proceed with marketing and selling the property.
  5. The lender must apply sale proceeds according to legal priorities. Any remaining equity may belong to the homeowner, while a shortfall will create further liability to you, as residential mortgages tend to be “full recourse”.

A judicial sale is different. It is court-supervised, and the timeline is controlled by court proceedings and orders rather than the standard power-of-sale timetable.

Do not ignore a Notice of Sale. The precise deadline and amount required to redeem should be reviewed promptly by an Ontario lawyer. An orderly voluntary sale generally provides more control over the listing, timing, condition of the property, and communications than a forced sale.

Toronto home with a calm legal-document and calendar motif representing early mortgage loan enforcement planning

When is a consumer proposal or bankruptcy the responsible answer?

A consumer proposal may be appropriate where the mortgage loan is fundamentally affordable, but unsecured debt is making the household budget impossible. The mortgage loan remains a secured debt, meaning it is tied to the home and is not eliminated by the proposal. You must continue making mortgage loan payments.

Your Licensed Insolvency Trustee will review the home’s value, mortgage loan balance, HELOCs, other charges, income, expenses, and unsecured debts. Home equity affects what creditors expect to receive in the proposal.

Bankruptcy requires a more detailed asset analysis. Non-exempt home equity may need to be paid into the bankruptcy estate or realized through a sale. The mortgage loan also remains separate, and missed mortgage payments can still lead to enforcement.

The Ira Smith Trustee & Receiver Inc. personal bankruptcy services page explains that bankruptcy is not the only option. A confidential assessment is essential before borrowing against the home or deciding to sell.

Which options look like help but are not?

Be cautious about:

  • Debt consultants charging large upfront fees while offering no legally binding protection from creditors.
  • Private mortgages used to pay credit cards, without a realistic plan to reduce spending and debt.
  • Borrowing to keep the lights on, make minimum payments, or cover ordinary living costs.
  • Signing a second mortgage without understanding the interest rate, lender fees, renewal terms, broker fees, and enforcement rights.
  • Assuming that a consumer proposal will stop mortgage enforcement. It does not cure mortgage arrears.

We know the tension put upon you can make any immediate relief look attractive. Before signing, calculate the total repayment cost and obtain independent professional advice.

What should you do in the first 30 days?

  • Find your renewal date, current balance, interest rate, amortization, and payment history.
  • Request a current mortgage loan statement and identify every HELOC, second mortgage, lien, or secured charge.
  • Prepare a complete monthly budget, including property tax, insurance, utilities, childcare, transportation, and unsecured debt payments.
  • Obtain a realistic property valuation, not only an optimistic realtor or online estimate.
  • Speak with your existing lender early and ask what renewal, amortization, and hardship options are available.
  • Obtain independent mortgage advice before applying to multiple lenders.
  • Stop using credit to fund ordinary living expenses where possible.
  • If you have received a demand letter or Notice of Sale, speak with an Ontario lawyer promptly.
  • If unsecured debt is the main problem, book a free consultation with a Licensed Insolvency Trustee before taking on more secured debt.

The purpose of these steps is simple: early information creates choices. Delay removes them.

Frequently Asked Questions (FAQ)

Can my lender refuse to renew my mortgage loan in Ontario?
Yes, a lender may decline to renew or may require a different arrangement, although a current borrower seeking a straightforward renewal is generally in a stronger position than someone seeking new money or who is in arrears. A federally regulated lender must provide renewal information and notify you if it will not renew within the required timeframe. Ask for the decision and reasons in writing.

Will I lose my house if I cannot renew?
Not automatically. You may be able to renew with the existing lender, negotiate, refinance, sell voluntarily, or address unsecured debt separately. The risk becomes more immediate if the mortgage is in default and enforcement begins.

Can I renew my mortgage loan if I am behind on payments?
It may be possible, but arrears make the situation more difficult. Contact the lender immediately. A consumer proposal does not erase mortgage loan arrears, and a lender retains its secured-creditor rights.

Does a consumer proposal affect my mortgage?
The mortgage loan is not included in the proposal. You must continue paying it. The proposal may affect your credit and future borrowing, and your home equity can affect the amount creditors expect.

Should I sell before I go into default?
If the mortgage loan is not sustainable, selling before default may provide more control and reduce enforcement costs. But do not sell without calculating the payout amounts, selling costs, taxes, and whether there may be a shortfall.

How long does a power of sale take in Ontario?
The timeline varies. A contractual power of sale commonly has a minimum 35-day period after the Notice of Sale, while a statutory power of sale may involve 45 days. Marketing, court applications, redemption attempts, and the property’s condition can lengthen the overall process.

What if my home is worth less than my mortgage loan balance?
That is negative equity. Refinancing may be difficult, but a straight renewal with the existing lender may still be possible if you remain current. If you sell, there may be a shortfall requiring separate advice.

Starting Over, Starting Now

Don’t let financial uncertainty dictate your future. If you or your business is struggling with debt, losing sleep, or facing legal action, contact Ira Smith Trustee & Receiver Inc. today.

We offer a free, confidential consultation to discuss your situation, explain your options in plain language, and help you develop a clear, actionable plan. Our team of Licensed Insolvency Trustees is dedicated to providing the compassionate, professional support you need to regain control and achieve a debt-free life.

Take the first step towards a brighter financial future; call us now.

  • Phone: 905.738.4167
  • Toronto Line: 647.799.3312
  • Evening and Weekends: 289.670.7500
  • Website: irasmithinc.com
  • Email: ira@irasmithinc.com
    Ira Smith Trustee & Receiver Inc. is licensed by the Office of the Superintendent of Bankruptcy. Ira and Brandon Smith are members of the Canadian Association of Insolvency and Restructuring Professionals.

————————––

Disclaimer: This analysis is for educational purposes only and is based on the cited sources and professional expertise as a Licensed Insolvency Trustee. The information provided does not constitute legal or financial advice for your specific circumstances. Every situation is unique; the outcomes discussed may not apply to your particular case. Please contact Ira Smith Trustee & Receiver Inc. to discuss your specific needs.

About the Author:

Ira Smith is President of Ira Smith Trustee & Receiver Inc. and a Licensed Insolvency Trustee serving individuals and businesses across Ontario. Ira provides practical guidance on personal bankruptcy, consumer proposals, corporate restructuring, receiverships, and other complex financial situations. His approach centres on helping clients understand their options, reduce uncertainty, and begin Starting Over, Starting Now.

Toronto homeowner reviewing a mortgage loan renewal letter and household budget at a kitchen table

#MortgageLoan #TorontoMortgage #MortgageRenewal #GTAHomeowners #MortgageStress #OntarioPowerOfSale #ConsumerProposal #PersonalBankruptcy #DebtRelief #FinancialFreshStart #StartingOverStartingNow
Categories
Brandon Blog Post

DEFAULTING ON A MORTGAGE: THE BEST COURT-APPROVED WAY TO DEBT FREEDOM IN 2020 & BEYOND

The Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.

Defaulting on a mortgage introduction

I just finished reading a defaulting on a mortgage decision of the Ontario Superior Court of Justice released on September 15, 2020. It had to do with a person who had filed a proposal under the Bankruptcy and Insolvency Act (Canada) (BIA). The court case is about the debtor who could not afford to pay all the mortgages on her home. The home was sold on a conditional basis, and a dispute occurred between two potential purchasers. I describe below how the court dealt with the dispute.

That case highlighted for me three things:

  • what we advise everyone who comes to us for a no-cost initial consultation who cannot afford to keep paying a loan registered against an asset, normally a vehicle or house;
  • how sometimes a strategic default on a mortgage or vehicle loan can help someone in dealing with all of their debts when they are about to file either a proposal or for bankruptcy; and
  • the appropriate manner (in my view) the court decided to resolve the dispute between the two potential purchasers.

Defaulting on a mortgage: What we advise debtors

Whenever someone comes to us for a no-cost consultation, we first get financial information from them. We want to understand the nature of their assets and liabilities and their household income and expenses. Through our analysis and discussion, we determine if the person can afford to keep paying that loan or mortgage. We also ask them, if appropriate, are they happy with the asset if it seems that they are paying too much based on the level of secured debt and the market value of the asset.

If the person says they would love to get rid of the asset, that they have no or little equity in, then we look at the impact of using defaulting on a mortgage as a strategic default so that any shortfall experienced by the lender will be an ordinary unsecured debt which can be discharged through either a proposal or bankruptcy.

Obviously, the person has to have a realistic option to replace that asset or have an alternate plan:

  • Can they lease a different vehicle at a lesser cost before filing which they can afford and therefore will not default on?
  • Is public transit a realistic option as opposed to having their own vehicle for the time being?
  • Is there a relative who will co-sign for them so that they can lease or buy a more reasonable cost vehicle?
  • Can they rent somewhere that they can afford for much less than what they have been paying on their home and then look at buying something after they are through their debt restructuring when they are back on their feet?

As I said, we do this all the time when working with people to look at all of their options for financial restructuring. We especially look at in the case of a home, does defaulting on a mortgage make financial sense?

Defaulting on a mortgage: What is a strategic default?

When the market value of your home is less than the amount owed on the mortgage, that mortgage debt is underwater. To put it simply, an underwater home mortgage loan has a higher remaining principal balance than the value of the house.

Homeowners with little or negative home equity can find themselves in this situation when housing prices fall, even if they are current on all their payments. It’s also described as being “upside-down” or having “negative equity” in the residence.

When it doesn’t make sense to keep using your cash to stay current on that underwater mortgage, rather than using that money for other necessary expenses, defaulting on a mortgage as a strategic default may be your only option. After establishing that you can’t see your property rising in value in a reasonable period to restore some of your equity, you may plan to just stop making mortgage repayments. You’ll default and eventually, the lender will enforce on its mortgage, take over the property and sell it.

Even if you have equity in the home, but you can no longer afford to keep up the payments, you may find that putting your home up for sale is your best option. Again, you need to have a realistic plan in place on where you will live once your home sells. Depending on the situation, you might decide to also create a strategic default by defaulting on a mortgage at the same time you list your home for sale. Once sold, the net proceeds of the sale, representing the equity in the home, can be used to help fund the proposal.

During the financial crisis in the United States, a strategic default on underwater homes by defaulting on a mortgage became progressively typical. Such home loans came to a head at 26 percent of all mortgaged homes in 2009. Many house owners did the math and made the agonizing however rational decision to leave the home and let the lender deal with the property and its underwater mortgage.

As I explain in the next section, in most cases, you can just walk away from such a loan in the United States. Unfortunately, it is not so easy for Canadians to walk away from their homes and defaulting on a mortgage. But there is one way to do it in Ontario.

defaulting on a mortgage

Defaulting on a mortgage: Walking away from a mortgage in Canada is not simple

In the United States, it is normal for a mortgage to be “non-recourse“. What this means is that the lender can only look to the value of the property it has mortgage security against to repay the mortgage loan. If the lender suffers a shortfall, unless there is a separate guarantee given, the lender cannot sue the mortgagor, the borrower, for any shortfall. So if you have negative equity, defaulting on a mortgage may be the right decision for such a US resident.

In Canada, it is normal for a mortgage to be “full recourse“. This means that if the lender suffers a shortfall on the mortgage debt, the terms of the mortgage loan automatically allows the mortgagee, the lender, to go to court and get a judgment against the borrower for the amount of the shortfall. So defaulting on a mortgage needs to be done in conjunction with a plan to deal with the shortfall debt.

For this reason, walking away from a mortgage in Canada is not simple. However, there is one way to do it. Once the shortfall is known and, either before or right after the lender gets a judgment, the debtor can file a proposal under the BIA to restructure all their unsecured debt. If that is not practical, then bankruptcy is the other option.

Now the shortfall is caught in the insolvency proceeding. The filing invokes an automatic stay of proceedings so that the lender cannot take action to try to execute against any of the assets or income of the debtor who has filed. The debt is caught in the insolvency proceeding and will be dealt with in that forum.

Defaulting on a mortgage: The first sale

The court case deals with a woman in Ontario who had begun a proposal process under the BIA. The debtor owned (at least) two residential properties. The property in question had 4 mortgages registered against it. The other property had multiple mortgages against it, including a mortgage as additional security for the 4th mortgage loan against the property in question. To make matters worse, there was also a lien registered against the same residential property in favour of the Canada Revenue Agency (CRA) in the amount of $308,258.

The 4th mortgage was totally underwater. The debtor entered into an agreement of purchase and sale. The sale of the home would result in a shortfall of over $700,000. It would not provide any funds for the 4th mortgage. It would only partially repay the 3rd mortgage. So, one of the conditions of sale was that the vendor would either get a discharge of all of the mortgages or a court order vesting title in the home to the purchaser clear of all mortgages and other registrations against the title. The 4th mortgagee’s charge against the other home, which was also in 4th position, was also totally underwater.

As part of the proposal proceedings, the debtor brought a motion to the court to approve the sale (supported by appraisals) and get the vesting order to vest title clear of all registrations against the title. The debtor was not only going to be defaulting on a mortgage but on at least 2 of them!

Defaulting on a mortgage: The 4th mortgagee opposes the sale approval motion

The 4th mortgagee appeared at the motion with her lawyer to get an adjournment in order to oppose the authorization and vesting order and enable her to acquire the home on the same terms but also for even more money. This would enable the 4th mortgagee to possibly recover something on her outstanding mortgage loan at a later date.

The purchaser or the purchaser’s lawyer was not told in advance that there was going to be an opposition to the application. Therefore, the purchaser’s lawyer did not attend the hearing.

At the hearing, the court authorized the sale and vesting order yet suspended its issuance for 9 days to allow the 4th mortgagee the chance to make an offer. She did, on the very same terms yet $5,000 greater than the approved offer. She also had the deposit funds put into her lawyer’s trust account. She then made a motion for the approval of her offer and vesting order. Not surprisingly, and as to be expected, the first purchaser objected to her motion.

Defaulting on a mortgage: What the court decided

The 4th mortgagee’s lawyer argued that the first purchaser’s agreement of purchase and sale is nullified since there was neither discharges provided nor a binding court order vesting title free and clear from all mortgages and the CRA registration by the closing date. Therefore, it cannot now come to court and try to extend the closing of a deal that is already dead.

Legal counsel for the first purchaser argued that if the court approves the 4th mortgagee as the buyer, the sales procedure will be unfair. The first purchaser was not notified that there would be any type of objection to its motion for the approval and vesting order of its deal. Although the first purchaser can be criticized for not keeping up with what was happening both before and on the date of its court motion, it is still a good-faith buyer who took part in a fair sales process. The 4th mortgagee had every right to bid on the subject property when it was initially listed and did not do so.

The court decided that ultimately, this situation boils down to the process being fair and seen as being fair. So given all of this, the court decided:

  • All previous agreements of purchase and sale for the subject property are terminated.
  • A new sales process will be carried out where any of the interested parties, being the first purchaser and the 4th mortgagee, can send their best offers to the Trustee, on a confidential basis.
  • The offers are to be submitted and evaluated by the Trustee by September 18, 2020, with the closing of September 25, 2020.
  • In the event, the winning bid is not able to close on September 25, 2020, the other party may purchase the property.
  • If court approval of the successful offer and a vesting order is needed, a draft order may be provided to the court.
  • The proceeds of the sale, presumably net of the realtor commission, the vendor’s real estate legal fees, and any HST that may be applicable on the sale, are to be paid into court in order to figure out the proper amount and priority of the charges against the property.

As neither side was totally successful, the court did not award costs to any party. This seems to be the fairest outcome to all concerned.

Defaulting on a mortgage: A proposal is your best option

So as you can see, it is possible to use the proposal process under the BIA either to sell a home you can no longer afford to keep which has equity. The net sales proceeds can be used to partially fund the proposal. A proposal under the BIA is the only government-approved debt settlement plan.

Alternatively, you can use the proposal process to sell the home where you are defaulting on a mortgage where there are one or more mortgages underwater. The proposal process will compromise the resulting ordinary unsecured debt arising from the shortfall claim of underwater mortgage lenders. An application can be made to the court for an order approving the sales process, the sale, and obtaining a vesting order to complete the sale.

We have helped many people and companies do exactly that when defaulting on a mortgage.

Defaulting on a mortgage summary

I hope you have enjoyed this defaulting on a mortgage Brandon’s Blog. Hopefully, you have better insight now into the fact that there is a way to get out of a secured loan, especially a mortgage. It will require an insolvency proceeding to settle all your debts, including any shortfall on the sale of the secured asset.

Do you have too much debt? Are you in need of financial restructuring? The financial restructuring process is complex. The Ira Smith Team understands how to do a complex restructuring. However, more importantly, we understand the needs of the entrepreneur or the person who has too much personal debt.

You are worried because you are facing significant financial challenges.
It is not your fault that you are in this situation. You have been only shown the old ways that do not work anymore. The Ira Smith Team uses new modern ways to get you out of your debt troubles while avoiding bankruptcy. We can get you debt relief freedom.

The stress placed upon you is huge. We understand your pain points. We look at your entire situation and devise a strategy that is as unique as you and your problems; financial and emotional. The way we take the load off of your shoulders and devise a debt settlement plan, we know that we can help you.

We know that people facing financial problems need realistic lifeline. There is no “one solution fits all” approach with the Ira Smith Team. That is why we can develop a restructuring process as unique as the financial problems and pain you are facing. If any of this sounds familiar to you and you are serious in finding a solution, contact the Ira Smith Trustee & Receiver Inc. team today.
Call us now for a free consultation.

We will get you or your company back on the road to healthy stress-free operations and recover from the pain points in your life, Starting Over, Starting Now.

The Ira Smith Trustee Team is absolutely operational and Ira, in addition to Brandon Smith, is readily available for a telephone consultation or video meeting. We hope that you and your family are safe and healthy.

defaulting on a mortgage

Categories
Brandon Blog Post

DIMINISHED CAR VALUE CLAIM: ARE CAR AND TRUCK DEALERSHIPS FORCING YOU TO CAR LOAN DEBT CONSOLIDATION BECAUSE OF DIMINISHED CAR VALUE

2

Diminished car value claim: Introduction

You need to know just how car and truck manufacturers and dealerships have achieved higher sales in Canada. By forcing a diminished car value claim on you. Everything starts with pitches like this: 112 bi-weekly at 0%, reduced payments extended over a longer time period. Over half of brand-new vehicle loans are for 7 years or longer. This is a huge change from exactly what was the standard for perhaps 5 years.

Diminished car value claim: What is the best term for a car loan?

The very best time period for an auto loan, on average, is no greater than 5 years. If you are the type of person that hangs on to your car for a very long time, then you could also opt for a 7 or 8 year loan. Regardless of your choice, the key is that you have to hang on to your car for at least the length of the loan.

Letting go of your car earlier than when the loan is fully paid off, either through a forced sale, accident write-off or trade-in for a new set of wheels, will cause you to suffer the dangers of negative equity. This will produce a diminished car value claim. Continue reading below as I make the case.

Diminished car value claim: “Oh I could manage that vehicle payment”

Canadians have purchased much more pricey cars and trucks as a result of those reduced monthly payments. The typical customer sees that they believe “Oh I could manage that vehicle payment, I could handle that no worry”. For the vehicle manufacturers and dealers, it is simply an extra means of bringing customers right into the car dealership. They are marketing them something that they actually cannot pay for. It doesn’t take much to produce a diminished car value claim.

Diminished car value claim: A recipe for problems

Seven year financing, “that to me is short-sighted just a recipe for problems” says John Carmichael, Chief Executive Officer of the Ontario Motor Vehicle Industry Council (OMVIC). Salesmen ought to be discussing all the financing choices and the dangers of the financing choices and negative equity. Customers need a lot more information about a diminished car value claim. Thus people can easily get involved in a treadmill of debt.

Diminished car value claim: There is so much negative equity in a car being financed

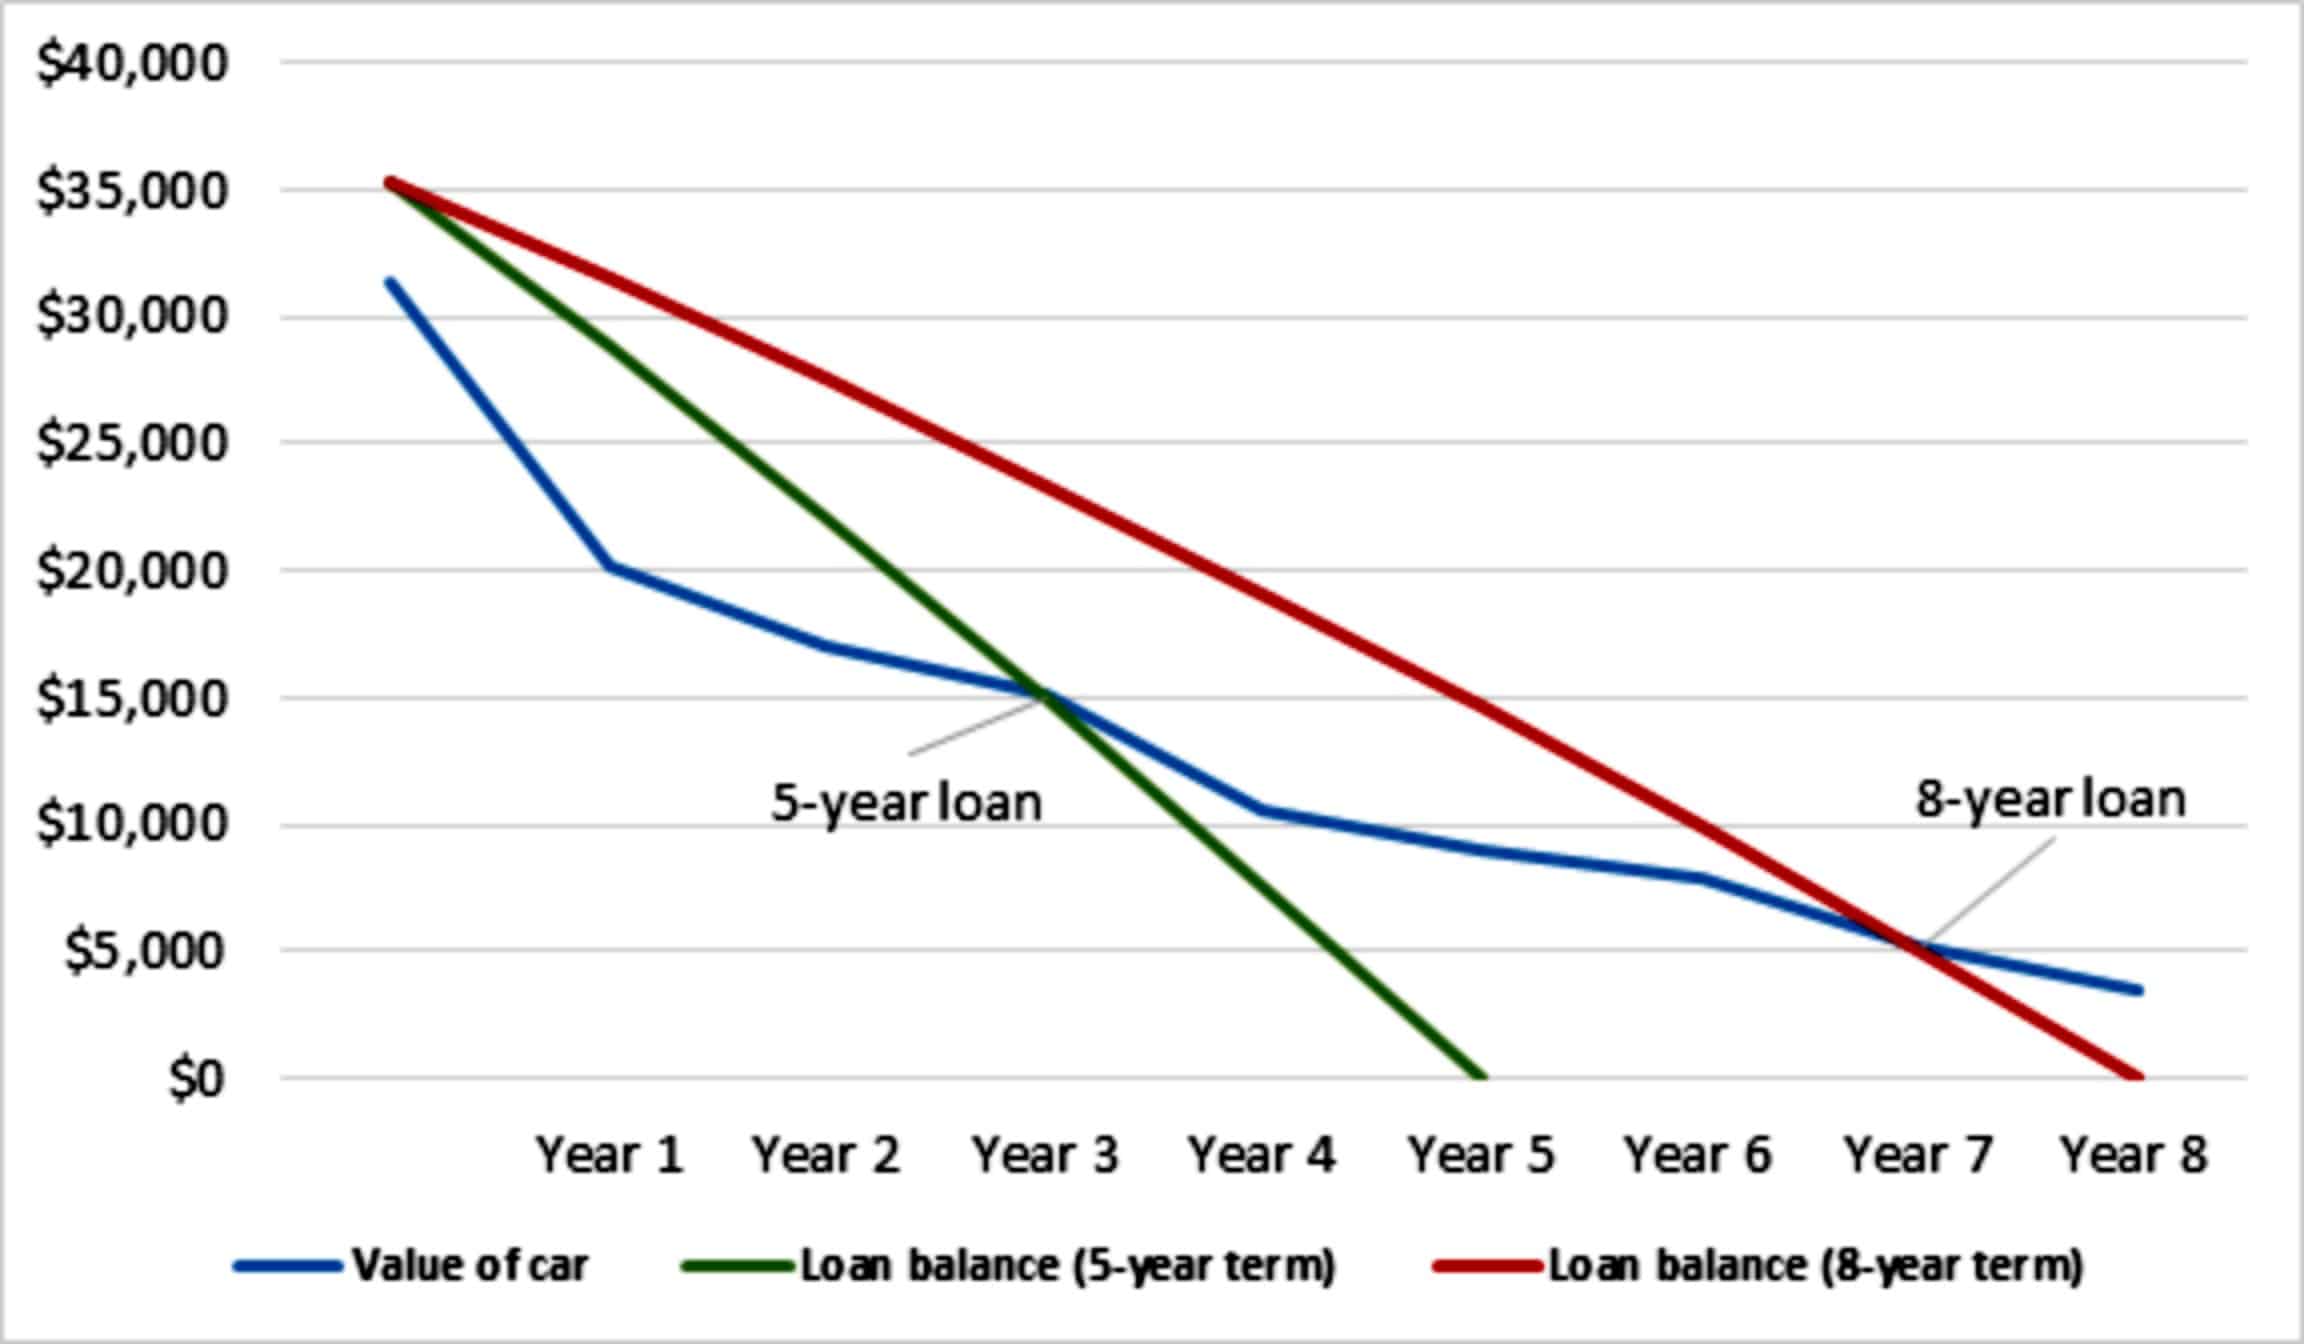
Let me show you an example of how a diminished car value claim works. Here is a negative equity comparison on a $31,300 car with a 4% interest rate.

Source: Government of Canada, Financial Consumer Agency of Canada

diminished car value
diminished car value claim

This chart highlights 2 vital factors:

  1. With five-year financing, you would not start gathering “favourable or positive equity,” until completion of the 4th year. By comparison, with an eight-year term, you would stay in an adverse or negative equity circumstance up till the 7th year of your financing.
  2. Negative equity has the tendency to be greater in the first 2 years of an auto loan. This is since automobiles drop rapidly in the very first year of use. Thus, a bigger section of each of your payments goes to interest in the very first couple of years.

You can find a diminished car value calculator website online. You can calculate how much negative equity you have in your vehicle for free online.

Diminished car value claim: The economic dangers of negative equity

If something unforeseen occurs and you should have to offer your auto for quick sale, you will probably lose on the loan. What you will be able to sell the car for will be less than what you owe on it. If this were to happen, you would need to have to put your hands on cash to cover your loss, i.e. the difference between the sale price and what you still owe on it.

If you are in an accident and your insurance company tells you that your car is a write-off, the cash you get from the insurer won’t cover what you still owe on your vehicle loan unless you have added insurance policy protection. Then if your insurer decides the current value of your auto is $10,000 however you still owe $16,000 on your financing, you will be required to cover the $6,000 shortage.

If your car is worth less than the amount you owe on your vehicle loan and you trade-in your vehicle at a car dealership to purchase another, you could wind up paying a great deal of extra money. You would spend for the brand-new car and have to cover the amount still owing on the old loan.

All these examples show how you could be forced to part with your car before you planned to. You will be taking on more debt because your vehicle was worth less than the amount of the loan against it. This would amount to a bigger financing and even more interest costs.

This will then snowball to produce a larger negative equity on your new vehicle because you are starting with a loan equal to more than your new car is worth. That is if you can find someone who would even lend on that basis to you. Certainly they would need more than just the new car as collateral.

Diminished car value claim: What to do if you have debt problems

Do you have debt problems, negative equity in your vehicle and zero or not enough equity in your other assets? If so, you need professional help and you need it now. More debt isn’t an answer for you. Don’t seek out a car loan debt consolidation lender.

Contact the Ira Smith Team. We can help you get out of your debt problems. We will put you back on track for debt and stress free living Starting Over, Starting Now. Book an appointment for a free, no obligation consultation today and take the first step to ending the cycle of debt.

diminished car value claim 0
diminished car value claim
Call a Trustee Now!